What You Actually Need to Know Before You Open a Single Page
The Business Exit Exam Study Guide is one of those things everyone tells you to take seriously, then nobody explains what it actually tests until you're already halfway through a chapter on accrual accounting and realize you don't know why it matters for the exam. I went through this process twice — once trying to wing it, once doing it properly. The difference was roughly a 40-point gap on my score, which is enough to either pass or trigger a remedial retake at most institutions. Here's the thing nobody puts on the first page of any PDF they sell you: the exam doesn't test whether you can define terms. It tests whether you can apply them under time pressure. There's a meaningful difference. I spent three weeks memorizing balance sheet formulas, then on exam day they gave me a scenario where the answer required me to figure out which items didn't belong on a balance sheet at all. I froze. Not because I didn't know accounting. Because I'd studied for a different test than the one I was taking. Let me walk you through how this actually works, what you should spend time on, and where most people waste weeks they don't have.
Business Exit Exam Study Guide: How to Use It Without Wasting Your Time
Start by understanding the exam's structure before you open anything called a study guide. Most business exit exams follow a similar pattern — multiple choice questions covering financial accounting, managerial accounting, business law, economics, and sometimes quantitative reasoning. The total question count runs between 100 and 150 depending on your institution. Time allocation is usually somewhere around 2.5 to 3 hours. That means you have roughly 100 seconds per question. Not a lot of time to second-guess yourself. I picked up a Business Exit Exam Study Guide from my university's bookstore and immediately started reading cover to cover. Bad move. I got through about 80 pages before I realized I was absorbing information passively — I understood it while reading, which is not the same as being able to retrieve it under exam conditions. Switched tactics after that. Started doing practice problems first, then went back to the text only for topics I got wrong. This cut my effective study time in half and actually improved my retention because I was targeting weak spots instead of reinforcing things I already knew. Here's a specific problem I ran into that I couldn't find help for anywhere online: the economics section of my exam had a heavy emphasis on elasticity calculations, but none of the study guides I found dedicated more than two pages to it. I spent an hour searching past exam forums and finally found a professor's old syllabus that listed the exact weightings. Economics was 15% of the exam, and elasticity alone accounted for roughly 40% of those economics questions. I adjusted my study schedule accordingly and stopped wasting time on macroeconomic theory that barely showed up.
If you're looking for a Business Exit Exam Study Guide, the official one from your institution's testing center or academic affairs office is always the starting point. Third-party guides can help, but they often extrapolate or generalize content from different versions of the exam. My recommendation: get the official guide, supplement it with practice questions from your school's question bank if one exists, and then use a third-party resource only for topics you're struggling with specifically.
Get the Full Details
The Topics That Actually Show Up (And The Ones That Don't)
Financial accounting tends to be the heaviest section. You need to be comfortable with journal entries, adjusting entries, trial balances, and financial statement preparation. The depth goes beyond introductory level — expect questions that require you to identify errors in a partially completed set of statements or determine how a specific transaction affects multiple line items simultaneously. This is where most students lose points because they've only ever worked with clean, simplified problems. Managerial accounting covers cost behavior, break-even analysis, budgeting, and variance analysis. Break-even questions show up consistently across every version of this exam I've seen. You should be able to calculate it from memory and explain what happens to the break-even point when fixed costs change or when variable costs per unit shift. These are almost always single-concept questions that don't require elaborate calculations, which means they should be quick points if you've memorized the formula and practiced applying it a few times. Business law is the section most people dread and honestly shouldn't. The questions tend to be scenario-based rather than definition-based. You'll read a short paragraph about a contract dispute or a liability issue and pick the most legally correct answer. Contract formation, agency relationships, UCC provisions for sales of goods, and basic corporate structure are the core topics. I found that drawing out simple diagrams for agency relationships — principal, agent, third party — made the questions significantly easier to unpack during the exam.
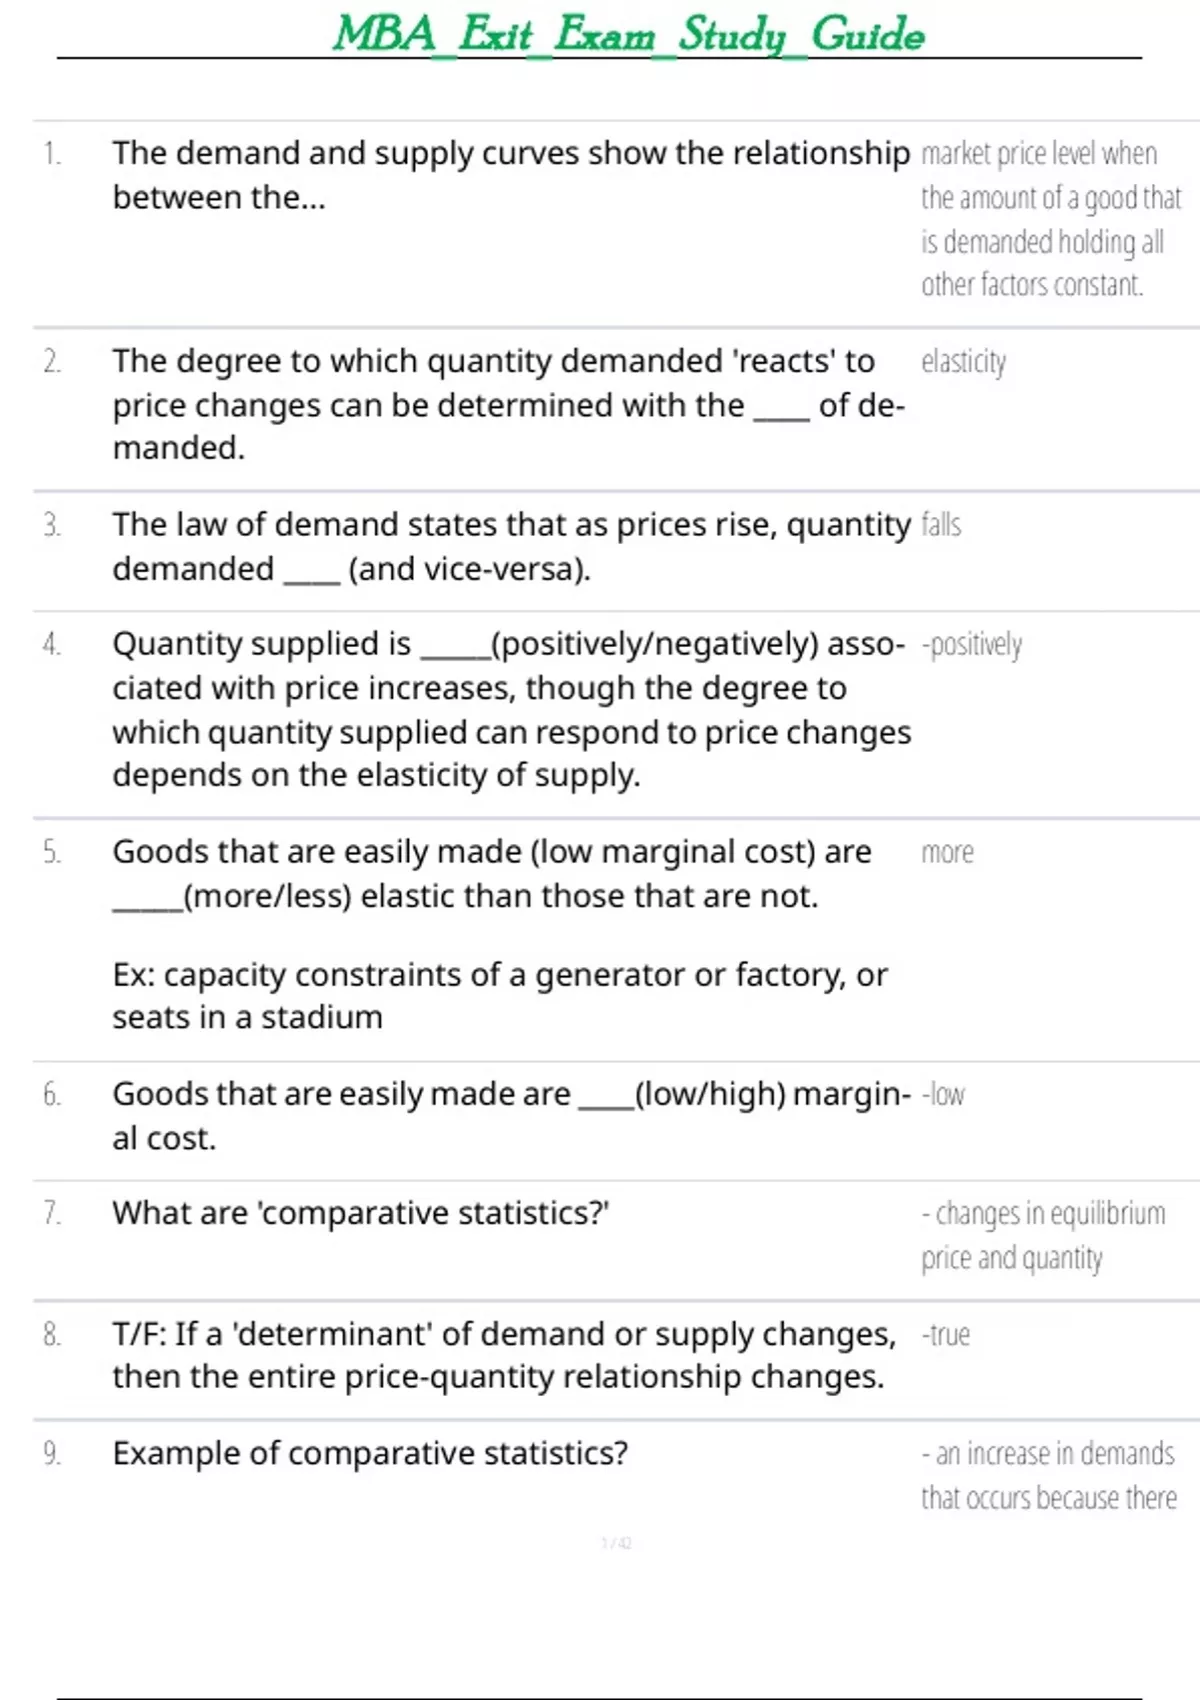
Economics splits between micro and macro, but micro tends to dominate. Supply and demand shifts, market structures, elasticity, and externalities are the recurring themes. Macroeconomics questions usually focus on GDP calculation methods, fiscal versus monetary policy tools, and inflation measurement. If you're weak in economics like I was, don't try to relearn the entire semester in two weeks. Focus on the topics that appear most frequently and accept that you might not master everything. Passing this section rarely requires knowing everything — it requires knowing the right things well enough to eliminate wrong answers quickly.
How I Actually Studied (The Method That Got Me Through)
My study routine broke down into three phases over about six weeks. Phase one was diagnostic — I took a full practice exam cold, no studying, just to see where I stood. Scored about 58%. Brutal but useful. I identified my three weakest areas: elasticity calculations in economics, adjusting entries in accounting, and contract law in business law. Phase two was targeted study. I spent roughly 60% of my time on those weak areas and 40% maintaining my stronger subjects. For each weak area, I did this: read the relevant section in the Business Exit Exam Study Guide, immediately do ten practice problems on that topic, check my answers, then re-read only the parts I got wrong. This feedback loop is what actually builds competence. Most people skip the practice problems and just re-read, which creates a false sense of mastery. Phase three was practice under real conditions. I took three full-length practice exams in the final two weeks, each timed and without notes. The first one I scored 67% on. The third one was 82%. The improvement came from recognizing question patterns and learning when to skip and come back rather than burning 3 minutes on a single problem. Exam strategy matters as much as content knowledge, and nobody teaches you that until you're sitting there staring at a question you don't know and watching the clock tick.
What Most Study Guides Get Wrong
The biggest flaw in most Business Exit Exam Study Guide materials is that they over-index on breadth and under-index on application. They'll give you ten pages defining every type of business organization and two paragraphs on how to actually analyze a case study involving partnership dissolution. The exam tests the latter. Read definitions, sure, but spend your energy on applied problems. Another common issue: outdated content. I used a guide that was two years old and it included a section on a tax law change that had been reversed before my exam date. Not a huge deal, but it confused me during the test because I'd prepared for something that didn't exist anymore. Always check the publication date and cross-reference with your institution's current course syllabi. There's also the problem of practice questions that are too easy or too hard relative to the actual exam. Some third-party guides write questions that are either comically straightforward or artificially complex. The real exam sits in a middle ground — questions that require you to think but don't require you to work through five steps of unnecessary complexity. If your practice questions consistently feel impossible or trivially easy, your resource might not be well-matched to the actual exam difficulty.
A Few Things I Wish Someone Had Told Me
First, the exam is adaptive in certain sections at some institutions, meaning your performance on early questions can influence the difficulty of later ones. This isn't universal, so check with your program coordinator, but if it applies to you, getting the first several questions right establishes a higher baseline and can make the rest of the section more manageable. Second, don't ignore the quantitative reasoning portion if your exam has one. It's usually a smaller section, maybe 10 to 15 questions, but it's the part where students who are strong in business content but rusty on math can lose easy points. Basic algebra, ratios, percentages, and data interpretation are the skills tested. A quick refresher on these going in is worth far more than the time it takes. Third, sleep and timing matter more than an extra hour of studying. I pulled one all-nighter before my first practice exam and scored worse than I did the day after a normal night's sleep. Cognitive fatigue hits retrieval speed first, and this exam rewards speed. Seven hours of sleep before study days and exam day is non-negotiable if you want your brain to work at the level you're capable of.
If you're searching for a Business Exit Exam Study Guide right now, start with what your school provides, fill gaps with practice questions from reputable sources, and spend more time doing problems than reading text. The exam is passable with focused effort, but it punishes vague, passive studying pretty severely. Good luck.