How Business Line Of Credit Underwriting Guidelines Actually Work On The Ground
Most people think underwriting is just about checking boxes on a form. It's not. I've spent years watching credit teams move files through review, and the gap between what the guidelines say and what actually happens is where most deals either go sideways or get quietly approved through sheer momentum.
When I first started digging into Business Line Of Credit Underwriting Guidelines, the official documents read like a checklist: pull the credit report, verify two years of business history, calculate debt service coverage, set a utilization threshold, and you're done. In practice, it's messier than that. Lenders care about the same surface metrics, sure, but the real decision-making happens in the gray areas between them.
I remember one file from about three years ago that perfectly illustrates this. A mid-market manufacturing client applied for a $750,000 revolving line. Their DSCR came in at 1.18, which sits just below the typical 1.25 comfort zone most underwriters target. Their credit score was solid, cash flow was consistent, but there was a recent dip in revenue during Q2 that brought down their trailing twelve-month average. A rigid adherence to the guideline would have sent this one to reject. Instead, I pulled the month-by-month breakdown, found that Q2 was entirely seasonal — their business ships primarily to holiday retailers — and restructured the underwriting around their actual operational cycle rather than the raw TTM figure. The line got approved, and they've been paying on time for two years now. The guideline didn't account for seasonality, but the human reading the file had to.
Core Components of Business Line Of Credit Underwriting Guidelines
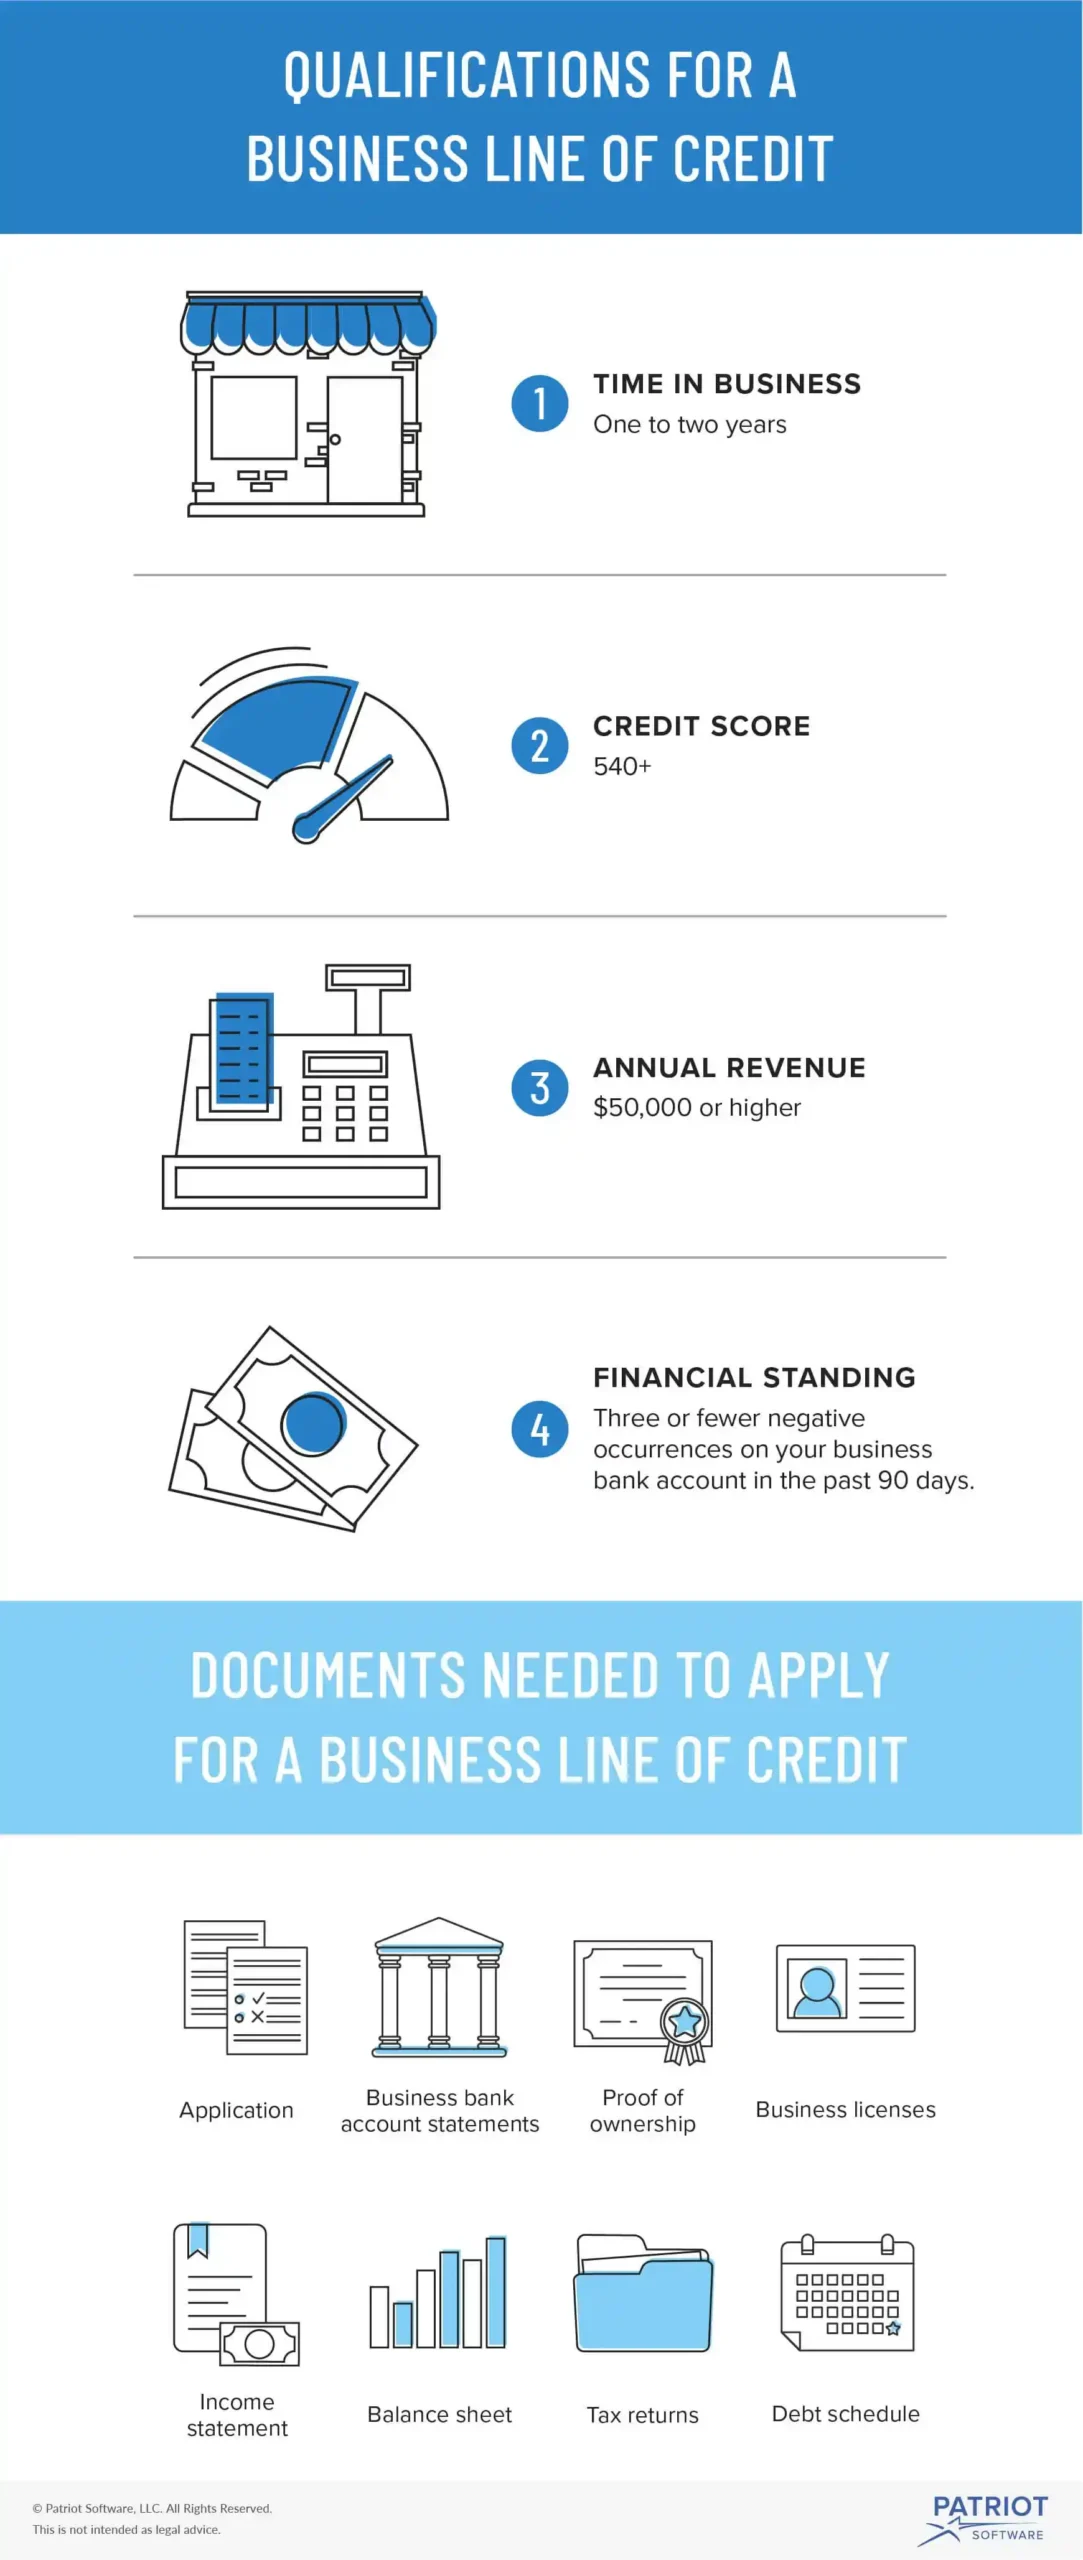
The foundational layer is always financial qualification. That means reviewing the business credit profile, personal guarantees, and the company's debt obligations. Lenders typically want to see a minimum credit score ranging from 680 to 720 for conventional lines, though specialty lenders may stretch that lower if the overall picture is compelling.
Then there's the revenue verification piece. Most institutions require at least $100,000 in annual gross receipts, though the exact threshold depends on the product and the lender's risk appetite. You'll need two years of tax returns, usually both the business and personal ones, plus recent bank statements showing the cash flow that supports repayment capacity.
Debt service coverage ratio is where things get technical. You're calculating whether the business generates enough operating income to cover its existing debt payments plus the new credit line obligation. The formula is straightforward — net operating income divided by total annual debt payments — but applying it correctly requires knowing what numbers to include and what to adjust for. Add-backs matter. Things like one-time expenses, owner compensation above market rate, or non-recurring losses can inflate or deflate your real capacity if you don't account for them properly.
Collateral and personal guarantees form the safety net. Unsecured business lines exist, but they're expensive and come with lower limits. Most lenders will want a blanket lien on business assets as collateral for lines above $100,000, and they'll almost always require a personal guarantee from the owner regardless of size.
The Hidden Variables That Actually Move Decisions
Industry classification matters more than most people realize. Lenders segment businesses into risk buckets based on NAICS codes, and some industries carry automatic red flags or preferential treatment depending on the lender's portfolio. A restaurant applying for a line of credit faces different scrutiny than a software company with recurring revenue, even if their financials look identical on paper.
Payment history on existing credit is scrutinized aggressively. Not just whether bills get paid, but how they get paid. Consistent early payments tell a different story than payments made on the due date or occasionally late. Automated payment systems are usually viewed favorably because they signal organizational maturity and reduce the likelihood of accidental mismanagement.
Bank statement analysis has become the standard replacement for traditional document-based underwriting at many lenders. Instead of relying solely on tax returns, which reflect the past, lenders now look at 6 to 12 months of bank statements to assess real-time cash flow patterns. This shift has made underwriting faster but has also introduced new challenges around interpreting cash flow that varies significantly from month to month.
The relationship factor is real and worth acknowledging. Clients who have an existing banking relationship with the lender, especially one that includes deposit accounts and payment processing, often receive more favorable terms. This isn't always written into any formal guideline, but it's a consistent pattern across institutions.
Where The Guidelines Break Down In Practice
The biggest limitation of standard Business Line Of Credit Underwriting Guidelines is that they were designed for stable, traditional businesses with predictable cash flow. They don't translate well to seasonal operations, project-based revenue, or companies in rapid growth phases where current financials don't reflect earning potential.
Startup businesses face a structural problem here. Most traditional guidelines require two years of operating history, which excludes newer companies that may have strong growth trajectories but insufficient track records. SBA lenders and some community banks offer alternatives, but the guidelines differ significantly from standard commercial line products.
Another blind spot is the treatment of concentrated revenue. If a single customer represents more than 20 to 25 percent of gross revenue, many guidelines don't have a clear pathway for evaluating that risk properly. The conservative approach is to discount that revenue, but the right approach depends on the relationship quality, contract terms, and industry norms — factors that a spreadsheet-based guideline can't capture.
Underwriters also tend to undervalue intangible assets and intellectual property in the collateral assessment. A software company with proprietary technology might appear weaker on a traditional underwriting worksheet than a similar company with equipment to pledge, even though the technology could represent significantly more value. This is a persistent bias in the system.
What To Prepare Before You Submit
Organize your documents before you start the application process. Most lenders will ask for the same core items: business and personal tax returns for the past two years, year-to-date profit and loss statement, balance sheet, accounts receivable and payable aging reports, and six to twelve months of business bank statements. Having these ready in advance usually cuts the initial review time substantially.
Write a brief narrative explaining any anomalies in your financials. If your revenue dipped last quarter, if you acquired a new customer in the last six months, or if there's a one-time expense that inflated costs, address it proactively. Underwriters appreciate being handed context rather than having to excavate it.
Know your numbers before the underwriter asks. Your DSCR, your debt-to-income ratio on the personal guarantee, your average monthly cash balance, and your current utilization on existing credit lines. When you can provide these figures immediately, it signals that you understand your business financially, which builds confidence with the reviewer.
Be realistic about the amount you need. Applying for significantly more than your documented capacity raises questions. Lenders typically set line amounts between 25 and 50 percent of annual gross revenue for conventional business lines, though this varies by industry and financial strength. Requesting an amount well outside this range without strong justification often triggers additional scrutiny that slows the process.
Common Reasons Lines Get Denied or Reduced
Short credit history is the most common rejection reason for newer businesses. Even if your revenue looks good, a history shorter than two years raises uncertainty for underwriters who rely on trend data.
High existing leverage relative to cash flow is another frequent blocker. If your total monthly debt payments already consume a large portion of your operating income, adding a new line increases risk beyond comfortable thresholds for most lenders.
Insufficient or unstable cash flow stands out in bank statement reviews. Lenders look for consistent deposits that cover operating expenses with room to spare. Businesses that show irregular cash patterns, even with adequate annual revenue, can raise concerns about repayment ability.
Negative items on the credit report — collections, late payments, or high utilization — directly impact the personal guarantee assessment since most business lines require one. These don't always disqualify you, but they reduce the available line amount or push you toward higher-cost products.
Outdated or incomplete documentation stalls applications more often than outright rejections. Underwriters can't make decisions on missing information, and resubmitting documents adds days or weeks to the timeline.
Gallery Business Line Of Credit Underwriting Guidelines
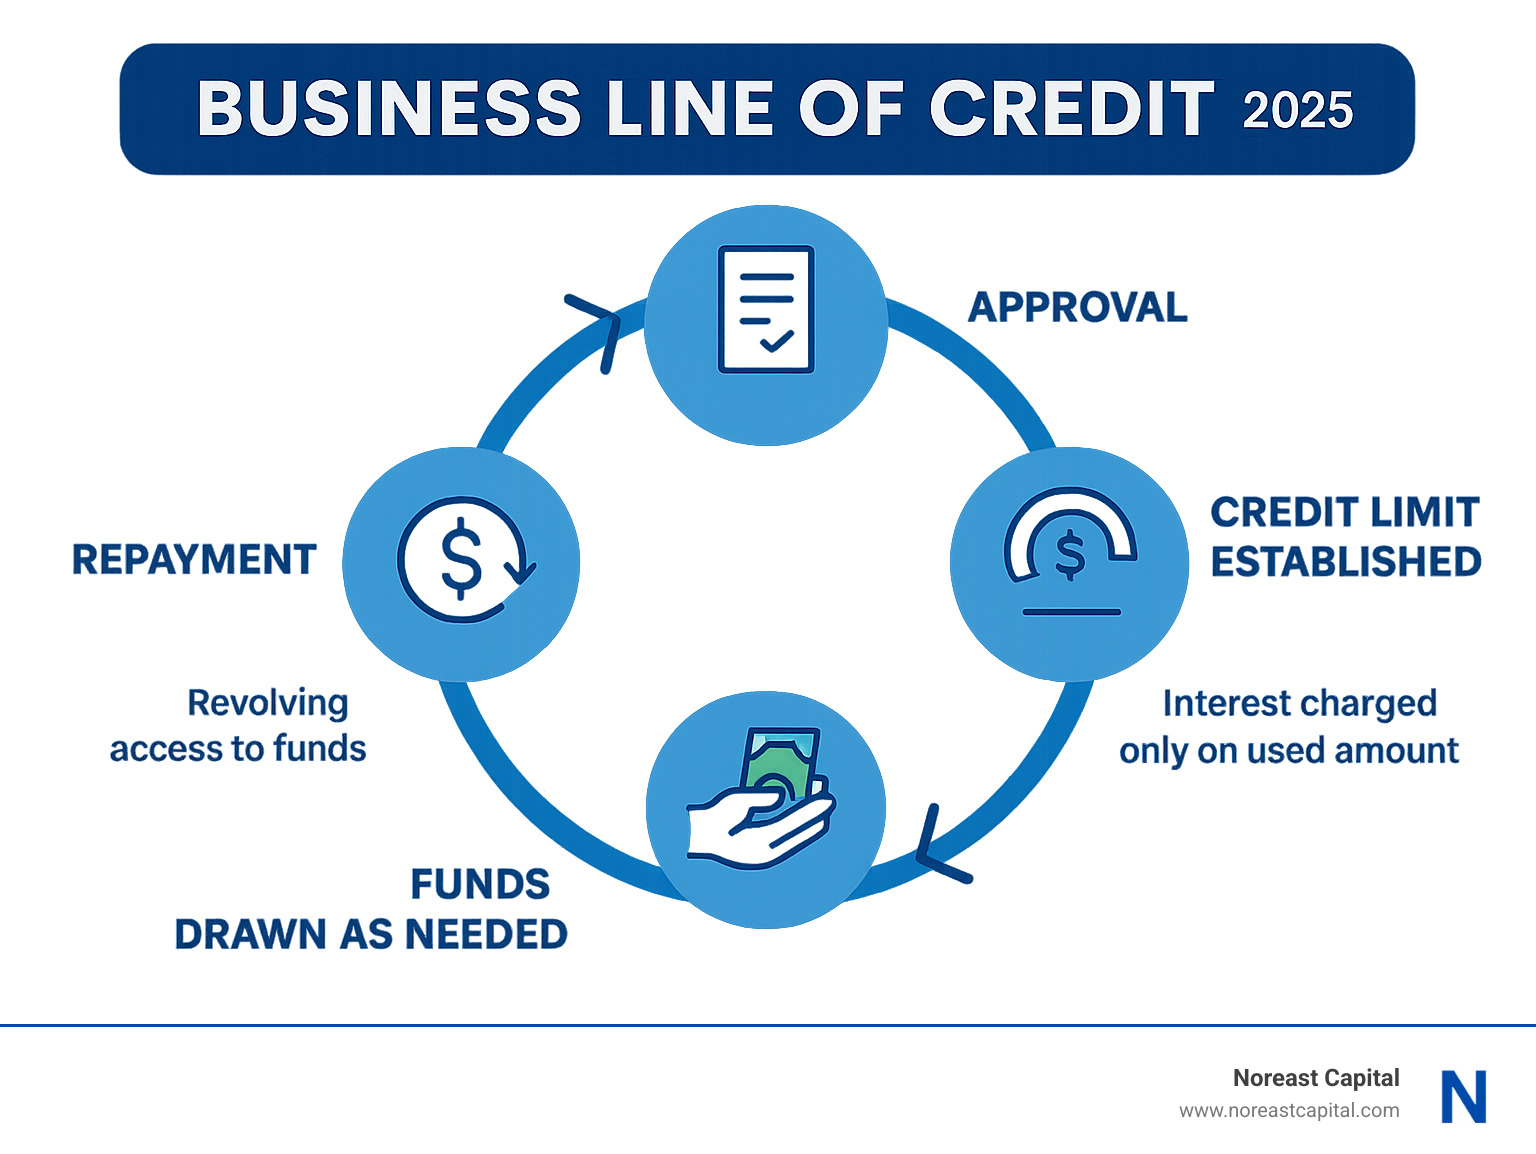
What Is a Business Line of Credit?
Business Line of Credit | Definition, Features, Types and Application
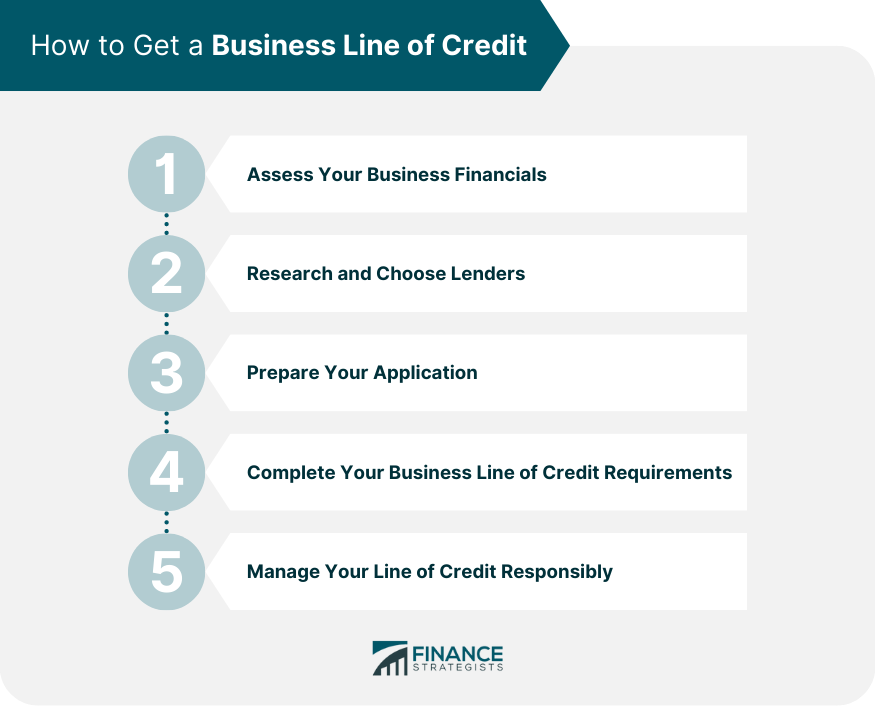
How to Get a Business Line of Credit (+ Common Mistakes)
Small Business Line Of Credit
Understanding Business Line of Credit