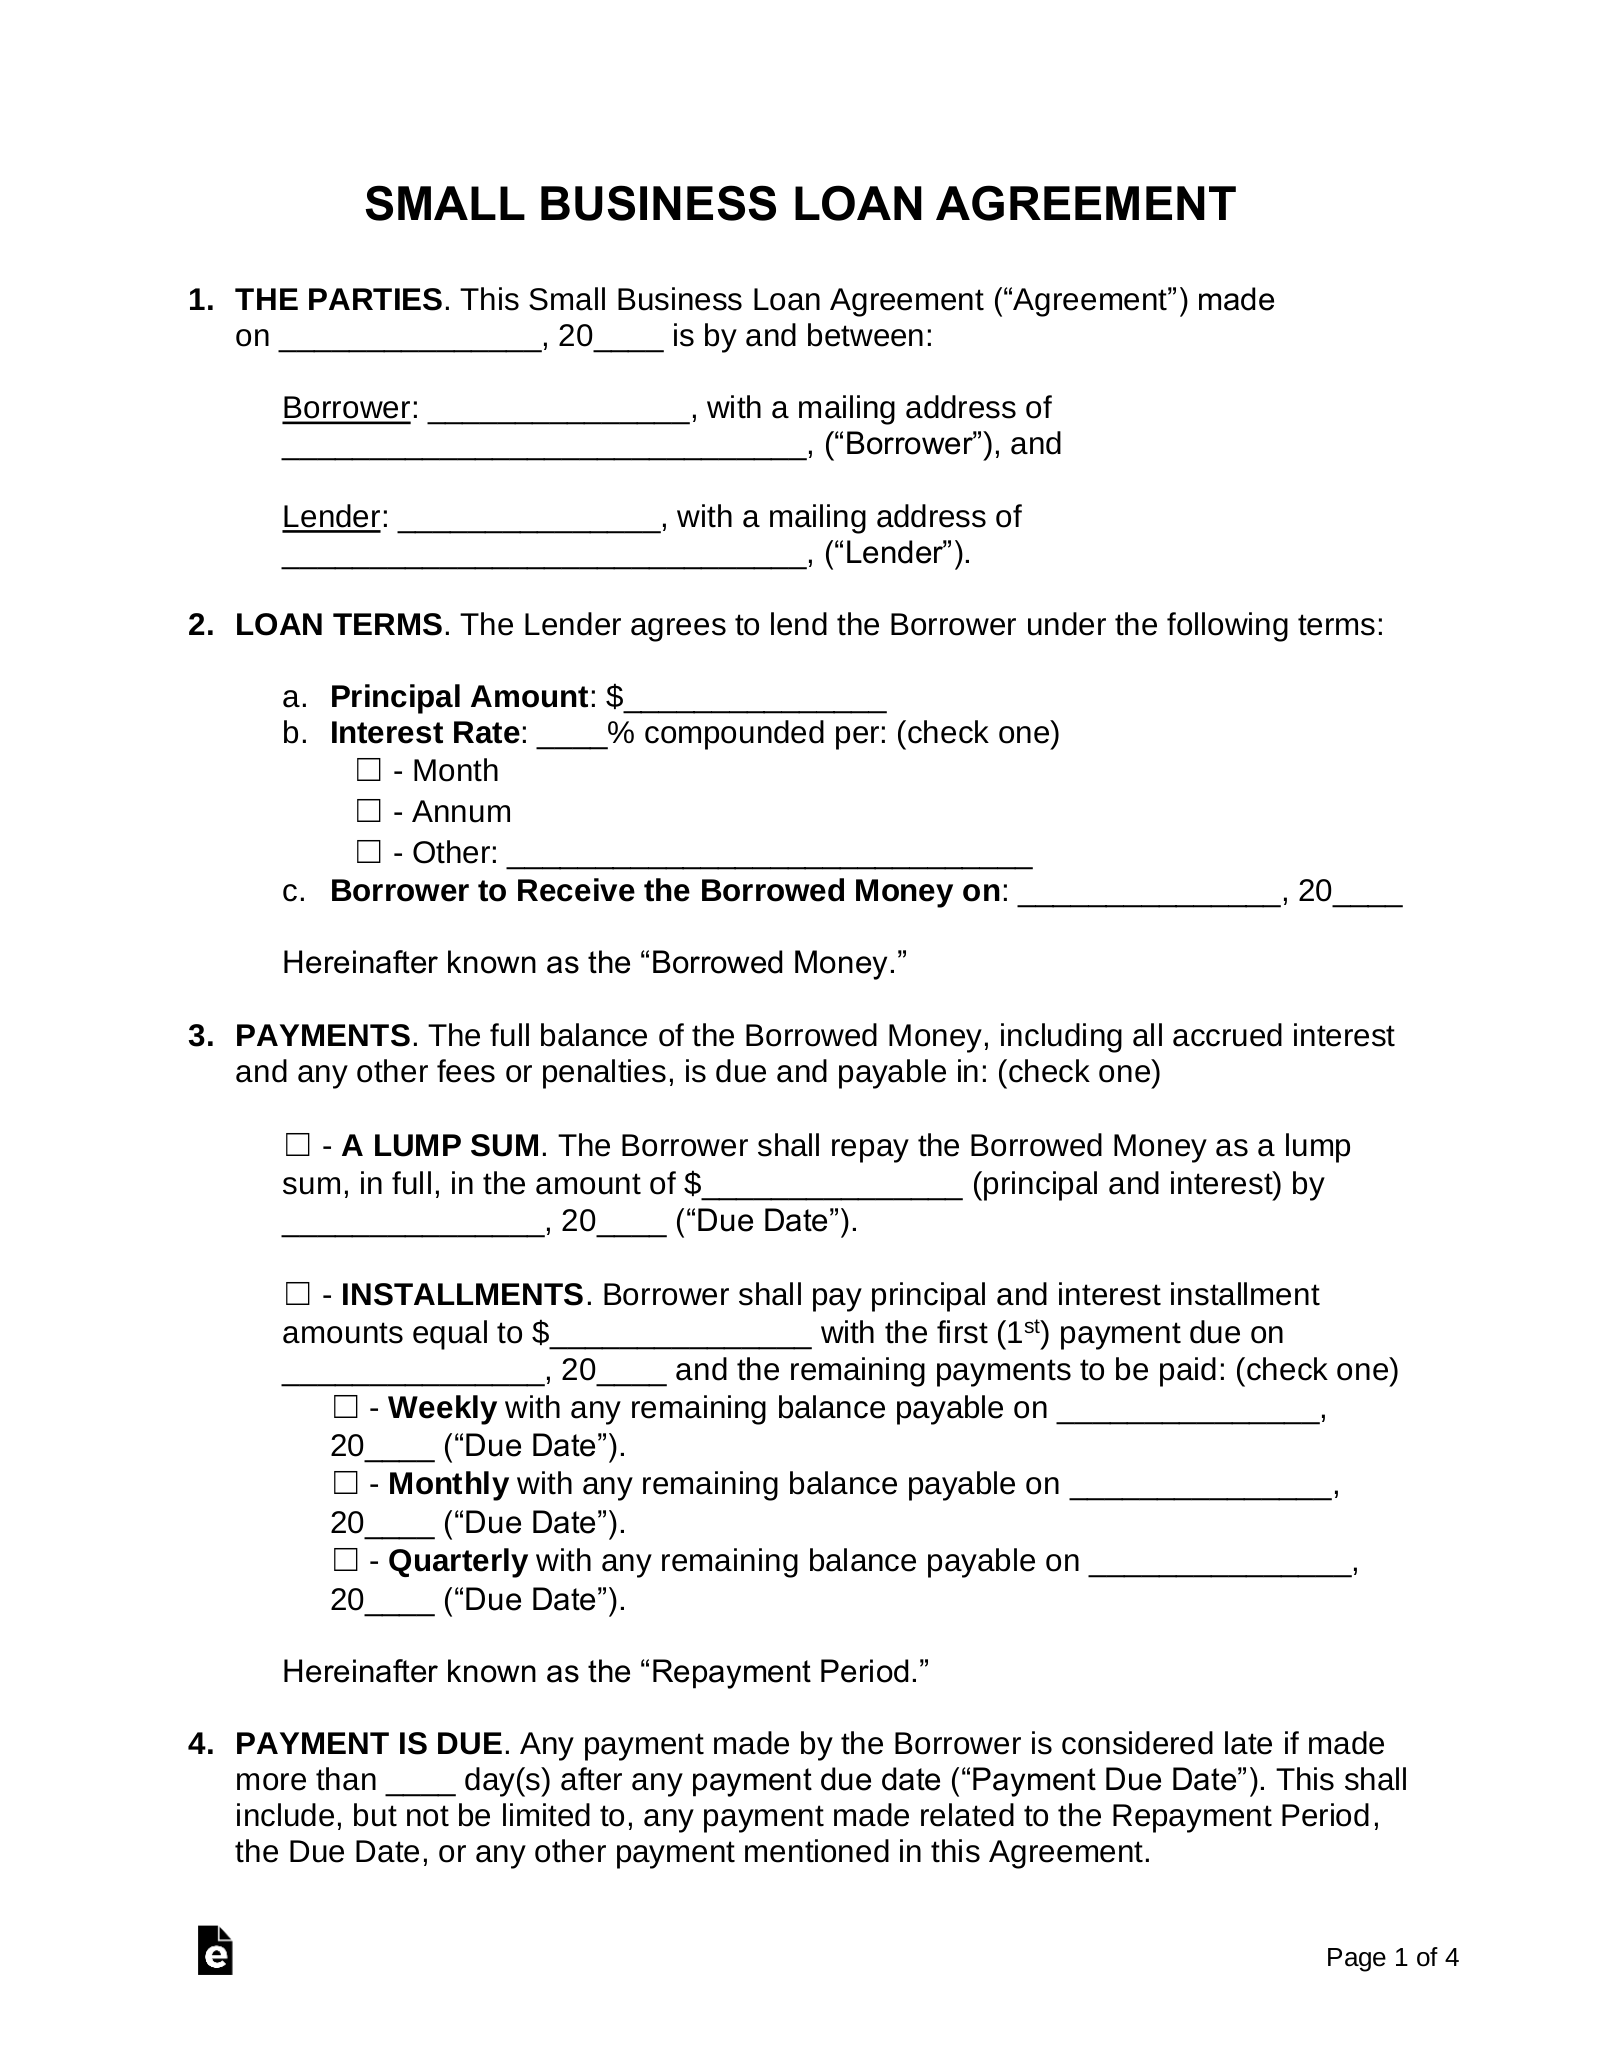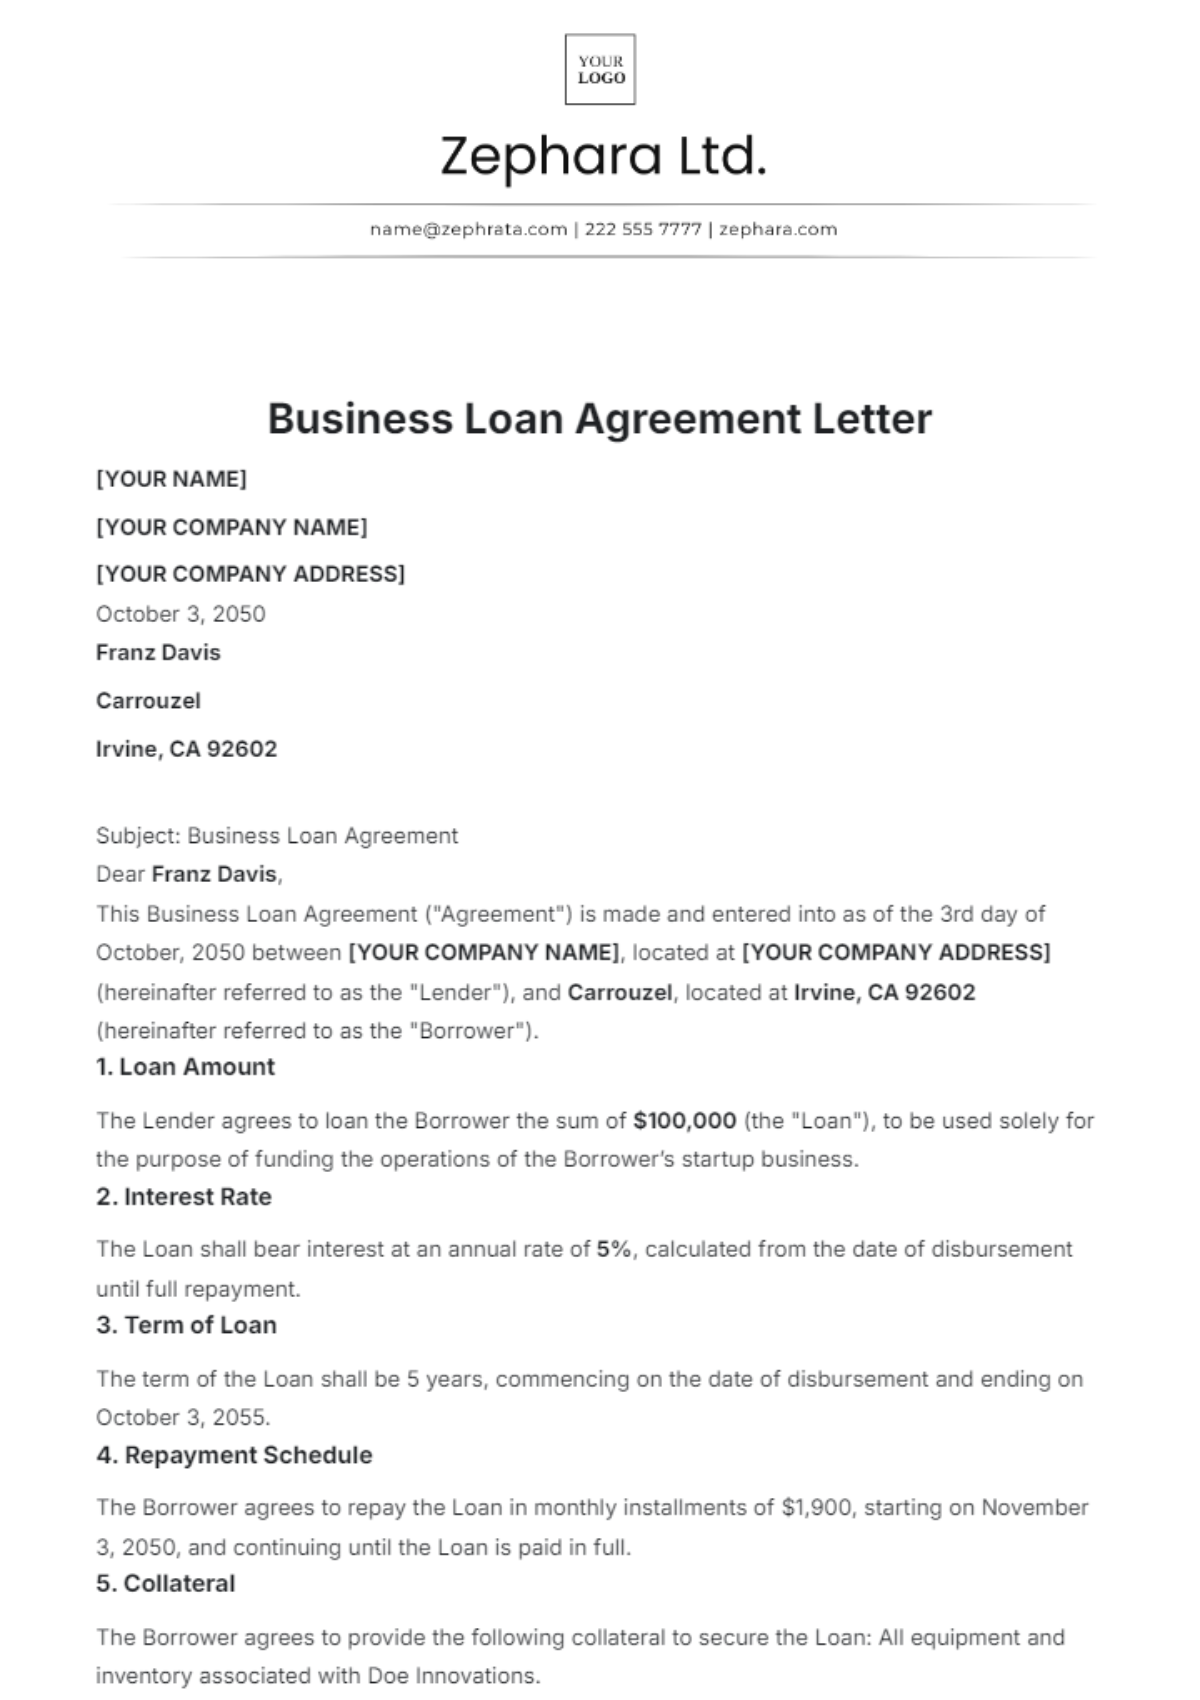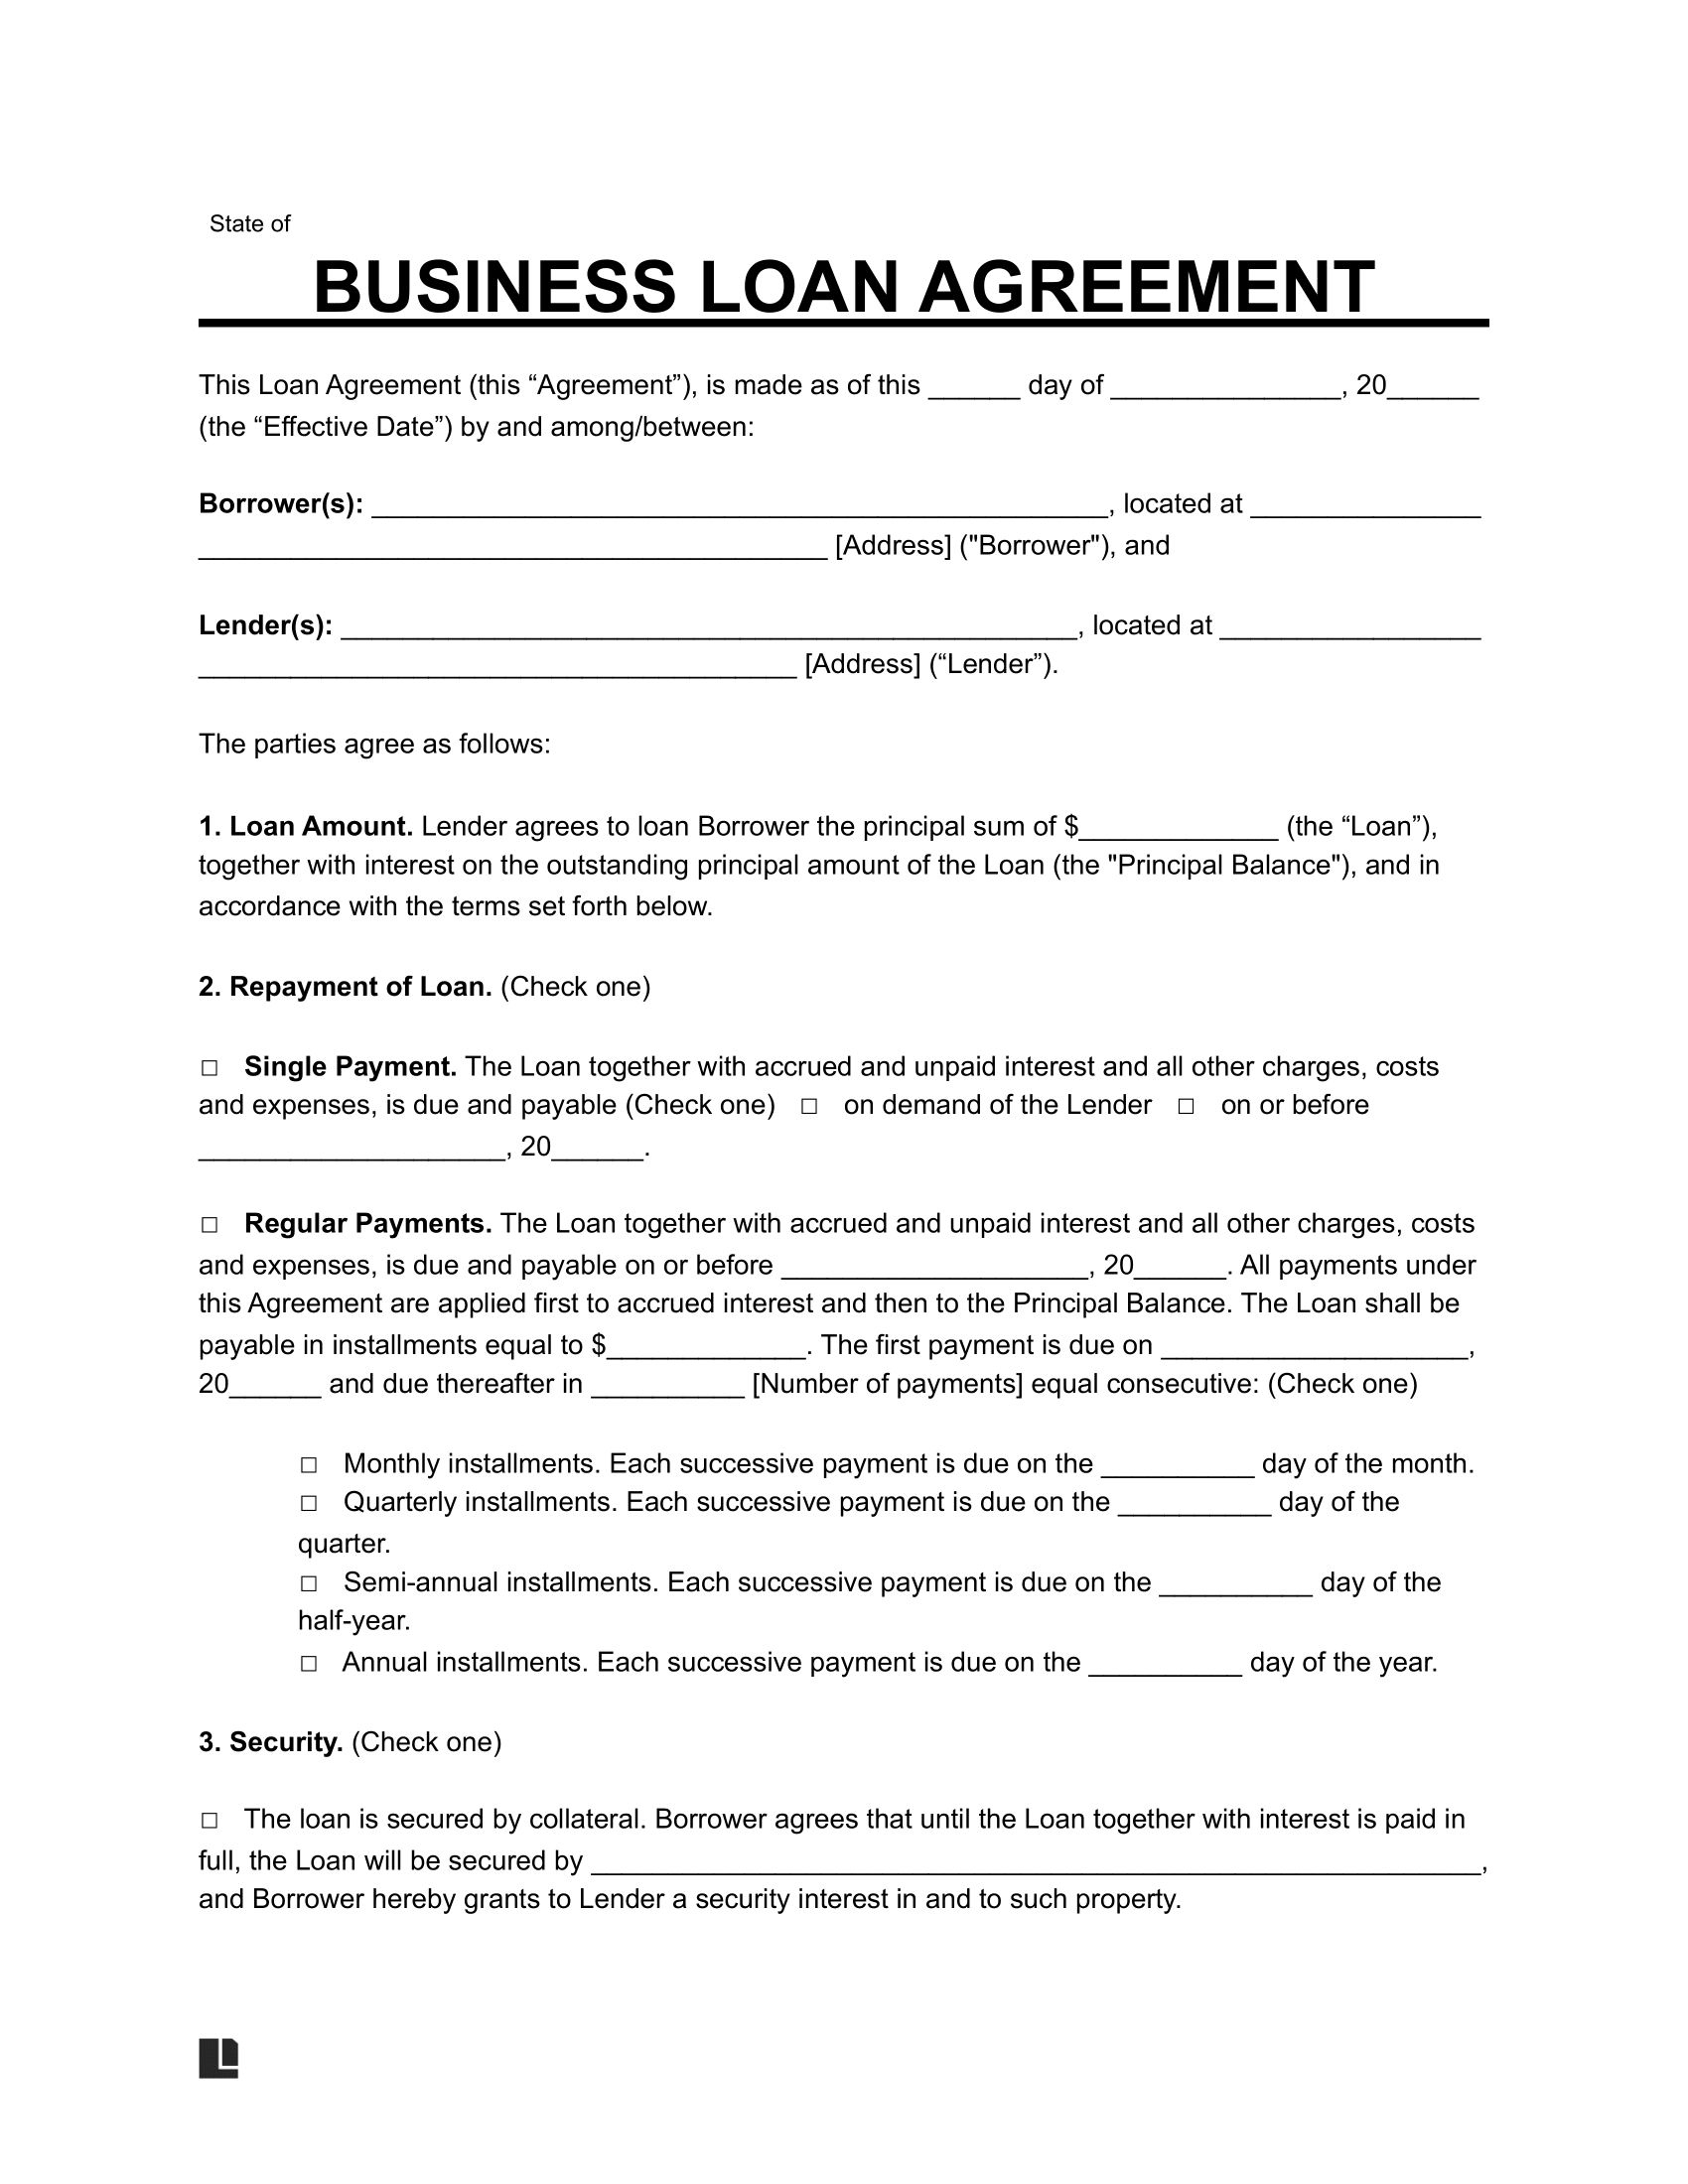
Getting a Business Loan Agreement Template right actually matters
Most people treat these documents like formality boxes to check before they get the money. I've watched small business owners sign agreements without reading past the first three pages, then get surprised when a prepayment penalty or an acceleration clause bites them six months later. That's on them, but it also means a lot of templates out there are written by people who've never had to enforce one. The core issue with most Business Loan Agreement Template documents you'll find online is that they're designed for one specific type of loan and presented as if it covers everything. An SBA-style term loan needs different provisions than a short-term working capital advance, which needs different provisions than an equipment financing arrangement. Stack the wrong clauses together and you end up with a contract that's internally contradictory or leaves gaping holes where disputes actually happen.Building a Business Loan Agreement Template That Doesn't Fall Apart
Start by identifying what kind of loan this actually is. Is it secured or unsecured? What's the amortization structure? Who are the parties and do any of them have co-signers or guarantors? These answers determine everything that follows. I had a client once who used a generic template for a $75,000 equipment loan and forgot to include a UCC-1 filing requirement. The lender considered the collateral clause unenforceable because the template didn't specify the exact equipment serial numbers or require a filed lien. We ended up drafting a side amendment that referenced the equipment schedule and had both parties execute it before disbursement. Took two days and cost him about eight hundred dollars in legal fees that could have been avoided with a properly scoped template from the start. A solid template needs these sections and they need to be in the right order:Parties and Recitals
The borrower and lender names, addresses, and entity types. If there's a guarantor, they go here too. The recitals explain why the loan exists in one or two sentences. Don't skip this because it matters for interpretation if a court ever has to figure out what the parties intended.
Loan Amount and Disbursement Terms
State the principal clearly. Specify how and when funds are disbursed. One lump sum? Milestone-based? This is where I've seen people get burned by vague language like "funds will be made available within reasonable time." Reasonable means nothing in a dispute. Put a specific number of business days.
Interest Rate and Calculation Method
Fixed or variable. If variable, tie it to a specific index with a defined margin and adjustment frequency. Most templates get this wrong by saying "prime rate" without specifying which prime rate or how often it changes. Use SOFR or a clearly identified published index. State whether interest is calculated on a 360-day or 365-day year. This detail matters more than people think for the total cost of the loan over its life.
Get the Full Details

Repayment Schedule
Payment amount, frequency, and due date. Include what happens with the final payment if it's a balloon. Prepayment terms deserve their own subsection. Some lenders charge a yield maintenance fee or a flat percentage if you pay early. Other templates silently allow prepayment without penalty when the lender actually intends to charge one. Read the prepayment section twice.
Events of Default
This is the section that separates a usable template from a decorative one. Missed payment, breach of covenant, insolvency filing, material adverse change, cross-default to another obligation. List them all. Be specific about cure periods. A thirty-day cure for a payment miss is standard. Sixty days might be appropriate for a covenant breach. Don't lump them together.
Remedies and Acceleration
What can the lender do when default occurs? Demand immediate payment of the entire balance? Seize collateral? Charge a default interest rate? Specify which remedies apply in which situations. Some templates give the lender every possible remedy for any single default, which courts sometimes find unconscionable depending on jurisdiction.
Covenants
Affirmative covenants are what the borrower promises to do. Financial reporting, maintaining insurance, staying in compliance with laws. Negative covenants are what the borrower promises not to do. Take on additional debt, sell assets, pay dividends above a certain threshold. Keep these reasonable. Overly restrictive covenants get negotiated down anyway and a template that's too aggressive signals that the drafter doesn't understand how commercial lending actually works.
Miscellaneous Provisions
Governing law, venue, severability, amendment process, notice requirements, waiver provisions. These seem boring until you need them. The notice clause determines how you formally communicate a default or a modification. Without it, you're relying on informal emails that may not hold up. Specify that notices must be in writing and delivered by certified mail or a tracked courier with proof of delivery.
I've seen a lot of free templates online that skip the amendment and waiver clauses entirely. That's a problem because once the loan is active, circumstances change. The borrower might need a payment deferral during a rough quarter. Without a clear amendment process, you're stuck figuring out whether a handwritten email from the lender saying "don't worry about that payment" actually counts as a binding waiver. Include a clause that says no waiver is effective unless it's in writing signed by both parties, and that a single waiver doesn't imply future waivers. This protects both sides. One counter-intuitive thing about loan agreements: the default section isn't just for protecting the lender. A well-drafted default clause with clear cure periods and proportionate remedies actually makes the loan easier to get because it reduces perceived risk. Lenders prefer certainty. A borrower who can show a clean, balanced agreement gets better terms than someone dragging out a template full of one-sided panic clauses. Another thing people miss is the relationship between the loan agreement and any separate security documents. If this loan is secured by collateral, the agreement should reference the security agreement or promissory note by name and date. Cross-reference everything. I once reviewed a template set where the loan agreement mentioned collateral in three different places with three different descriptions, and none of them matched the actual security filing. That kind of inconsistency is exactly how you lose priority on a lien. The main limitation of any template is that it can't account for your specific jurisdiction's usury laws, consumer protection statutes, or commercial code provisions. A template drafted under New York law might violate Massachusetts lending regulations if you're operating there. Check your state's maximum interest rate and any disclosure requirements before you use a template as-is. Some states require specific language in the preamble or separate acknowledgments that a generic template won't include. For a basic unsecured business loan under fifty thousand dollars between private parties, a well-structured template with the sections above should cover the essentials. For anything larger, any secured transaction, or any situation involving a government-backed loan, you're better off having a lawyer adapt a template rather than using it raw. The template gives you a framework. The lawyer fills in the gaps that matter for your particular deal.