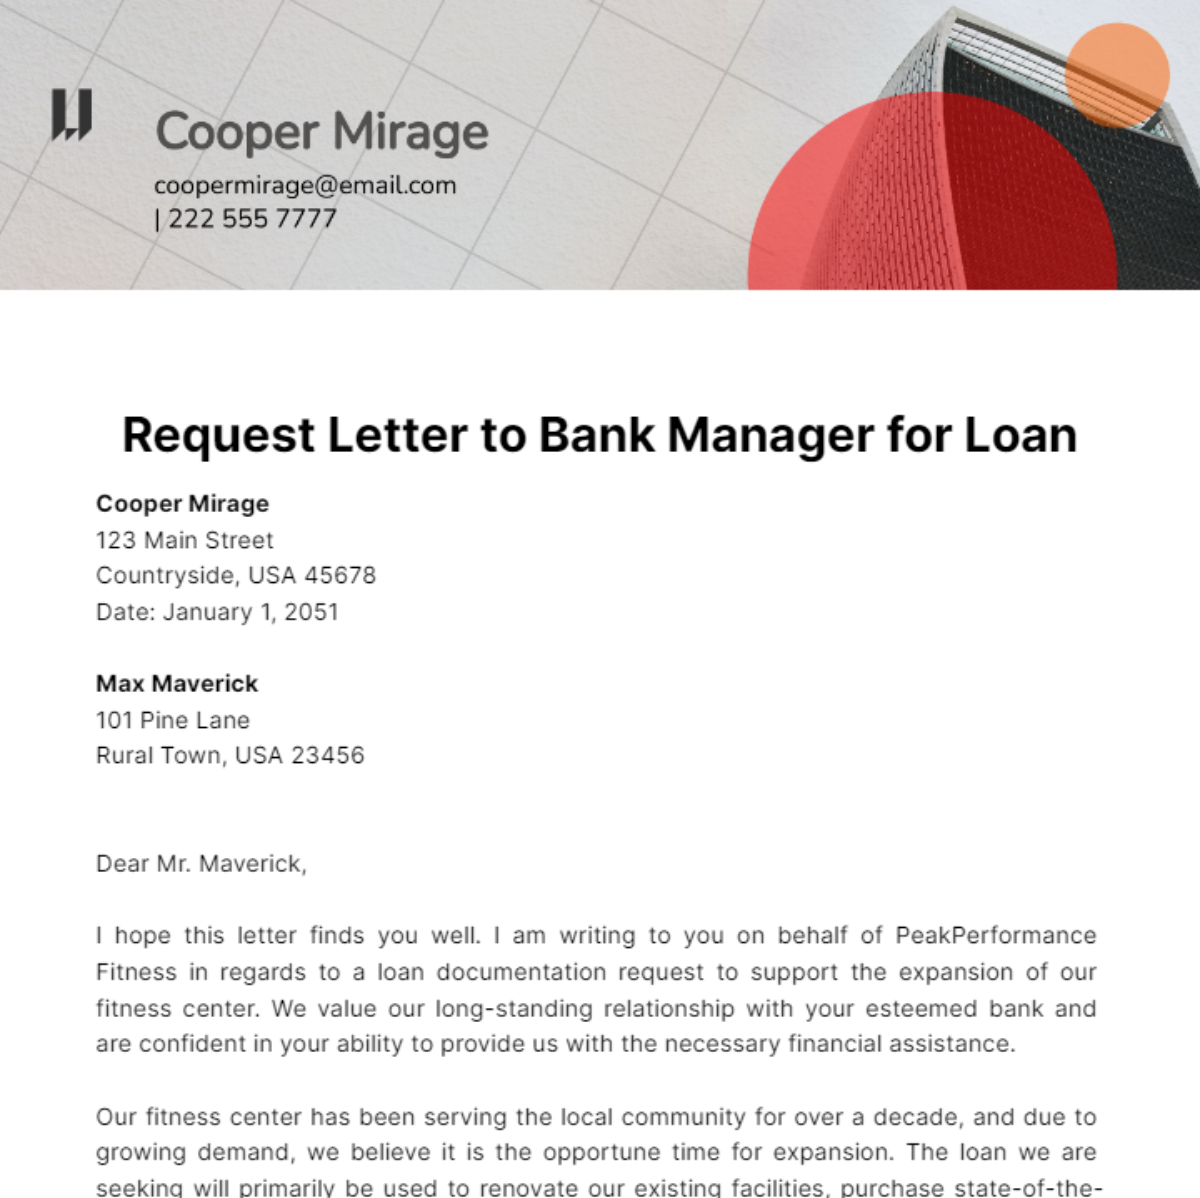
How to actually write a business loan request letter that gets read
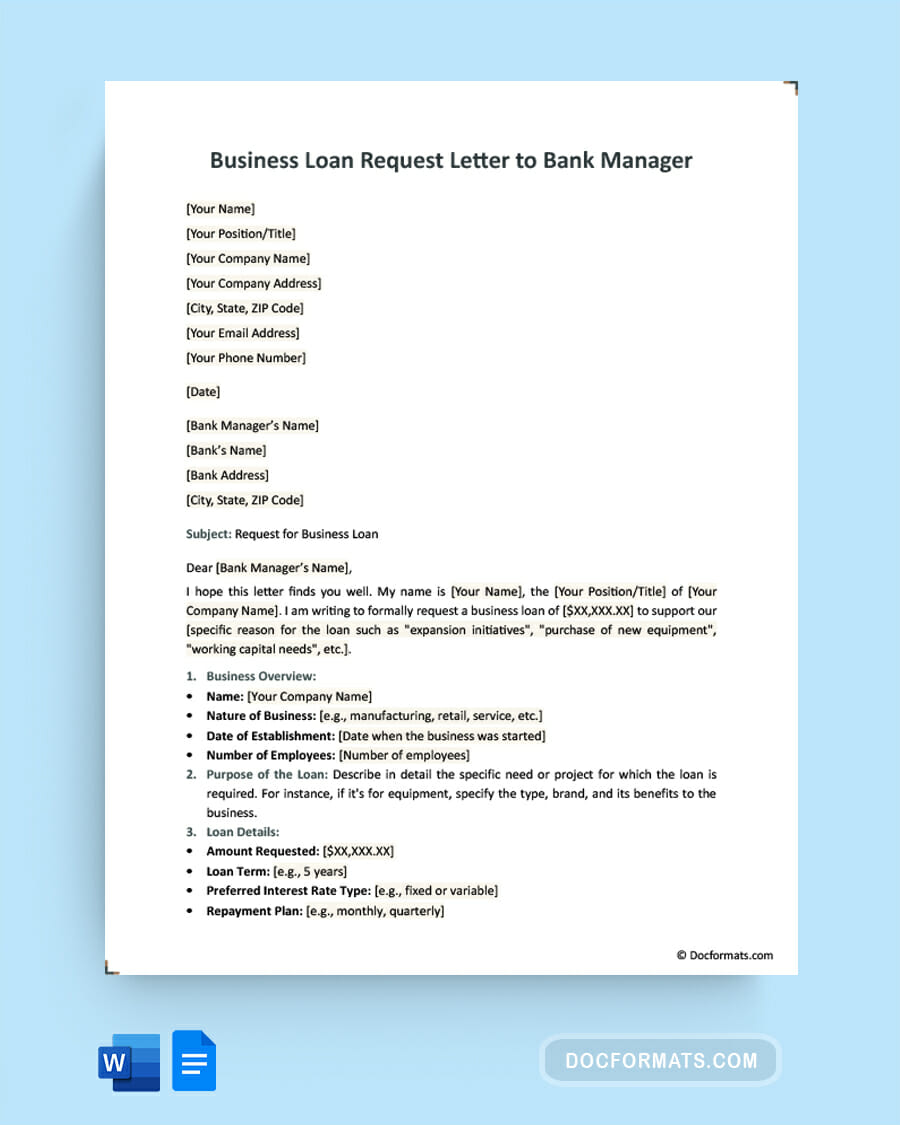
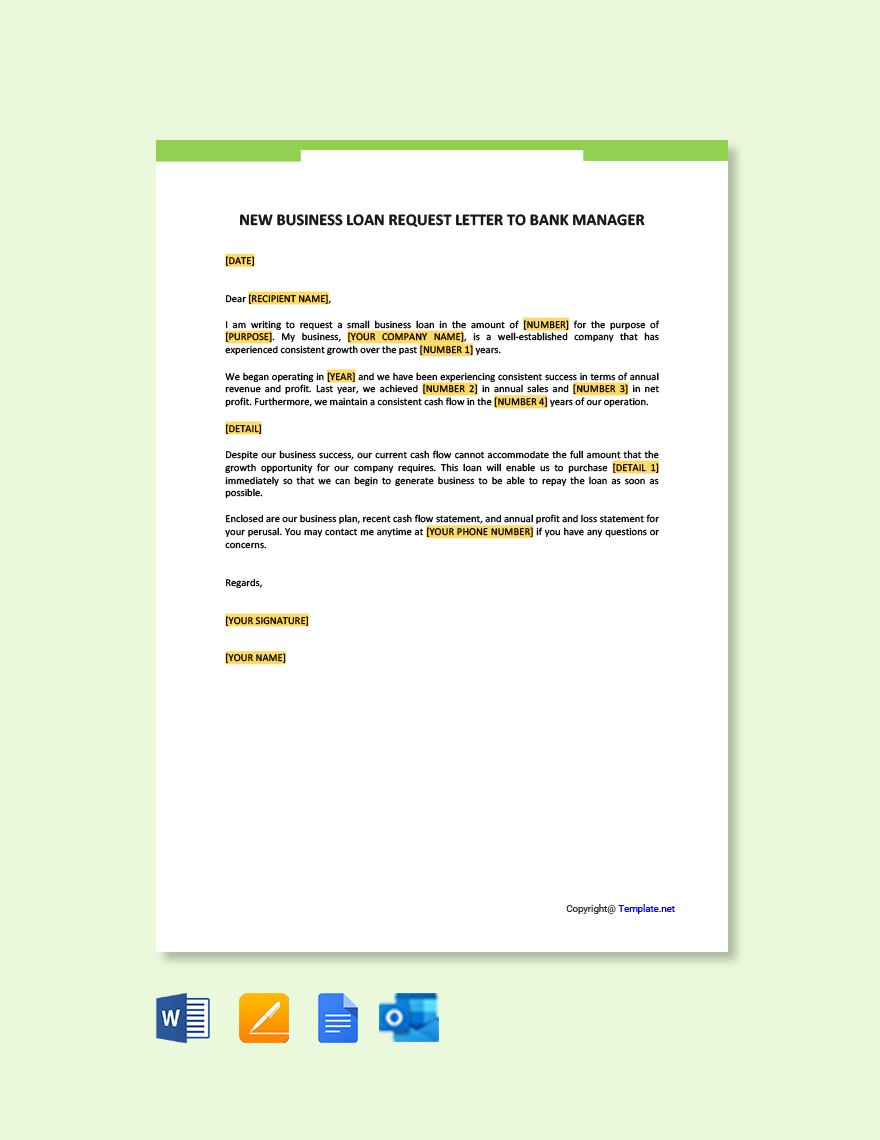
Most bank managers spend about three minutes scanning a loan request before it gets forwarded to underwriting or tossed into the "needs more info" pile. A generic template you download from a free site will almost certainly land in that second category. The format matters less than the specificity of what you include. Here is how I approached this when I was running a small logistics company and needed working capital for a fleet expansion.The Bank of America business loan officer I dealt with rejected my first submission because I had included a twenty-page business plan but only one page explaining the loan itself. She literally told me later that she could not find the ask. So I built a Business Loan Request Letter To Bank Manager Word Format that was strictly focused on the terms, the purpose, and the repayment mechanism. It ended up taking four pages max, and it got approved in eighteen days instead of the standard sixty to ninety for small business loans. The structure you need is straightforward once you understand what the banker is actually looking for. Bankers are risk assessors, not investors. They want to know three things: why you need the money, how you will pay it back, and what happens if you cannot. Everything else is decoration. Here is the section breakdown I use now:
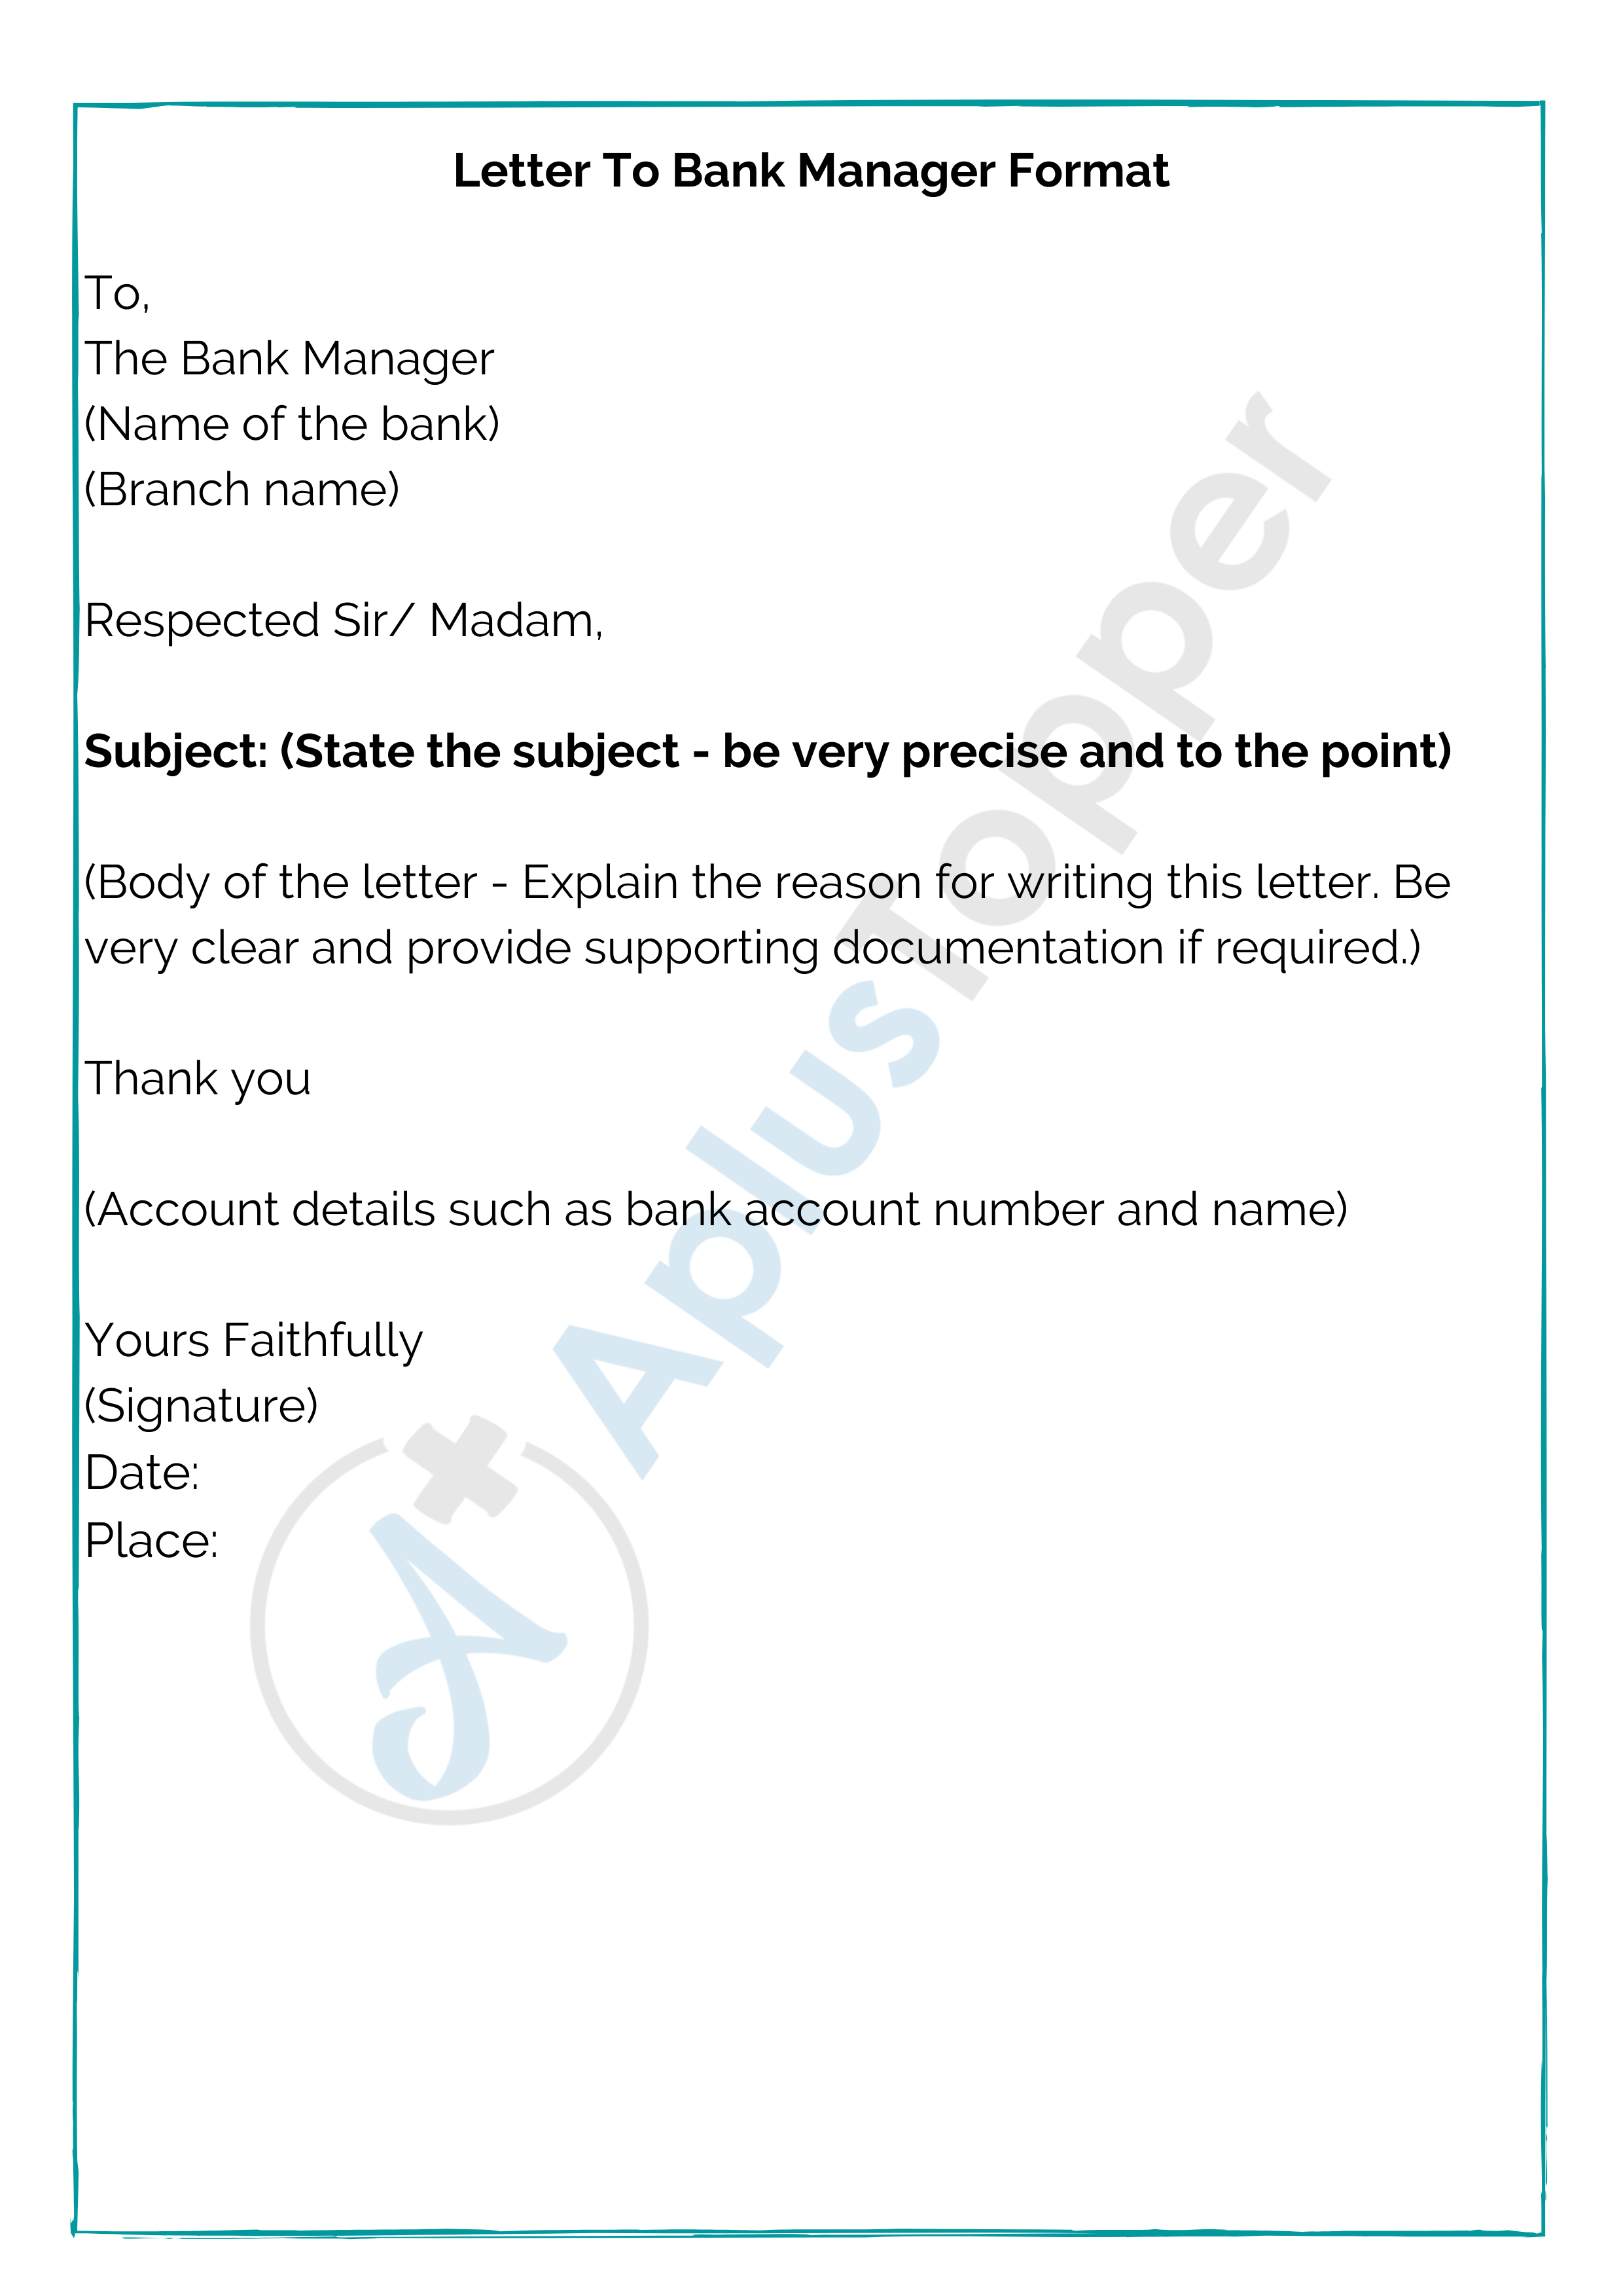
Header and salutation: Your business letterhead at the top, date, then the bank manager's name and branch address. Address it to a specific person. "To Whom It May Concern" guarantees your letter goes to the bottom of the stack. Call the branch first and get the actual name. It takes thirty seconds and signals that you take this seriously. Purpose statement (one paragraph): Open with exactly what you are requesting and why. Not "we are seeking funding for growth opportunities" — that is meaningless. Write "We are requesting a $125,000 term loan to finance the purchase of three delivery vans, which will increase our weekly capacity by 40% and generate an estimated additional $38,000 in monthly revenue." Specific numbers matter more than persuasive language. Repayment plan (two paragraphs): This is the section most people butcher. State your proposed monthly payment, the loan term you are requesting, and what cash flow covers it. Include your current debt service coverage ratio if you have calculated it. For reference, a DSCR above 1.25 is generally the minimum threshold most community banks require for small business term loans. If your DSCR is below that, acknowledge it and explain the remediation plan.
Collateral and guarantees: List what you are offering as security. For a vehicle purchase loan, the vehicles themselves serve as collateral. For larger working capital loans, you may need a personal guarantee or a lien on business assets. Be explicit about what is available. Do not make the banker ask for this information. Supporting documents list: At the end of the letter, include a bulleted list of enclosed documents. Typical requirements include recent business tax returns (usually two years), profit and loss statements for the past twelve months, a current balance sheet, and a cash flow projection covering the loan term. Some banks also want a personal financial statement from the owner. Closing: Keep it professional and include your contact information. Add a line like "I am available to discuss this application at your convenience and can provide any additional documentation required." Nothing more dramatic than that.
Get the Full Details
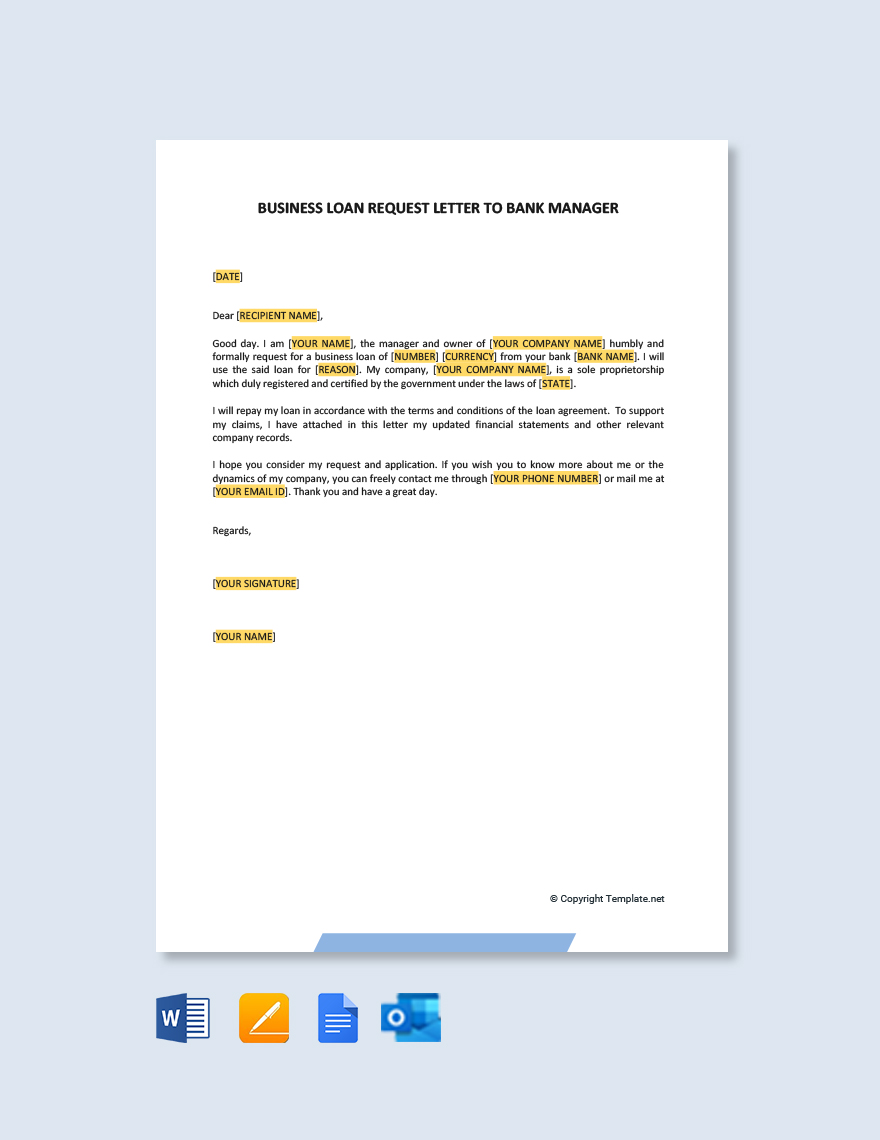
What the Word format should actually look like
Use a standard 12-point Times New Roman or Arial font. One-inch margins on all sides. Left-align everything — do not justify the text, because justified text creates uneven spacing that looks sloppy when printed and harder to read on screen. The banker is scanning, not reading for pleasure. Keep the total length between three and five pages. Any longer and the reader's attention degrades significantly. My experience is that the average bank manager reviews maybe fifteen to twenty loan requests per week during peak seasons. They do not have time to parse a novella. Save the file as a PDF before submitting it. Word documents can render differently on different systems, which occasionally corrupts formatting and looks unprofessional. The phrase "Business Loan Request Letter To Bank Manager Word Format" usually refers to the drafting stage, but the submission should always be a PDF unless the bank's online portal specifically requires a .docx upload.
The problem I ran into and the workaround
When I submitted my first version of this letter, the bank's automated intake system rejected it because the file was named "loan_request_final_v3.docx." That sounds ridiculous but it happened. Their document management system uses the filename to categorize incoming applications, and a mangled filename delayed my application by four business days while it got stuck in a manual review queue. The workaround was simple but something no template teaches you. Name your file using this convention: LastName_BusinessName_LoanRequest_YYYYMMDD.pdf. For my case it became "Martinez_Transtar Logistics_LoanRequest_20231015.pdf." After that, every submission went straight into the processing pipeline without any administrative friction. Also, never use special characters in filenames. Underscores and hyphens are fine. Spaces are risky because some banking portals encode them as %20 and the system misreads the extension.
Counter-intuitive things nobody tells you
First, the letter itself is rarely the deciding factor in loan approval. What actually decides it is your credit profile, your financial statements, and your relationship with the bank. The letter is a framing device. A well-written letter does not get you approved, but a poorly written one can actively hurt your chances by making the underwriter question your competence or attention to detail. Think of it as damage control rather than persuasion. Second, mentioning your existing banking relationship early in the letter has a measurable effect. If you hold a business checking account, a line of credit, or any other product with that bank, state it in the second paragraph. Banks prefer lending to existing customers because they already have visibility into your cash flow. A 2022 Small Business Lending Report from the Federal Reserve found that existing relationship borrowers received approvals roughly 22% faster than cold applications, even when the risk profile was identical. Lead with that fact.
![Loan Request Letter To Bank Manager {Customizable version] | Business letter format, Lettering ...](https://i.pinimg.com/originals/1b/89/90/1b899074ef2740725fe6009c9976cb3a.jpg)
When this approach does not work
A well-formatted letter will not save a loan application if your personal credit score is below 640, if your business has fewer than two years of operating history, or if your debt-to-income ratio is already above 43%. These are hard thresholds at most community and regional banks. The letter format cannot overcome a fundamental risk profile that falls outside the bank's lending criteria. In those situations, the better path is either a microlender or a CDFI (Community Development Financial Institution). Organizations like OpportunityFund or Accion specialize in loans for businesses that do not meet traditional bank criteria. The application process is different — you will submit a full proposal rather than a single letter — but the approval rates are meaningfully higher for marginal credit profiles. I switched to a CDFI for my second expansion loan after my credit had temporarily dipped due to an unexpected equipment repair. The bank would have rejected it outright, but the CDFI approved a $75,000 SBA microloan within eleven days. The letter format I described above does not apply there.
Quick reference checklist
Before you send anything, verify these items: - Bank manager's full name and title confirmed via phone or the bank's official website - Specific loan amount and purpose stated in the opening paragraph
- Repayment terms clearly defined with monthly payment amount and proposed duration - Collateral and guarantees explicitly listed - All supporting financial documents attached or referenced
- File named using the standard naming convention - File saved as PDF - Letter reviewed by someone who has not seen your business before, to catch ambiguity
The whole drafting process typically takes about forty-five minutes to an hour if you have your financial documents organized. If you are pulling tax returns and P&L statements from different folders while typing, expect two hours. That is why I keep a dedicated folder for loan applications and update it quarterly. Going back to old financials after six months of being asked for them is not worth the headache.