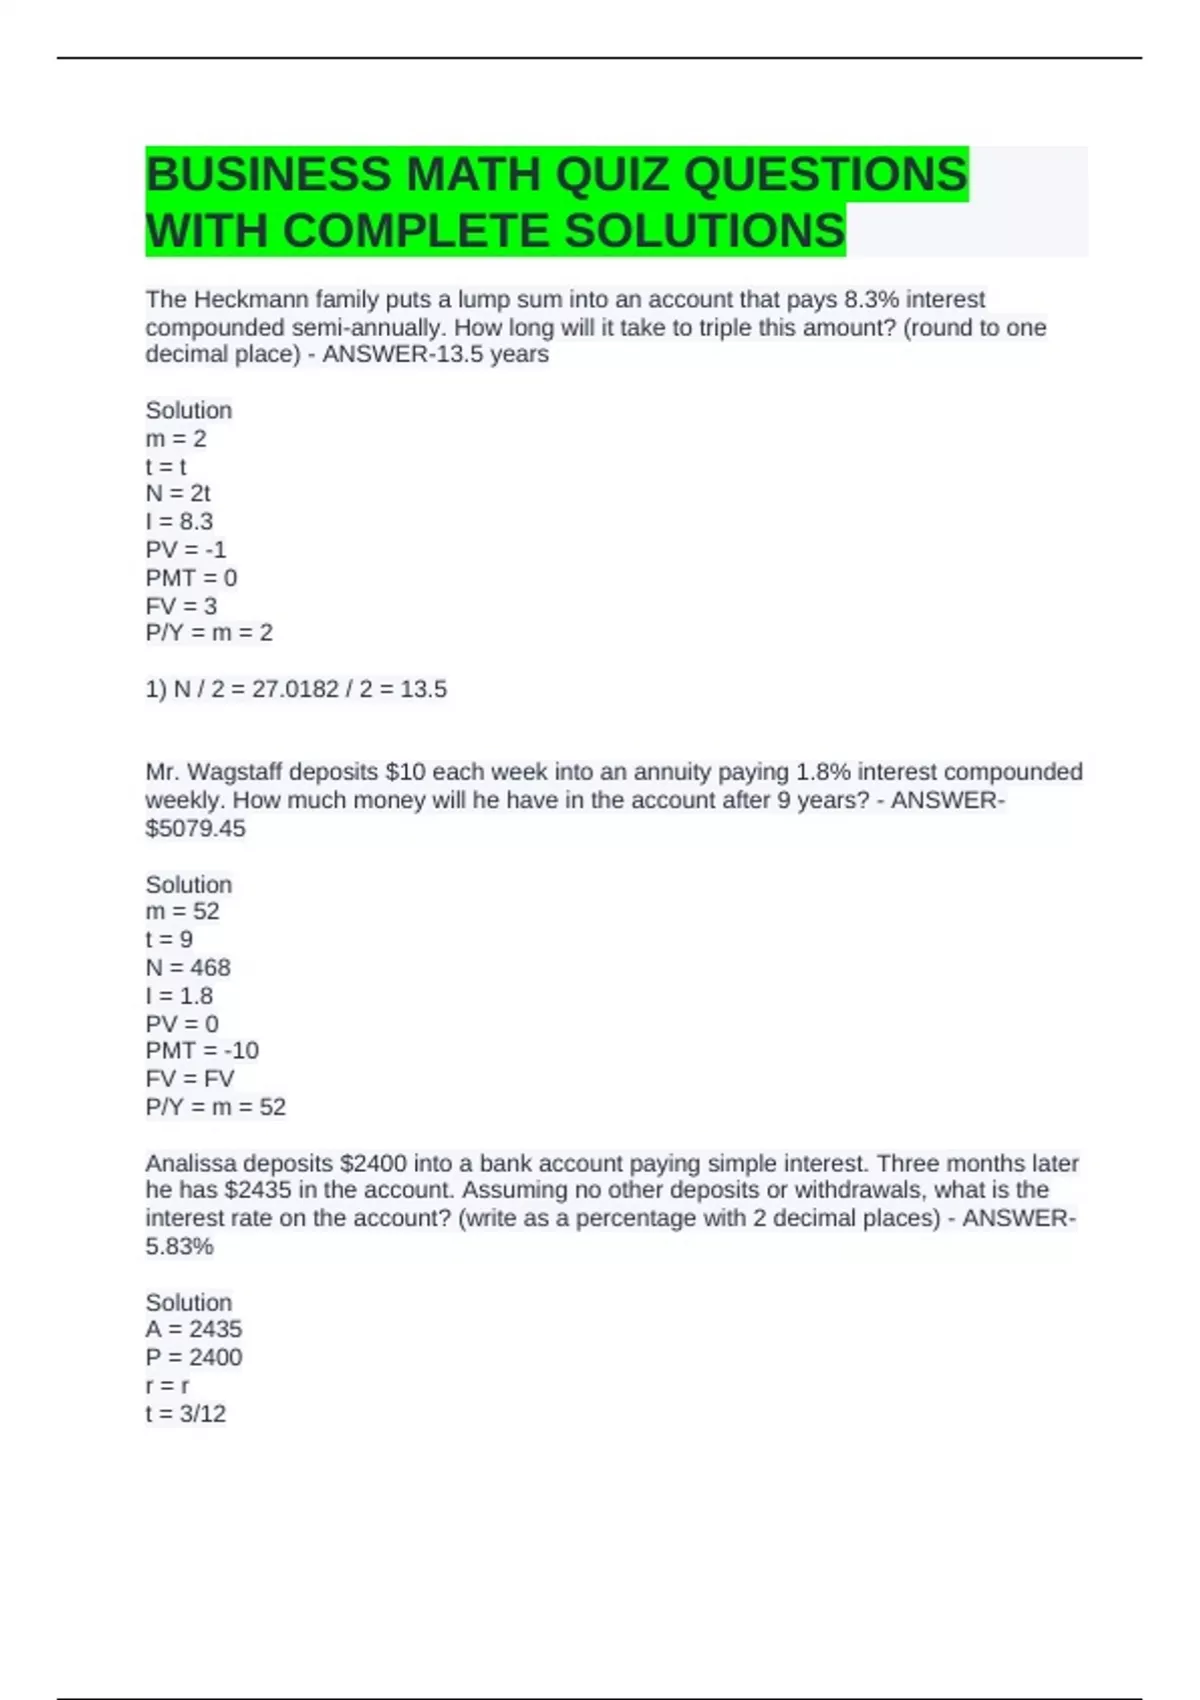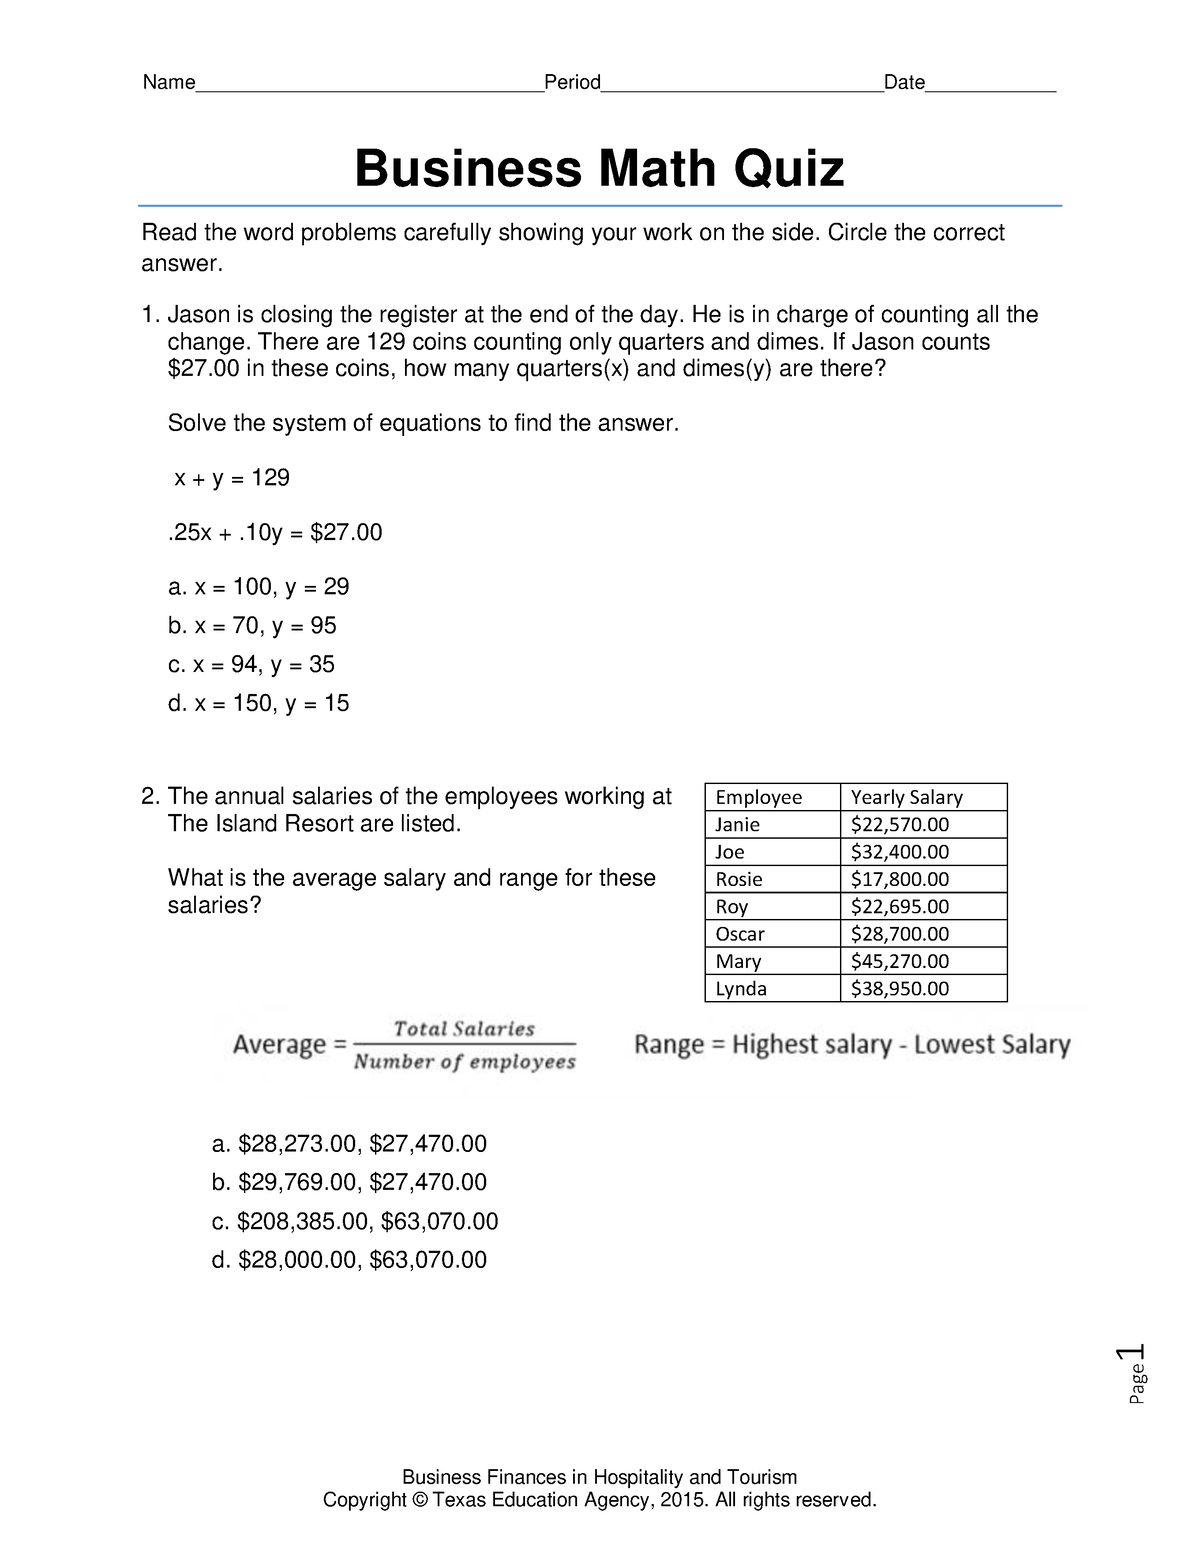
Working Through Business Math
Business math shows up in spreadsheets more often than people realize. Most of what you need to solve these problems isn't complicated, but it's easy to waste hours setting things up wrong the first time. I've been doing this for years across a few different industries, and I still see the same mistakes recycled. Let me walk through how I actually approach these problems in practice. The theory is fine, but the real value is in understanding where things break down.
Common Business Math Problems And Solutions
The most frequent issue I encounter involves cash flow projections with uneven payment schedules. Someone sends you a schedule where payments vary month to month, and you're supposed to calculate present value or future value. Standard financial calculators struggle here because they assume uniform periods. My workaround is straightforward once you've done it a few times. You break the cash flow into individual periods, discount each one separately, then sum them. In Excel, you can use NPV for the repeating portion and add the outlier periods manually. It takes about 5 minutes per scenario instead of the hour someone might spend wrestling with built-in functions that weren't designed for this. I remember working on a client project involving a lease agreement with variable escalations. The payments increased every 18 months rather than annually. The finance team tried to fit it into a standard annuity formula and ended up with figures off by nearly 8%. We recalculated using individual period discounting and found the discrepancy immediately.
Pricing and Margin Calculations
Gross margin calculations sound simple. Cost divided into selling price. But markups versus margins get confused constantly in business settings. A 50% markup does not equal a 50% margin. It equals a 33.3% margin. People build entire pricing strategies around the wrong number. The formula is clean enough. Markup percentage equals selling price minus cost, divided by cost. Margin percentage equals selling price minus cost, divided by selling price. Different denominators in the denominator position. One wrong decimal shift and your pricing model is broken. What nobody tells beginners is that compound interest and amortization formulas assume end-of-period payments. If your payments start immediately at the beginning of the period, every result shifts. I've seen loan calculations go wrong by several thousand dollars because of this single assumption. Adjust by multiplying the result by (1 plus the rate per period).
Get the Full Details
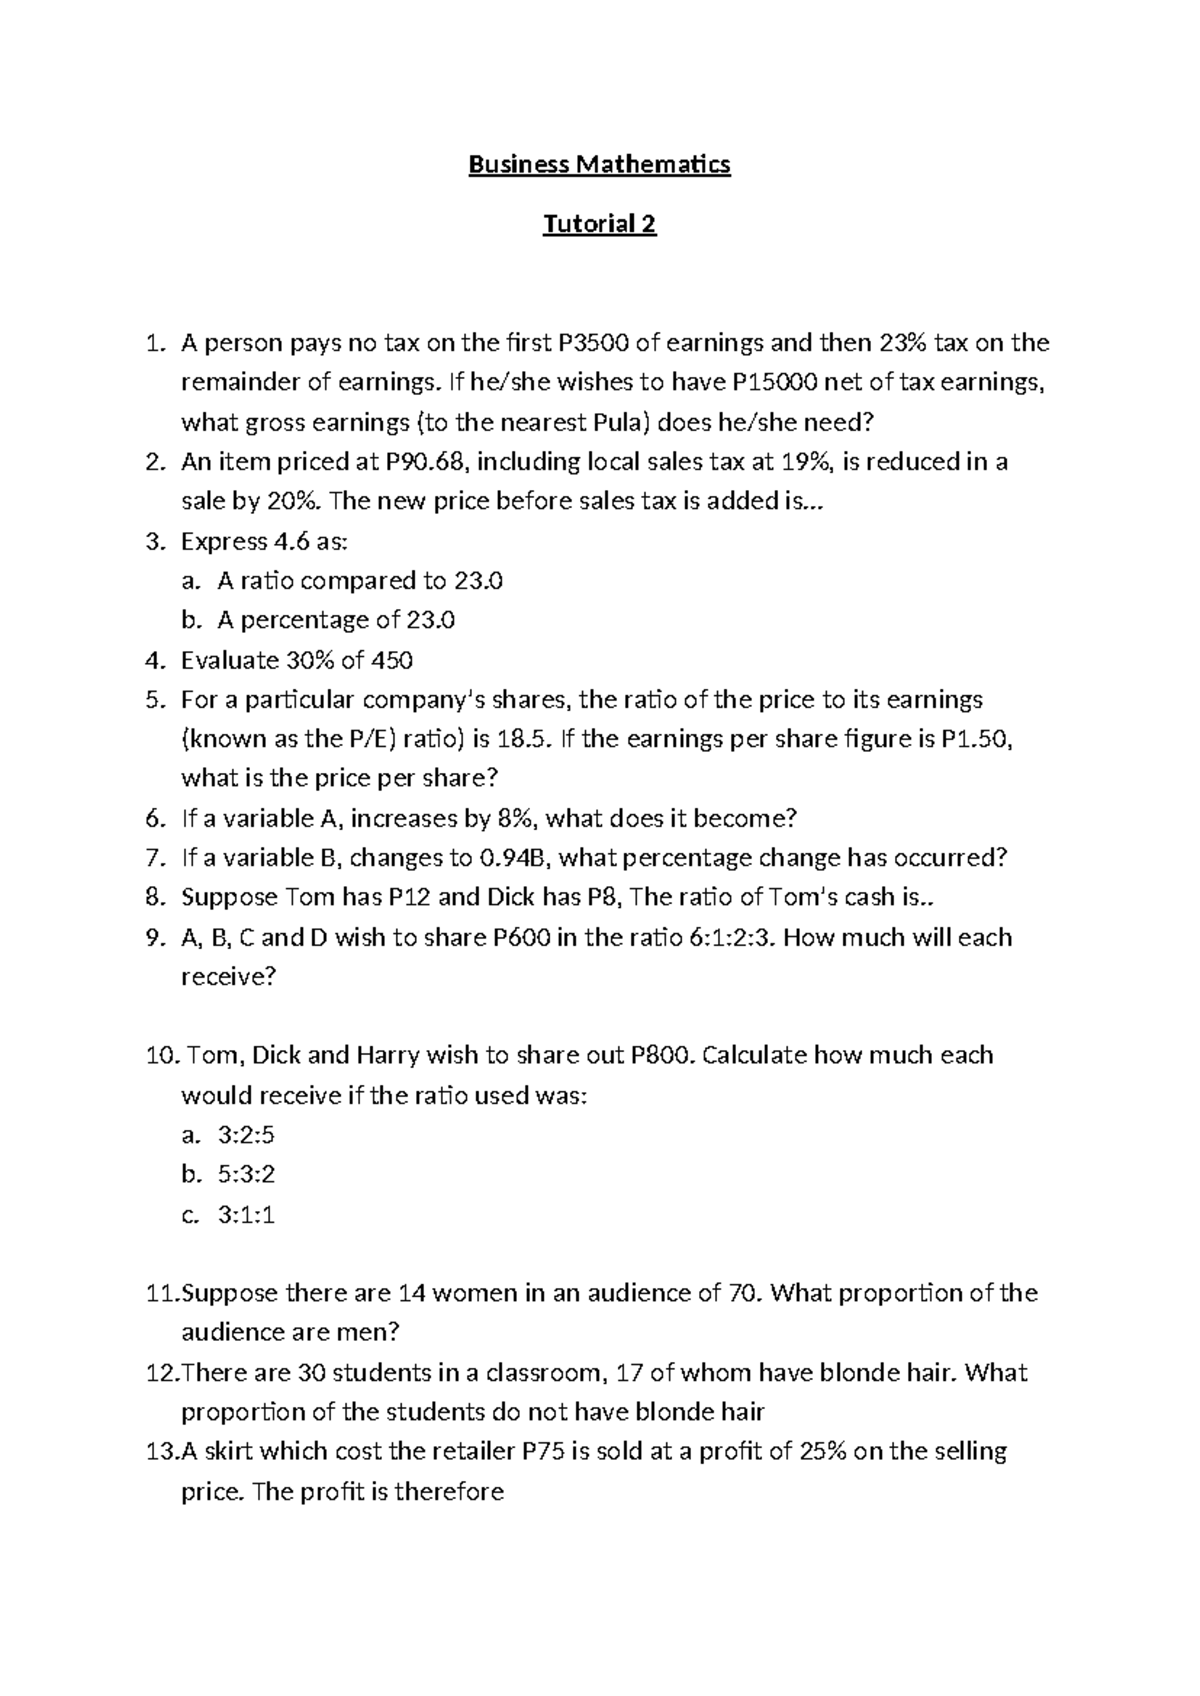
Tax and Depreciation Methods
Depreciation is where business math gets most messy in real-world applications. Straight-line is predictable. Double-declining balance creates bigger expenses upfront and smaller ones later. Sum-of-years-digits sits somewhere in between. Each method produces different tax outcomes over the asset's life. The practical issue is switching methods mid-life. Tax rules generally prohibit this without IRS approval in the United States, but people attempt it anyway when cash flow gets tight. It doesn't work. You commit to the method when you place the asset in service. Another overlooked detail is the half-year convention. Most tangible property depreciated under MACRS assumes you placed it in service at the midpoint of the year regardless of actual purchase date. This adds a half year to the depreciation schedule automatically. Forgetting this can throw off your Year 1 expense by a significant amount on high-value assets.
Break-Even and Contribution Analysis
Break-even analysis is useful but limited. It assumes fixed costs stay fixed and variable costs stay proportional. In reality, both assumptions break down at certain volume thresholds. Fixed costs jump when you need additional space or staff. Variable costs may decrease due to bulk purchasing discounts. The contribution margin approach handles some of this by separating costs properly. Revenue minus variable costs gives you contribution margin. Divide total fixed costs by contribution margin per unit to get the break-even point. This is cleaner than total cost approaches because it shows exactly how much each additional unit contributes toward covering fixed expenses. I worked with a manufacturer once who calculated their break-even at 12,000 units per month. They didn't account for the fact that raw material costs dropped 6% after 10,000 units due to volume pricing. Their actual break-even was closer to 10,500 units. The difference mattered enormously when they were operating near capacity.
Time Value of Money Decisions
PV and FV calculations underpin most capital budgeting decisions. Net present value, internal rate of return, payback period. These are standard tools. But the inputs matter far more than the formulas. A discount rate off by one percentage point can flip a positive NPV into negative territory on long-duration projects. The internal rate of return has a particular weakness. It assumes cash flows are reinvested at the IRR itself. This is almost never realistic. A project with a 24% IRR won't actually generate 24% returns on reinvested cash. Modified internal rate of return fixes this by using a separate reinvestment rate, typically the company's cost of capital. It's more accurate but less commonly used in practice. For quick comparisons between projects, I usually default to NPV rather than IRR. It handles multiple sign changes in cash flows without producing misleading results. IRR can give you multiple answers when cash flows switch from positive to negative more than once during a project's life. NPV does not have this problem.
When Formulas Fail
There are scenarios where standard business math simply cannot give you a reliable answer. Supply chain disruptions, sudden regulatory changes, or market collapses create conditions no model can predict accurately. I encountered this during a project in 2022 when commodity prices moved so dramatically that our entire cost structure became irrelevant within weeks. The formulas were correct. The inputs were obsolete. Inventory management models like EOQ assume constant demand and lead times. Real demand fluctuates. Lead times change. Using EOQ blindly in a volatile environment will get you either excess stock or stockouts. The model itself is fine for stable conditions, but you need safety stock calculations layered on top to handle variability. Sensitivity analysis is the practical solution here. Run your model with optimistic, expected, and pessimistic scenarios. It takes maybe 20 minutes in a spreadsheet. The insight it provides about which variables matter most is worth far more than a single precise calculation that may be wrong.
Practical Steps for Solving Business Math Problems
Start by identifying what the question is actually asking. Most errors come from misreading the problem, not from calculation mistakes. Write down what you know, what you need to find, and which variables connect them. Set up your equation before plugging in numbers. This catches conceptual errors early. If your algebra doesn't produce something dimensionally correct, no calculator in the world will fix it. Check your answer against a rough estimate. If your break-even calculation comes out to 2 million units but your monthly capacity is 15,000, something is wrong. The estimate should be within an order of magnitude. Anything farther off means you should retrace your steps.
Document your assumptions. Not everyone who reviews your work will see the same constraints you did. A note about discount rate selection or depreciation method choice prevents confusion and makes it easier to update the model when conditions change.
Tools and Resources
Spreadsheets handle the majority of business math problems adequately. Excel and Google Sheets have built-in financial functions that cover PV, FV, PMT, NPV, IRR, and more. For specialized applications like amortization schedules or depreciation tables, pre-built templates exist and save considerable time. Financial calculators like the TI BA II Plus remain popular among finance professionals for their speed on standard TVM calculations. They don't handle irregular cash flows as gracefully as spreadsheets, but they're reliable for straightforward problems. Online calculators abound for specific use cases. Break-even calculators, margin calculators, compound interest calculators. These are convenient but verify that they use the same definitions and conventions you expect. Some online tools use different base years or day-count conventions that can alter results meaningfully.
For more complex modeling, Python with libraries like numpy_financial or pandas provides flexibility that spreadsheets lack. The learning curve is steeper, but the ability to automate recurring calculations becomes valuable quickly.
Common Mistakes to Avoid
Using annual rates with monthly periods without adjusting. A 12% annual rate is not a 12% monthly rate. Divide by 12 for monthly calculations. This error appears constantly and is usually detectable because the resulting numbers are wildly wrong. Confusing nominal and effective rates. A stated 6% rate compounded monthly is actually 6.17% effective annual rate. The difference seems small but compounds over multiple periods. Loan agreements often quote nominal rates while payment calculations use effective rates. Understanding which one applies matters for accurate comparisons.
Final Thoughts

Business math is practical rather than theoretical. The formulas exist to serve decisions, not the other way around. Understanding the mechanics helps you spot when results look wrong. Experience teaches you which shortcuts are safe and which are traps. The problems themselves are rarely difficult. Getting them right consistently is what takes effort.