The Numbers That Actually Keep a Restaurant Open
Most restaurant operators never sit down and formally define their business model. They open a door, buy equipment, hire staff, and hope the market sorts itself out. That approach fails more often than you would think. I spend most of my week looking at restaurant P&L statements, and the pattern is always the same: the people who survive are the ones who understood their unit economics before they signed a lease. The rest are just gambling with someone else's money.Building a Business Model For A Restaurant
A business model is just a clear statement of how your restaurant makes money, how much it costs to make that money, and who is actually going to pay for it. It sounds simple, but most operators confuse a concept with a business model. A concept is "we serve Korean-Mexican fusion tacos." That is not a business model. A business model includes the average check, the target food cost, the labor ratio, the seating capacity, the table turnover rate, and the math that shows whether any of it works at all. The first step is picking your operating model and accepting the constraints it brings. Fast casual operates on different margins and labor curves than full service. Quick service is a volume game with thin per-unit profit. Fine dining has higher checks but much longer table turns and significantly higher labor and overhead costs. You do not get to pick and choose. The model you choose dictates everything that follows.
Menu Economics and What People Get Wrong
Your menu is your product offering and your pricing strategy rolled into one document. But here is where most operators make the mistake: they optimize for food cost percentage instead of contribution margin per seat. You can have a dish with a 28% food cost and still lose money on it if it takes forty-five minutes to prepare, requires two stations, and blocks a table that could have turned over twice during that same window. Meanwhile, your worst-selling appetizer might be the most profitable item on the menu because it moves fast, costs almost nothing to produce, and requires zero cooking equipment. I worked with a fast-casual concept a few years ago that was struggling to stay solvent despite consistent lunch traffic. They were open twelve hours a day, six days a week, with a skeleton crew of two people during the dinner shift. Their food cost was sitting at a healthy 31 percent. Their problem was not the food. It was labor and rent against a dinner crowd that barely existed. When I pulled together their contribution margin analysis by hour, dinner was costing them roughly four hundred dollars a night in net operating losses after accounting for labor, utilities, and waste. We cut the dinner hours to three nights a week, reduced the menu to twelve items that used overlapping ingredients, and the place started making money within ninety days. The food cost percentage actually went up slightly because we bought less volume, but the overall margin improved because we stopped losing money on hours that should never have been open.
Cost Structure and Where the Money Actually Goes
Your cost structure determines whether your revenue translates into profit or just keeps you busy. Food and beverage costs typically run 28 to 35 percent of revenue for a well-run operation. Labor runs 25 to 35 percent depending on your service style. Overhead—rent, insurance, utilities, software, payments processing—eats another 10 to 15 percent. That leaves you with a net profit margin somewhere between 5 and 15 percent for a healthy restaurant. Most new operators do not hit those targets in year one. Year three is more realistic if they are still standing. One thing nobody talks about enough is waste and shrinkage. I have seen well-managed kitchens throw out or comp away between 8 and 12 percent of their total inventory cost. That number is usually hidden inside the cost of goods sold line and most owners never dig into it. Tracking it properly means weighing what goes in the trash each shift, not just guessing. It takes about twenty minutes per shift and it changes how you order within two weeks.
Get the Full Details

Key Components of a Business Model For A Restaurant
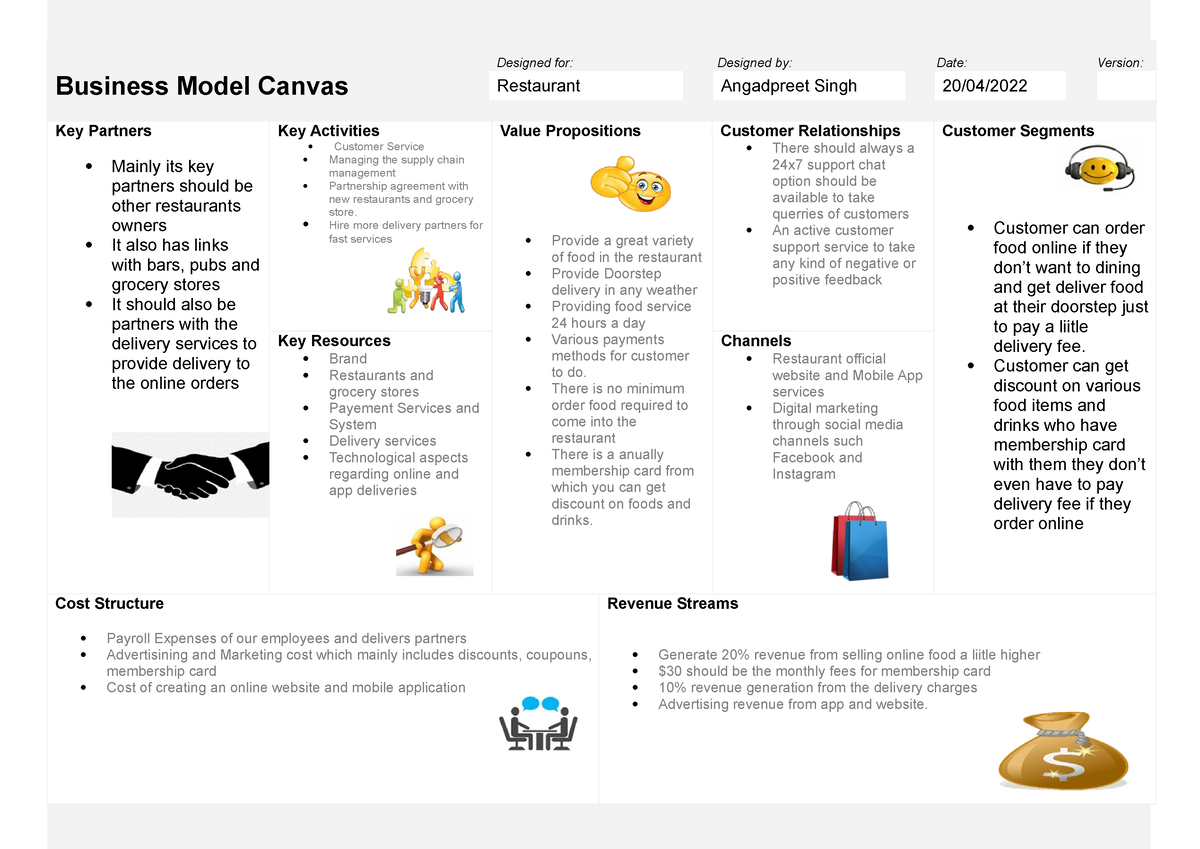
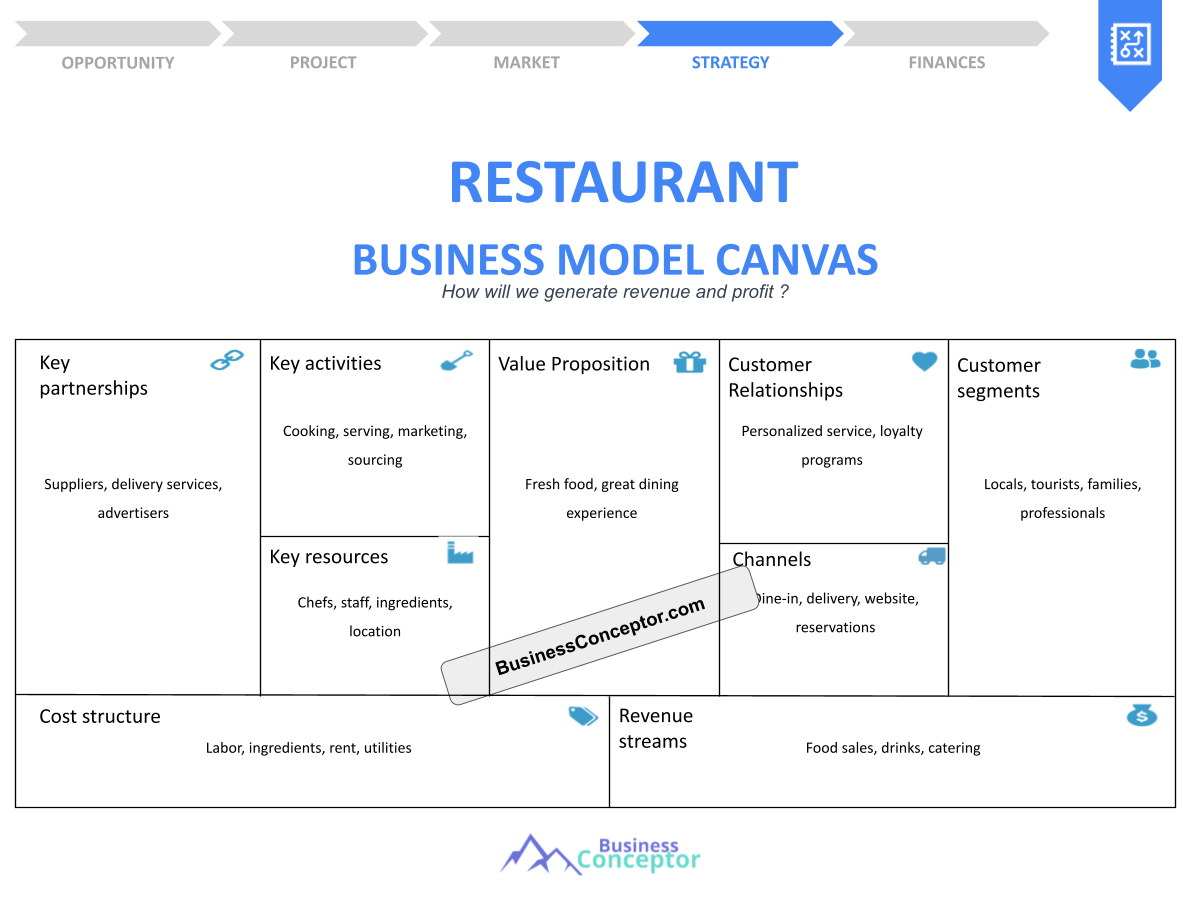
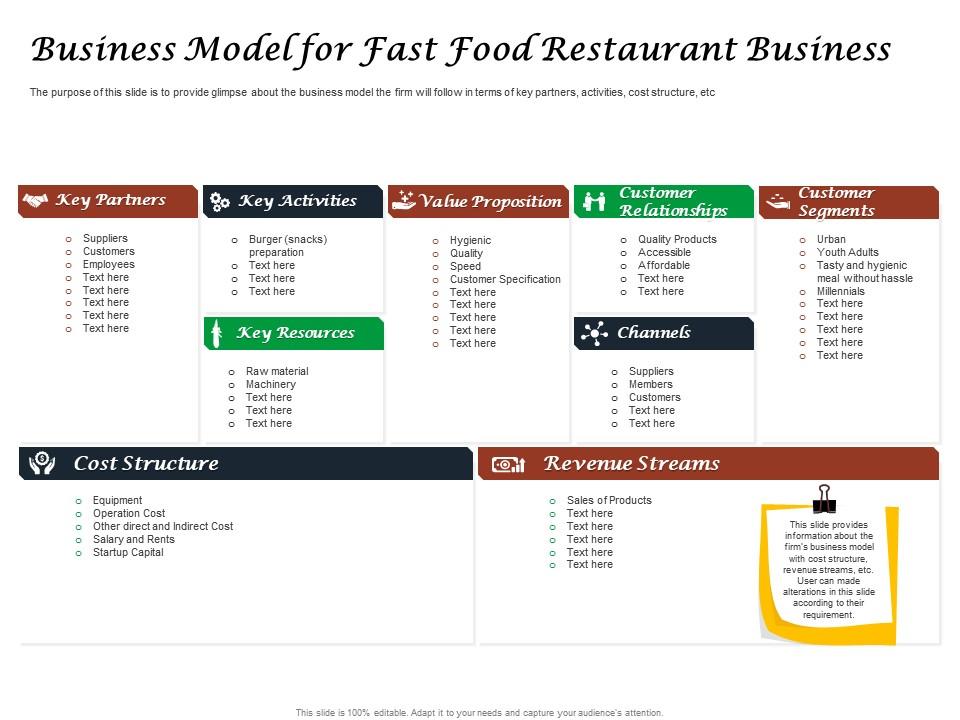
You need to define five things clearly and write them down. Your customer segment: who is actually eating here and why. Your value proposition: what problem you solve for that customer that somewhere else does not. Your revenue streams: cover count, average check, beverage revenue, catering, retail products, delivery fees. Your cost structure: fixed costs versus variable costs, and which one is going to kill you if revenue drops thirty percent. Your channel strategy: walk-ins, reservations, online ordering, third-party delivery apps, corporate catering contracts. Third-party delivery apps are worth a separate mention because they change your economics completely. A $16 entree becomes roughly $11 after commission and fees. If your food cost is 30 percent on that entrée, your effective margin on a delivery order is nearly half of what it is for a dine-in order. Some restaurants build entire menus designed specifically for delivery. Others refuse to participate and lose that revenue stream entirely. There is no universal right answer here. Customer acquisition is another component that gets ignored until it is too late. Your cost to acquire a new customer through marketing, promotions, and advertising needs to be less than the lifetime value of that customer. If you are spending $4 in marketing to acquire a customer who spends $28 once and never comes back, your model is broken. A loyalty program or repeat visit rate above 35 percent is a reasonable benchmark for a standing operation.
The Break-Even Analysis That Matters
You need to know your break-even point in dollars and in covers. This is not optional. If you do not know how many seats you need to fill per day to stay alive, you are flying blind. Take your total monthly fixed costs—rent, insurance, salaries for managers, software subscriptions, minimum utility costs—and divide by your average contribution margin per cover. That gives you the number of covers you need to break even each month. Divide by thirty days and you know your daily break-even. If your daily break-even is seventy-five covers and your average day last month was sixty-two, you already know your problem before you look at anything else. I had a client who was convinced his restaurant was losing money because his food quality had slipped. The food quality had not slipped. His break-even had moved from sixty covers to one hundred and ten because rent increased, labor costs rose with minimum wage adjustments, and ingredient costs climbed roughly eight percent over eighteen months. He was still running his old number in his head. Once we recalculated his break-even and saw that he was operating thirty covers below it, the real problem became obvious. He needed either higher checks, lower costs, or more covers. Those are the only three levers available.
Where This Approach Breaks Down
This method assumes you have reliable data. If your point of sale system is throwing errors, your inventory tracking is guesswork, and your labor scheduling is based on whoever happens to show up, none of this analysis will help you. The model is only as good as the numbers you put into it. I have reviewed business plans from owners who were proudly reporting 22 percent food cost when their actual cost was closer to 34 percent because they were not recording waste, spoilage, or employee meals. Twenty-two percent sounds impressive until you compare it to reality. The model also assumes some level of operational control. If you are constantly changing your menu, your pricing, or your staffing structure, you will not have stable data to analyze. This works best for an established operation with at least six months of consistent financial history. For a brand-new concept with no track record, the model is mostly theoretical and needs to be treated as a set of assumptions that will change as you learn what actually works. There is also a limit to how far you can push optimization before the restaurant stops being a restaurant. If you cut the menu down to five items to reduce waste and labor, you may reach break-even faster but you will also lose the customers who came for the variety. If you raise prices by twelve percent across the board, your margin improves immediately but your volume will drop, usually within the first month. The relationship between price and volume is not linear and it varies by market, concept, and location. You need to test it rather than assume it.
What to Track Instead of What Everyone Else Tracks
Most operators obsess over gross profit percentage and food cost percentage. Those numbers matter but they are lagging indicators. They tell you what already happened. What matters more are the leading indicators: customer acquisition cost, repeat visit rate, average check trend, table turnover rate, cost per covered seat, and labor cost per hour of operation. These tell you where you are heading before the P&L statement confirms it. Your labor cost per hour of operation is one of the most underutilized metrics in this industry. It combines scheduling efficiency, sales volume, and wage rates into a single number. If your labor cost per hour of operation rises while your sales per labor hour falls, something is wrong even if your overall labor percentage looks acceptable. That combination usually means your slower hours are understaffed while your peak hours are overstaffed, or vice versa. The fix is almost never "hire fewer people." It is rethinking your schedule structure. I recently worked with a breakfast and lunch spot that ran a tight operation on paper. Their food cost was 29 percent, labor was 27 percent, and their net margin looked respectable at 11 percent. But when I broke down the data by service period, the dinner shift was unprofitable and the lunch shift was barely covering its own fixed costs. The breakfast shift was the only one generating real margin. They had been subsidizing dinner with breakfast profits for eighteen months without noticing. They closed dinner six days a week within two months and became profitable within ninety days. Nothing changed about the food, the staff, or the location. Only the hours changed.
Practical Steps to Define Your Model
Start with your concept statement and write it in one sentence. If it takes more than two sentences to explain who you serve and what problem you solve, you do not have a clear enough concept yet. Write down your target customer profile with specific demographics and behavior patterns. Then build a one-page financial model with your best estimates for average check, covers per day, food cost percentage, labor percentage, and fixed monthly costs. Calculate your monthly break-even in dollars and in covers. Run three scenarios: conservative, expected, and optimistic. The conservative scenario should assume twenty percent fewer covers than your expected one. If you cannot survive the conservative scenario, your model is too fragile for a new operation. Review this model every quarter. Update it with actual numbers, not guesses. The differences between your projected and actual figures will teach you more about your business than any consultant report. Most operators never do this review. They pull a P&L at the end of the year and wonder why they do not understand their own business. Your business model is not a document you write once and file away. It is the framework you use to make decisions about hiring, pricing, menu changes, hours, and expansion. The restaurants that fail are usually the ones that kept making decisions without a clear model to evaluate them against. The ones that survive tend to be the ones that knew their numbers and adjusted when reality diverged from their assumptions.