Writing a Business Plan For A Small Restaurant
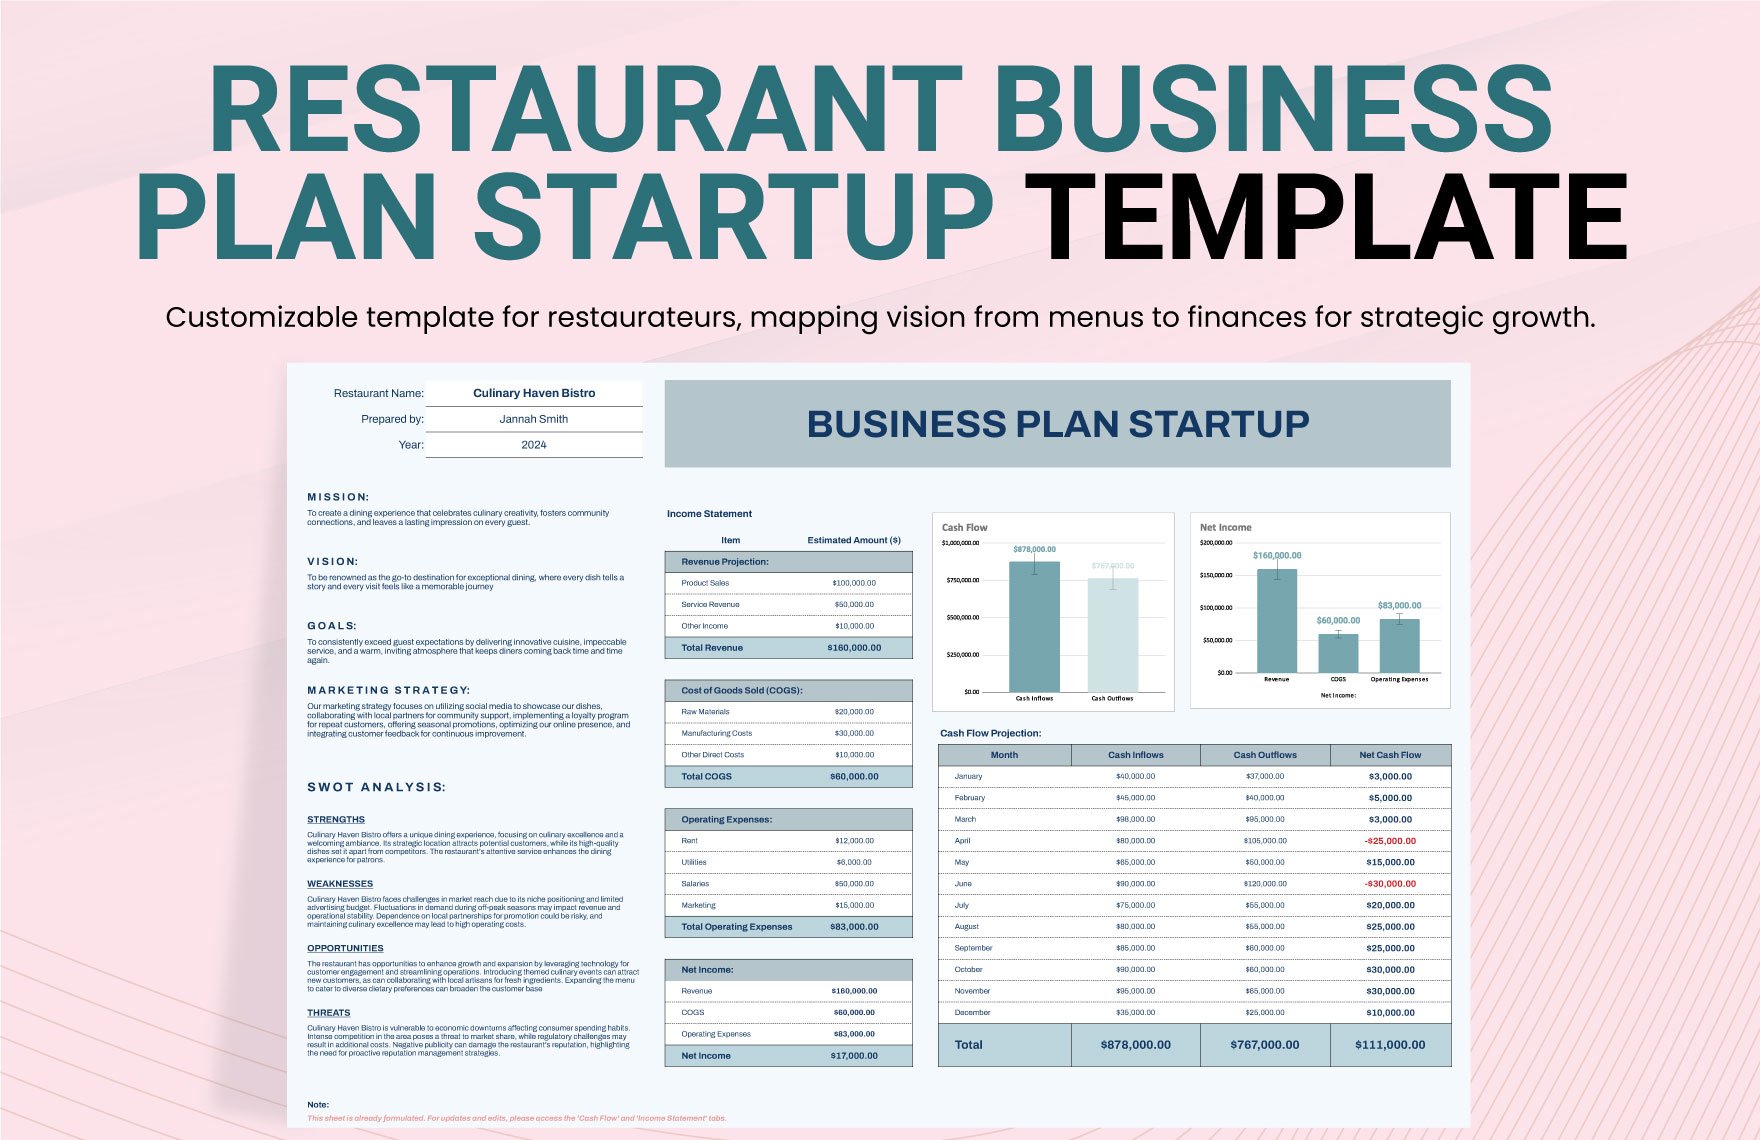
A business plan for a small restaurant isn't some grand visionary document. It's a working spreadsheet with a cover page attached. I spent six years running a 40-seat Italian place in a mid-tier city before selling the lease. The plan I filed with the SBA and showed to my lender looked nothing like the templates you find online. It was mostly labor projections, menu cost sheets, and three scenarios for what happens if health inspector shuts us down for two weeks. Here's how I built mine, starting from the thing most people get backwards. Start with the food cost model, not the revenue estimate. Most first-time operators project how many covers they'll seat per night, then work backward to revenue. That's where plans fall apart. Food cost is your hard constraint. If yourCOGS sits at 32 percent on the menu you actually want to serve, and your target gross margin is 68 percent, you can calculate the minimum revenue you need to cover rent, labor, and overhead before you even think about profit. I built a live menu engineering sheet first — entrees, appetizers, desserts, each with ingredient-level costs updated weekly. The moment you know your lowest viable revenue number, everything else becomes a planning variable instead of a guess.
My food cost model accounted for waste, spoilage, and comped meals from day one. That's where most spreadsheets lie. A single server comping a $28 entrée twice a week during soft opening isn't an exception — it's the norm for the first three months. I baked that in as a line item called "operational waste" at 4.5 percent of food sales and it saved me from understating costs by roughly $18,000 in year one alone. Labor modeling is where small restaurant plans actually die. You need a scheduling matrix mapped to your projected peak hours, not your average hourly covers. If you're open dinner only and your 6 to 9 PM window requires four cooks and three servers per shift, your labor cost isn't based on a 200-cover week. It's based on the nights you actually run that close to capacity. I built a week-by-week labor forecast for the first six months that accounted for training drag — new hires run at roughly 60 percent efficiency for their first three weeks. That means you need extra staffing during that window or you're burning money on overstaffing for the learning curve. The counter-intuitive part nobody talks about: your front-of-house labor doesn't scale linearly with covers. A restaurant doing 80 covers per night needs less than half the FOH staff of one doing 160, because table turnover changes the equation. Two 40-cover seats with 2.5 turns per night is cheaper to staff than one 100-cover seat with one slow turn. I learned this the hard way when we briefly ran a lunch menu that added 40 covers but required an entirely separate shift setup. The incremental revenue barely covered the incremental labor. We dropped lunch after month four.
Operating Expenses Most People Miss
Besides food and labor, your actual monthly burn has a few invisible lines. Repairs and maintenance on a commercial kitchen averages 1 to 2 percent of gross revenue annually, but it's lumpy. A walk-in compressor failure doesn't spread evenly across months. I set aside a monthly reserves line at 1.5 percent of projected revenue specifically for this. When the hood system needed re-lining in month fourteen, that line item paid for it without touching operating cash. Insurance, licenses, and compliance costs are fixed but often underestimated. A typical small restaurant in a US metro area pays between $4,000 and $8,000 annually for general liability, workers compensation, and food service insurance combined. Health department fees, liquor license renewals, and fire inspection certifications vary wildly by municipality. In my city, the annual fire suppression inspection alone was $1,200. These aren't dramatic costs but they're easy to forget when you're calculating break-even on paper. Technology costs have shifted significantly. Point of sale systems, online ordering platform fees, reservation software, and inventory management tools now run $300 to $800 per month for a small operation. Some of these platforms charge per transaction, which compounds quickly. If you're processing $60,000 in monthly sales through an online ordering portal that takes 15 percent, that's $9,000 gone before it hits your bank account. Factor that into your model or you'll wonder where your margins disappeared.
Get the Full Details

Financial Projections That Actually Work
Three-scenario modeling isn't optional. Write a base case, a conservative case, and a stress case. The conservative case should assume 70 percent of your base revenue for the first twelve months and hold costs flat. The stress case assumes 50 percent revenue with costs increasing by 10 percent due to supply chain disruption. Most small restaurant lenders want to see all three. More importantly, you need to see them yourself. I ran my stress case for the sixth month and realized that at 50 percent revenue with elevated COGS, our cash reserve would hit zero in month eight. The workaround was negotiating a $25,000 line of credit before signing the lease, not after. Having it ready to draw on rather than applying for it during a crisis changed whether we survived the pandemic-adjacent slowdown in early 2022 or closed. The plan document captured that contingency. Without it, the same plan looked fine on paper. Break-even analysis for a small restaurant typically falls between 60 and 75 percent of your projected monthly revenue. Below that threshold, you're losing money. Above it, you start building a margin buffer. Knowing your exact break-even point — calculated from your fixed costs divided by your contribution margin per dollar of sales — tells you what each additional cover is actually worth. If your contribution margin is 55 percent and your fixed monthly costs are $38,000, you need roughly $69,000 in revenue to break even. Every dollar above that is 55 cents going toward covering whatever comes next.
What the Plan Should Actually Look Like
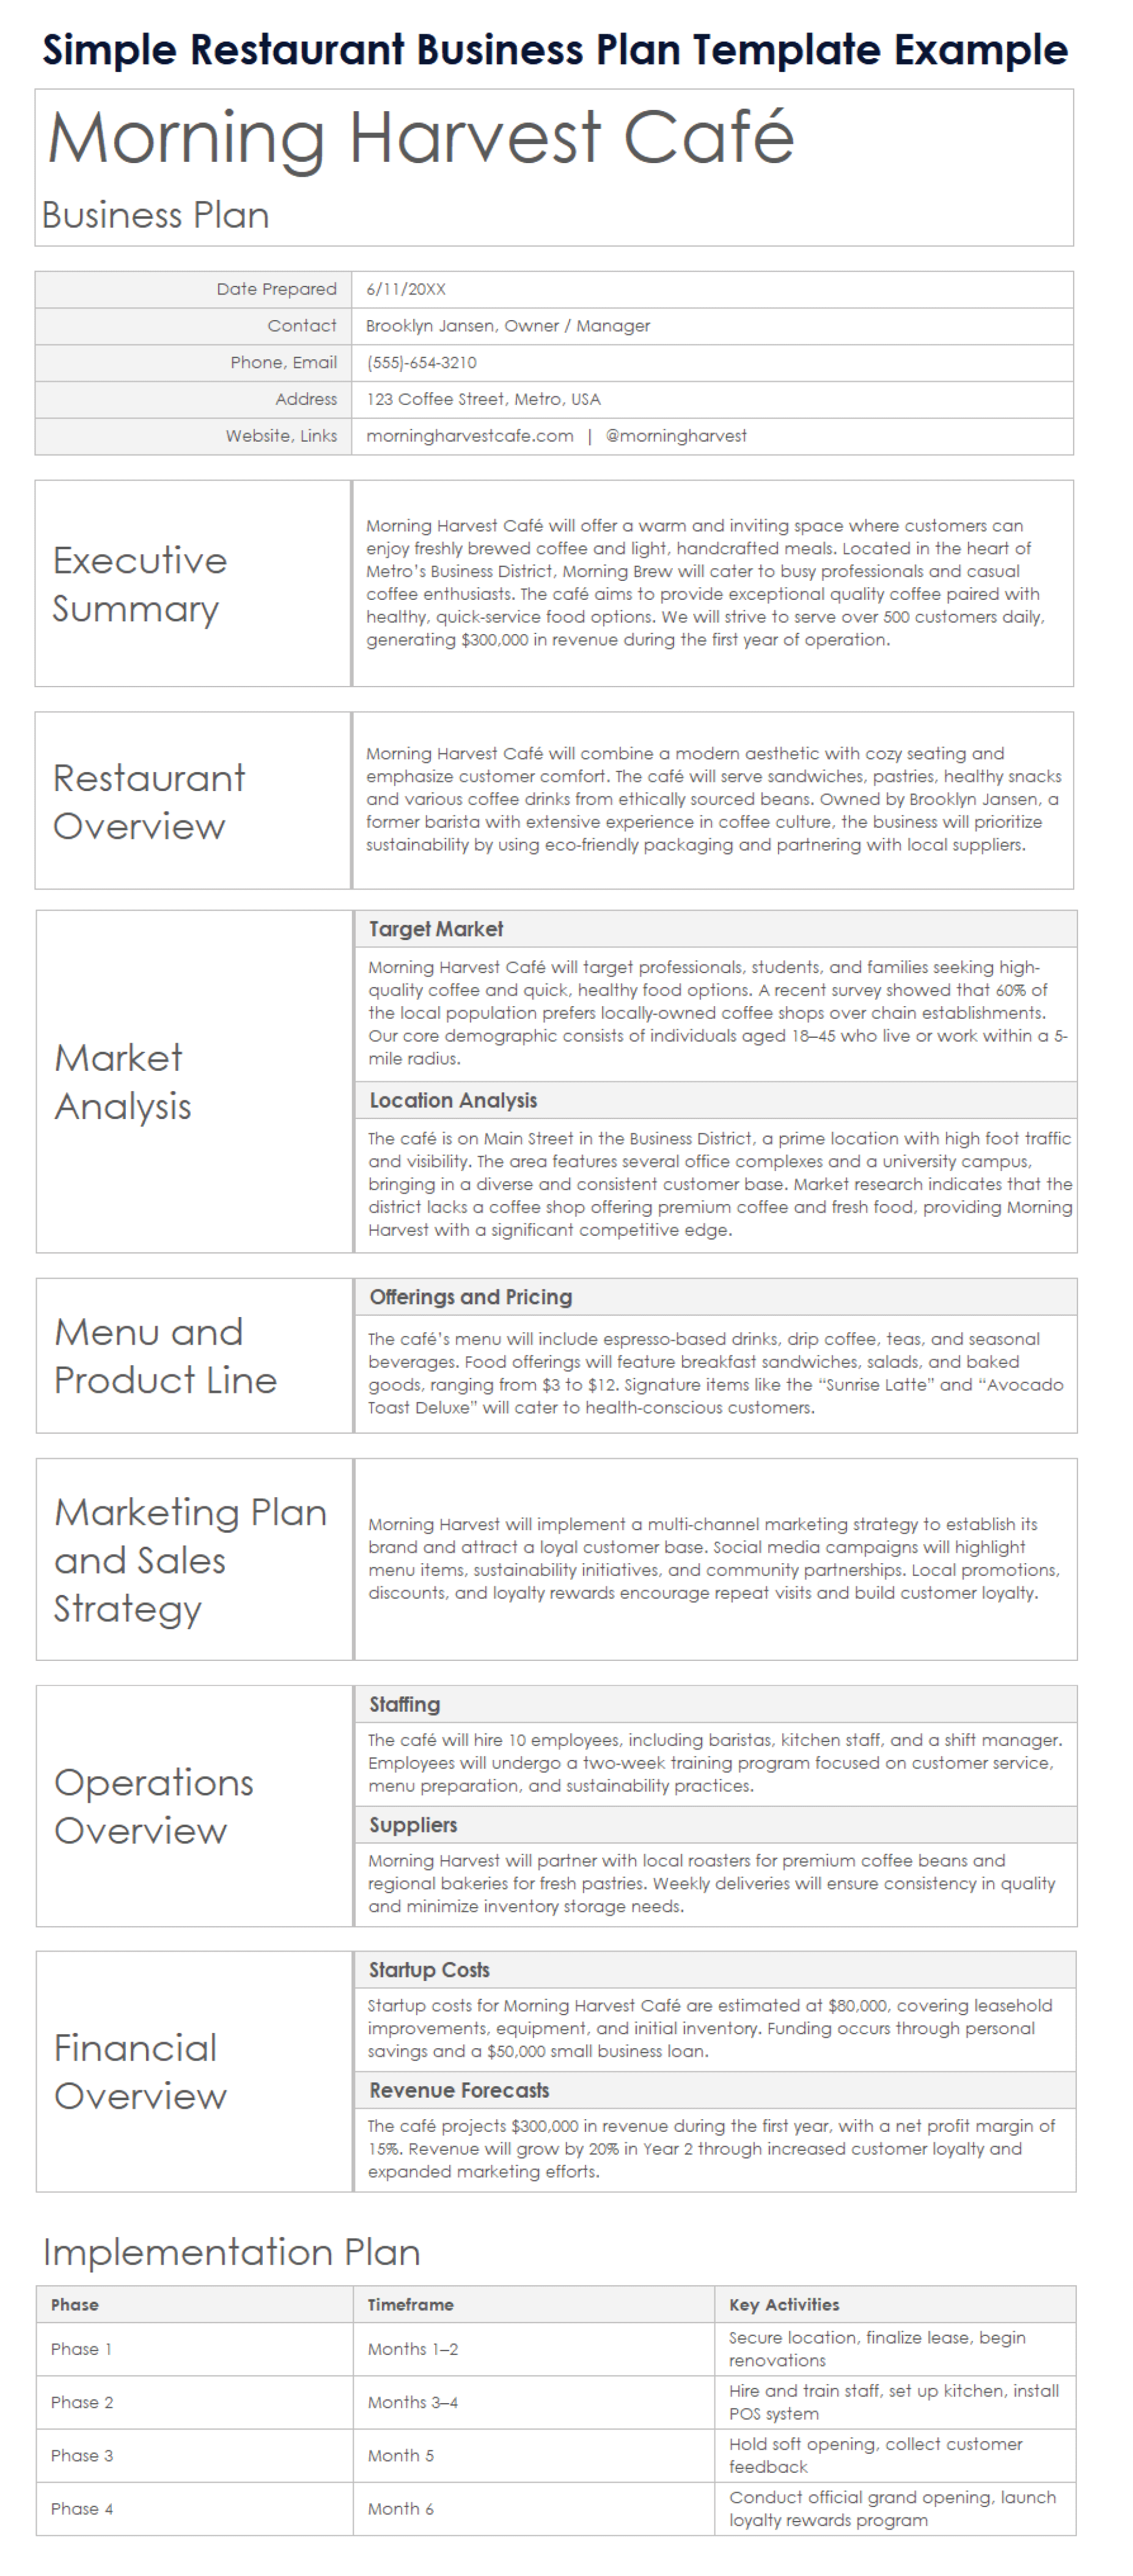
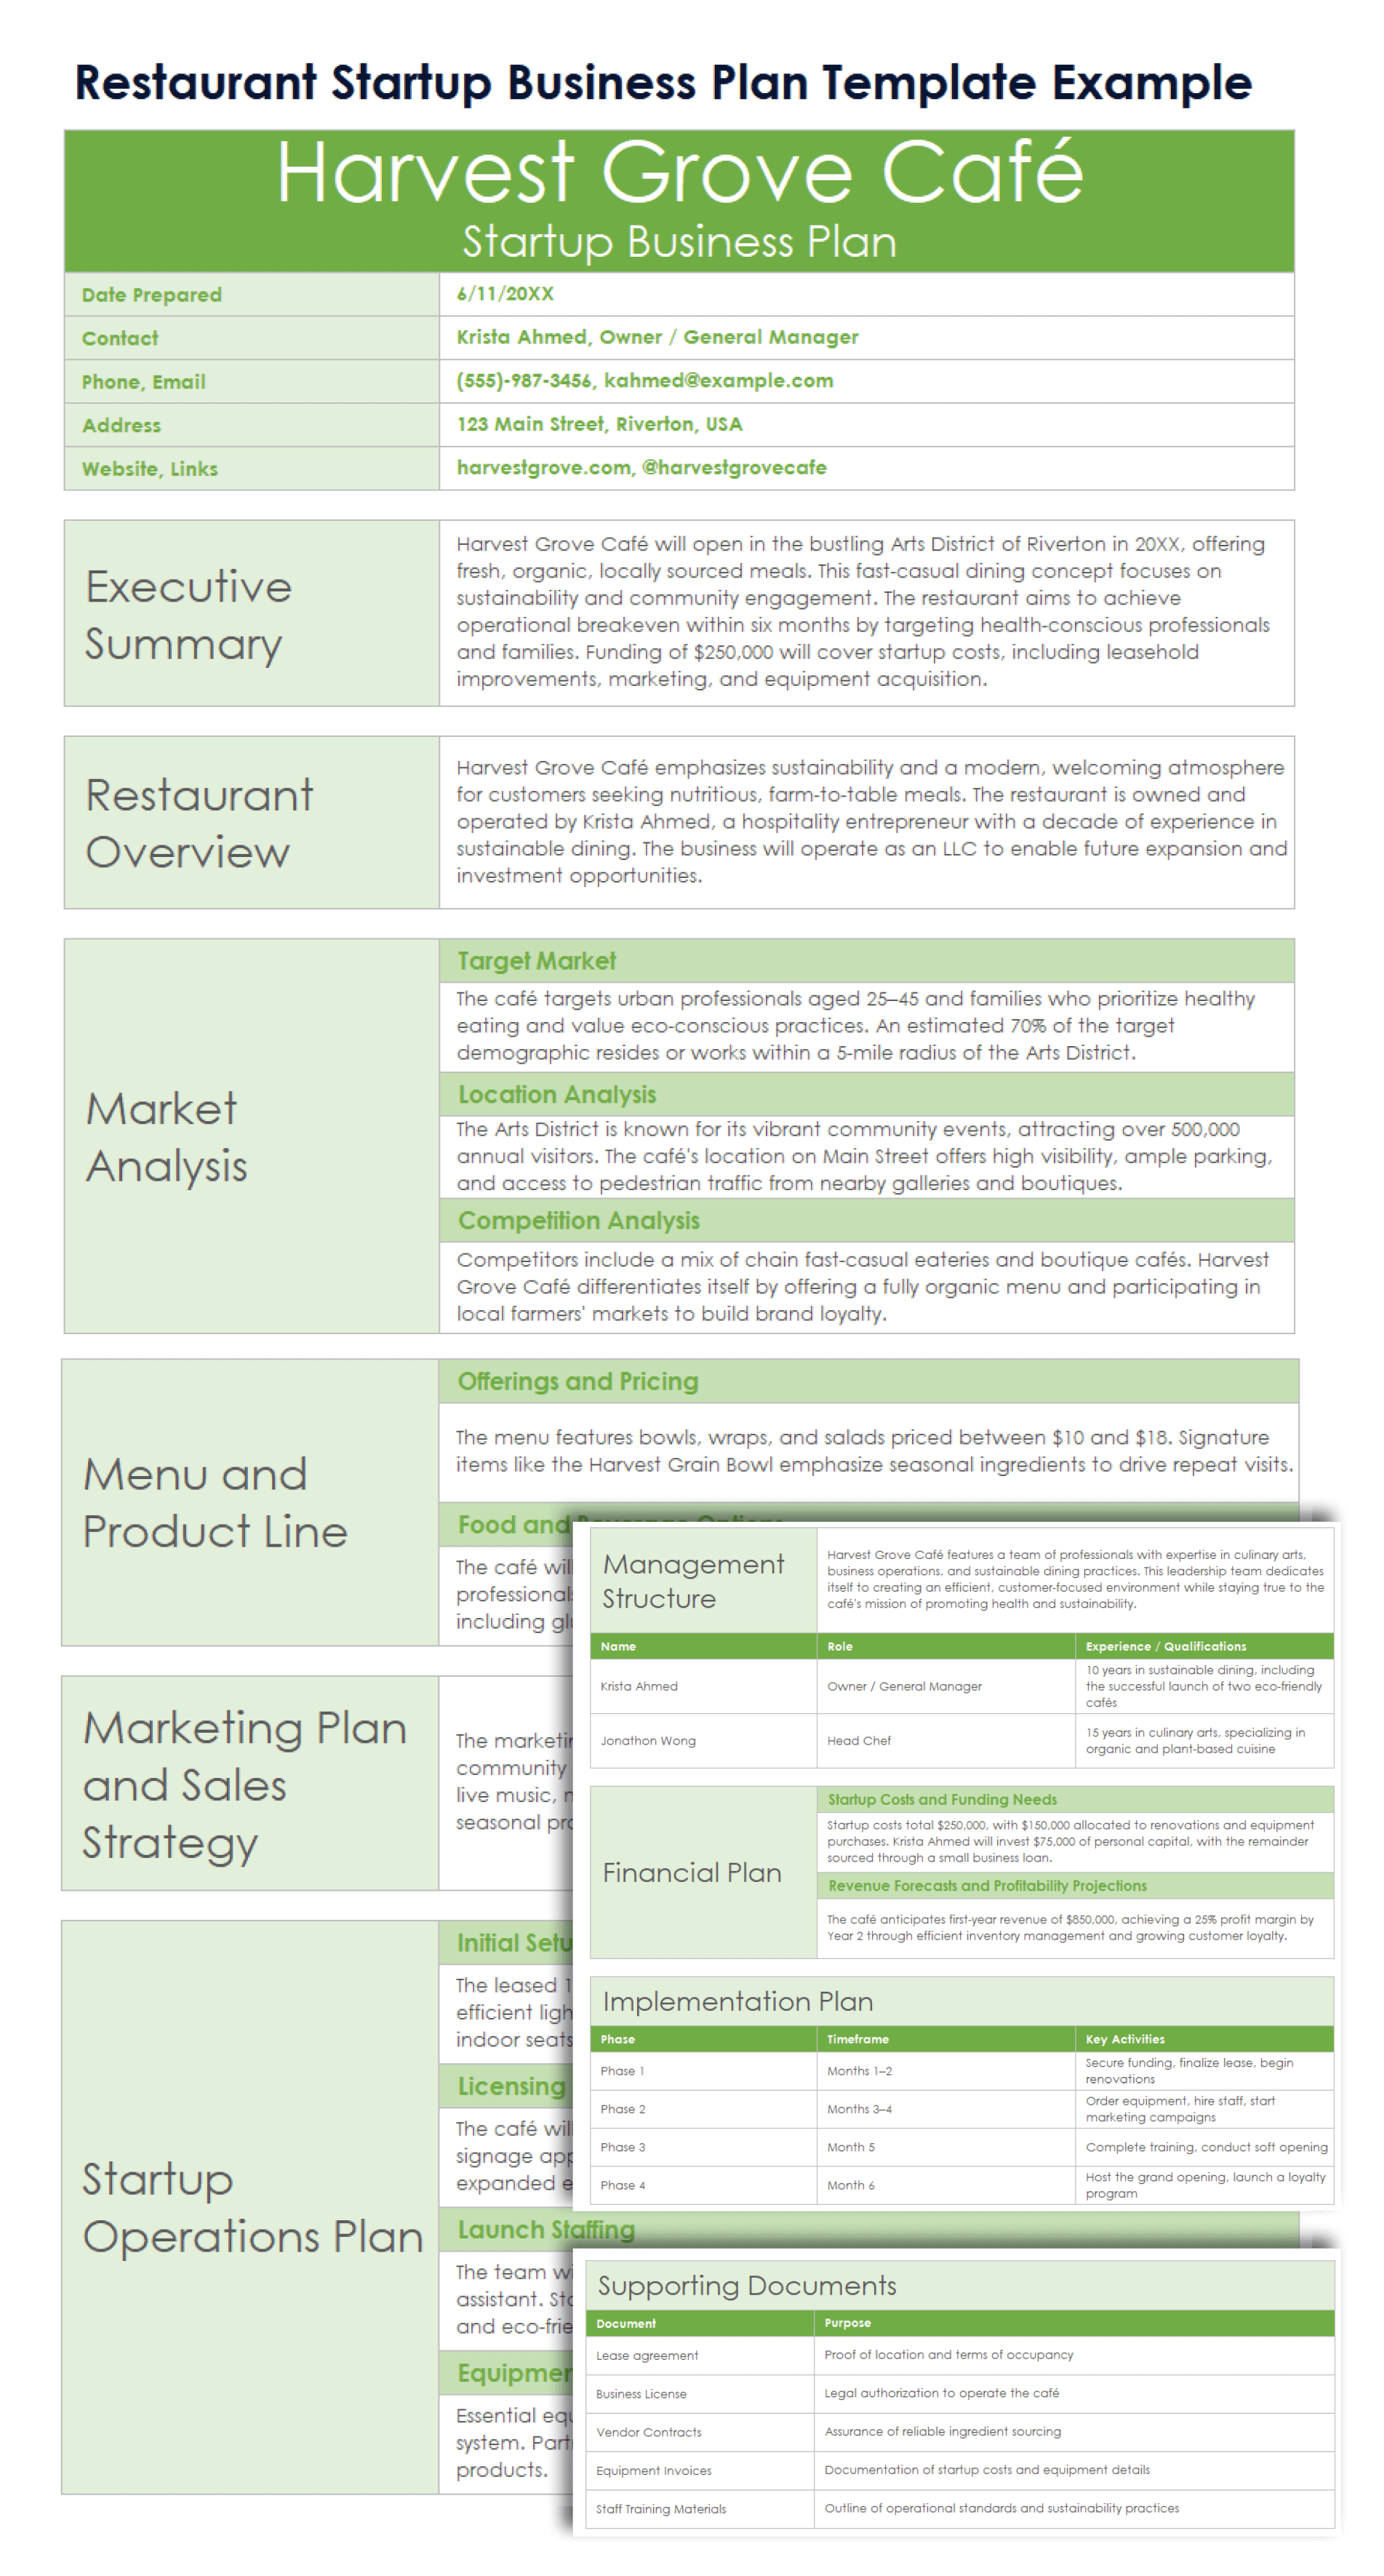
A functional small restaurant business plan runs 15 to 25 pages. It includes an executive summary, concept description, market analysis, menu overview, operational plan, management structure, financial projections, and funding requirements. The financial section is the only part that matters to a lender. The rest is mostly for your own clarity. The menu section should include a draft menu with price points and food cost percentages. Not final prices, but working prices. Your menu will change three times in the first year as suppliers shift and items get pulled. A plan that locks in specific dish pricing from day one will look unreliable to anyone reading it. Instead, show your target food cost range and explain how menu engineering supports it. Market analysis for a small restaurant doesn't require a full demographic study. You need to answer three questions: who is within a five-minute drive time during dinner hours, what are they currently spending on similar food, and what gap exists between what they're getting and what you're offering. I used Google Maps traffic data, reviewed aggregators, and sat in competitor restaurants on a Thursday night taking notes on party size, average check, and turnover rate. That fieldwork was worth more than any Census Bureau report.
Where This Approach Fails
A detailed business plan is not useful if your concept depends on viral social media attention or seasonal tourism. Plans built around a 90-day trend or a summer-only beach town location are structurally fragile. The model assumes consistent demand patterns that simply don't exist in those environments. If you're opening a restaurant in a college town, your plan needs to account for four months of significantly reduced revenue per year. If you're opening a concept that relies on influencer foot traffic, your plan is a gambling chip, not a roadmap. Another limitation: business plans don't capture operator skill. A perfectly modeled plan can still fail because the person running the kitchen can't manage a team of five cooks, or the owner can't handle the daily cash flow discipline small restaurants demand. The plan is a framework, not a guarantee. It works best when paired with someone who has worked inside a kitchen or behind a host stand before putting pen to paper. If you're looking for a template to start from, the SBA offers a free business plan builder at sba.gov/tools/business-plans and Spotahome maintains a restaurant-specific financial model that accounts for COGS, labor, and fixed costs in a single spreadsheet. Both are starting points, not finished products. The work is in filling them with numbers that reflect your actual market, not an average you pulled from a blog post.