What Most People Miss About Writing a Business Plan as a Mortgage Loan Officer
Most loan officers treat their business plan like a compliance checkbox. They dump some generic projections into a template and submit it to their UWMG or EHV file. That works for getting your name on the wall. It does not work for actually running a business. I learned that the hard way. In year two, I had a production volume that looked good on the surface but I was bleeding cash on overhead. My pipeline reports told me I was busy. My P&L told me I was losing money. The disconnect was my business plan never accounted for comp splits, desk charges, or the fact that about 30 percent of my initial pipeline dropped before closing. Once I rewrote the plan around actual numbers instead of fantasy volumes, everything changed.
Business Plan For Mortgage Loan Officer: How to Actually Build One
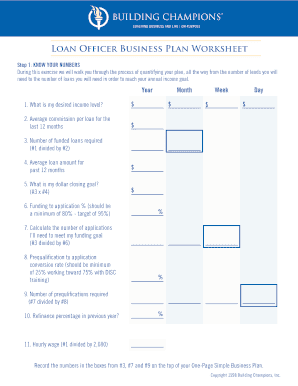
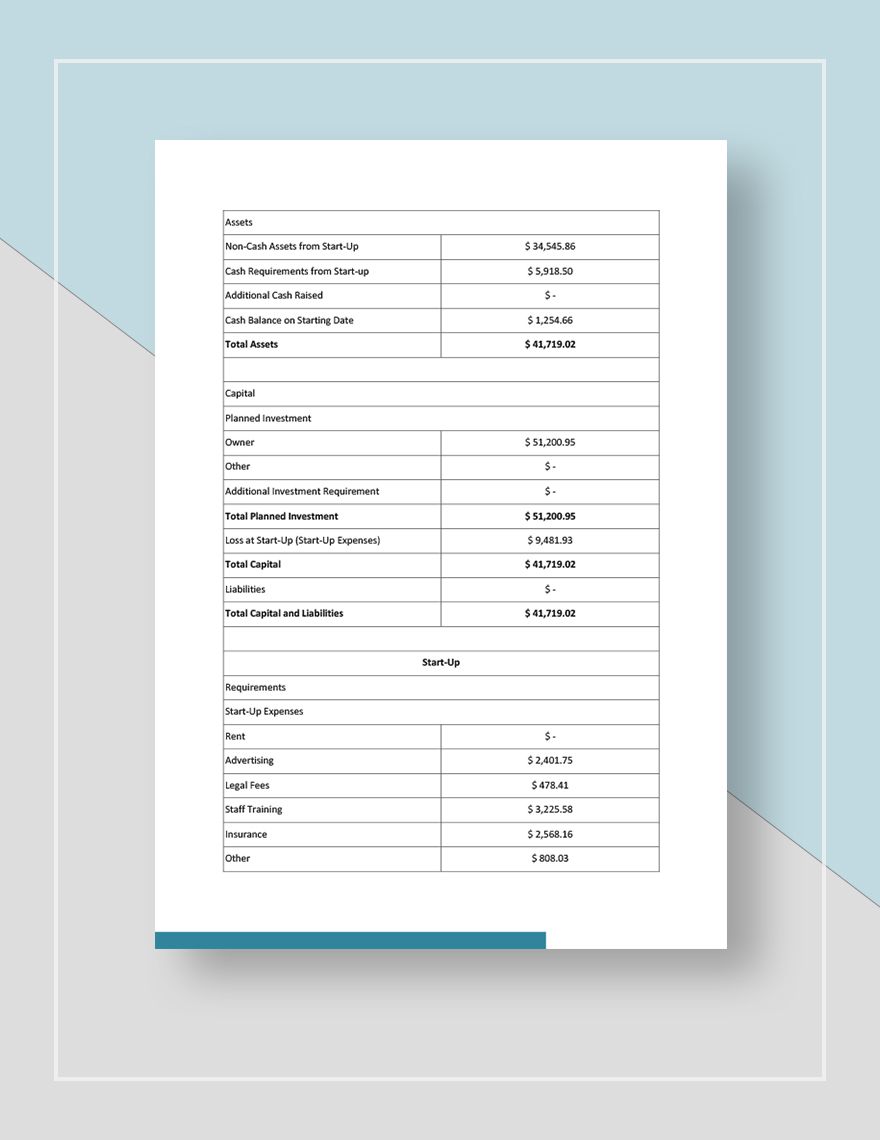
Start with your compensation structure. This is where beginners always mess up. If you are W2 with a salary plus bonus, your revenue model is straightforward. If you are 1099 commission based, you need to map out every revenue stream: origination fees, yield spread premiums if you still get them, broker fees, and any desk charge deductions. Most officers I talk to forget to subtract the desk charge until quarter three when they realize their projected take-home pay is off by 40 percent or more. Your expense section needs to be granular. I am talking specific line items. CRN background check at roughly 65 dollars per report. E&O insurance, anywhere from 800 to 2000 dollars annually depending on coverage. Your lockbox fee through your wholesaler. Direct mail campaigns. Sphere of influence events. Software subscriptions for your CRM, transaction management platform, and lead gen tools. A fresh loan officer budgeting these out properly usually lands between 15000 and 35000 dollars in annual operating expenses depending on their market and production level. Here is the part nobody talks about enough. Your funding pipeline projection. New officers love to project 50 loans in their first year. But let me walk you through what actually happens. You close 6 in the first quarter because your sphere does the heavy lifting. That drops to 4 per quarter in months four through nine because cold lead followup is brutal. Then maybe you pick up to 7 per quarter once your referral network stabilizes. A realistic Year 1 projection for most new LOs is 20 to 35 closed loans depending on market conditions and effort level. I have seen officers hit 50 in a hot market, but that is the exception not the rule and you need to justify those numbers with specific strategy not wishful thinking.
When it comes to marketing strategy, most plans are garbage because they say things like build brand awareness and expand referral sources. Pick three specific channels and commit to them. Direct mail to your past clients with a quarterly homeownership update. A targeted Facebook or Instagram campaign aimed at first-time homebuyer demographics in your top two zip codes. Weekly email newsletters to your database with market updates. Track the cost per acquired loan for each channel. After six months you will know which one actually pays for itself and which one is just burning budget. One thing I wish someone had told me is that your business plan should be a living document not a PDF you file and forget. The best approach is a quarterly review cycle. Each quarter sit down and compare actual performance against your plan. If you projected 10 loans and closed 6, figure out why. If your average loan size came in at 350000 instead of your planned 425000, adjust your revenue model. This is how you avoid the mid-year panic I experienced in my second year when I realized I was underwater against my own projections and had no idea why. There are also downsides to relying too heavily on a written business plan. Markets shift fast and rate environments can wipe out your assumptions overnight. If rates jump from 6 to 8 percent, your entire pipeline projection becomes obsolete. You need to build in contingency scenarios. Model what happens at different rate environments so you are not scrambling when the Fed moves. Also be honest about your personal runway. If your plan assumes break-even by month eight but you only have six months of savings, you are already behind before you start. Factor in a personal financial buffer and do not skip it because it makes the numbers look worse on paper.
Get the Full Details
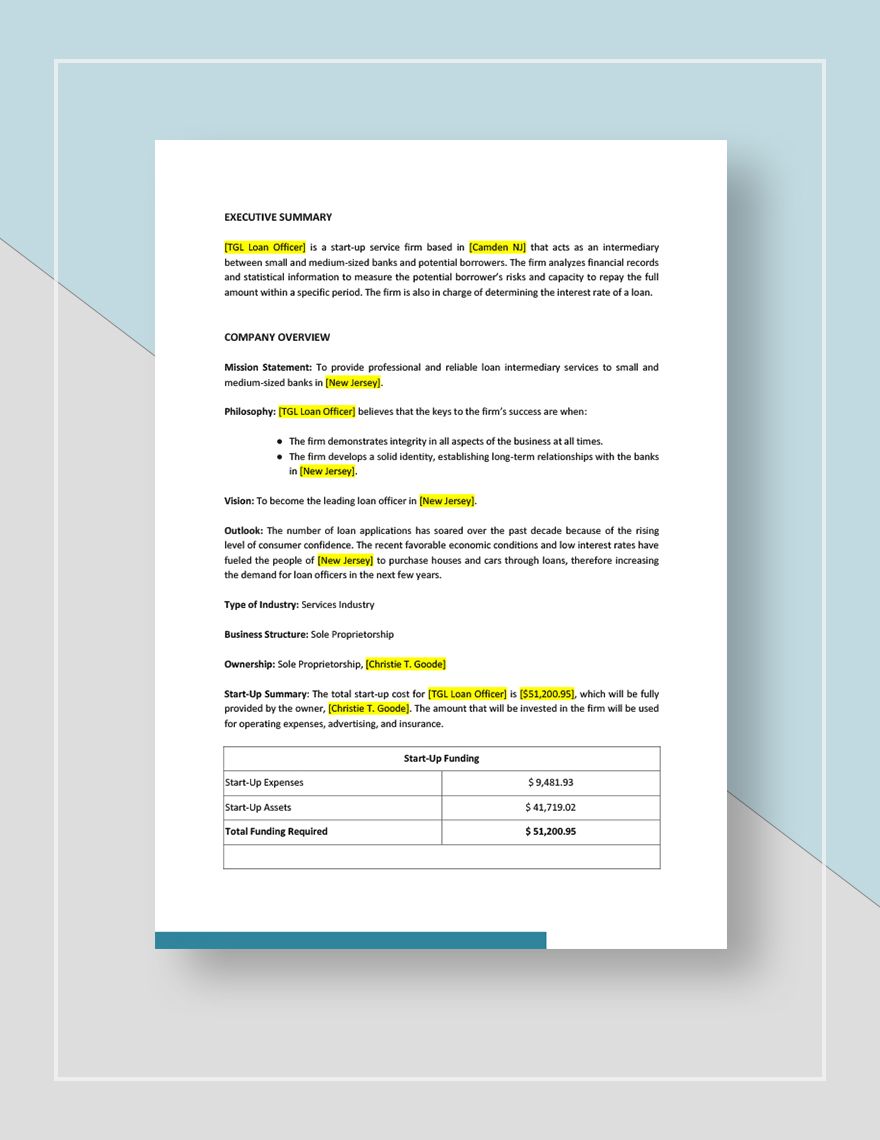
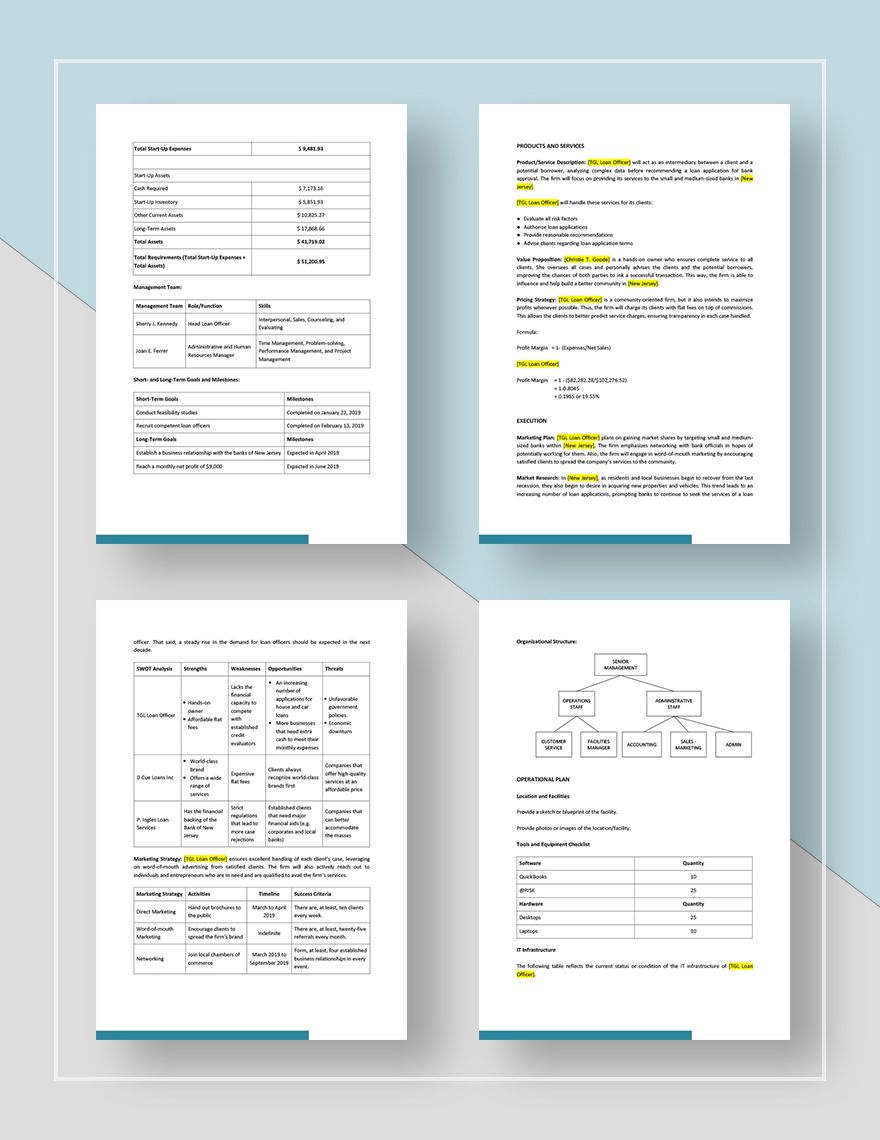
If you want a template to start with, the MBA and state mortgage associations often provide basic business plan frameworks for loan officers. They are not perfect but they give you the right skeleton to build on. I would not recommend paying for expensive template packages online. Most of them are generic and designed for small businesses in general, not the specific realities of mortgage lending compensation and regulatory compliance. The bottom line is this. A real business plan for mortgage loan officer work is not about impressing anyone. It is about knowing your numbers cold so you can make decisions when things go wrong. And they will go wrong. You will lose deals at the appraiser stage. Your processor will call out sick the week before closing. Your lead source will dry up. Having a plan with actual projections means you know exactly how much time and money you have before you hit a wall. That is worth more than any motivational quote about chasing dreams in this industry.