Writing a hotel business plan doesn't require a consultant, just a solid template and some real numbers.
Most people grab a generic business plan template and try to shoehorn hotel operations into it. That's the first mistake. Hotels have different revenue streams, different cost structures, and different metrics than almost any other business type. A restaurant template won't work. A retail template will mislead you. You need something that accounts for occupancy rates, RevPAR, room nights, and seasonal fluctuation.I spent a few years working with small independent hotel owners trying to get bank financing. The ones who got approved didn't have the prettiest plans. They had plans where the numbers actually made sense internally. The template matters less than the discipline behind filling it out, but starting with a blank document is a recipe for disaster. A good Business Plan Template For Hotel should already have sections for your ADR calculations, your departmental P&L breakdown, and a revenue forecast that isn't just a single line growing 10% every year. Here's what you actually need in the document, laid out in the order that makes the most sense when you're trying to figure out if this venture can survive. This is the part most people skip or gloss over. Start with your revenue assumptions. Not your hopes. Your assumptions. If you're opening a 50-room boutique hotel in a suburban market, you need to decide what your achievable occupancy rate is month by month for the first three years. Not the industry average. Your number.
I once reviewed a business plan from someone who projected 85% occupancy in year one for a new hotel in a market where the best-performing property was running at 62%. The underwriter didn't even read past that table. It was over before it started. You can be ambitious. But the gap between your projection and what the actual comparable properties are doing needs an explanation, not a wish. From occupancy, you derive room revenue. Then you layer in food and beverage, meeting space, parking, resort fees, anything else that brings money in. Hotels often have multiple revenue centers, and each one has its own cost structure. Room revenue has very different COGS than restaurant revenue. Your template needs to separate these, otherwise your gross margin will look like fiction.
Operating expenses need the same level of detail.
People tend to underestimate labor costs in hotels because they don't realize how many positions actually exist. Front desk, concierge, housekeeping, maintenance, shift supervisors, general manager, executive housekeeper, revenue manager. In a small property, one person might wear two hats, but that doesn't eliminate the labor cost. It just means you're paying one salary for two jobs, which is a different kind of risk. Utilities in a hotel are not a fixed expense. They scale with occupancy. HVAC, laundry, pool heating, lighting in public areas. If you model utilities as a flat monthly number, your break-even analysis will be wrong. Use a per-available-room-night figure based on utility data from comparable properties, then multiply by your projected occupancy. Insurance for hospitality properties is significantly higher than standard commercial insurance. I learned this the hard way when a client budgeted for generic commercial rates and came in $18,000 short in the first year. Get actual quotes early. Don't estimate from a template.
Get the Full Details
Your competitive analysis should be brutal.
This is another section where people go soft. Look at the three properties within a five-mile radius of your location. Not the luxury resort twenty miles away. The ones that are actually competing for the same guest. What are their ADRs? What are their occupancy rates? Where do they rank on reviews? What do their reviewers complain about? I pulled occupancy and ADR data from a public STR report for a client once. The market was saturated with supply coming online in eighteen months. His plan assumed no new competition. The bank asked him to run a stress test at 90% of his projected rate. He did, and the numbers still worked. That stress test is what got him funded.
Seasonality isn't optional. Factor it in.
If your hotel is in a seasonal market, your cash flow will look nothing like your annual average. A beach property might make 60% of its annual revenue in four months. Your staffing plan, your marketing spend, your debt service coverage ratio all need to account for the lean months. Lenders look at this. They want to see that you can cover your fixed costs during the low season without dipping into reserves you don't have. One workaround I used successfully: instead of modeling seasonality as wild swings, I smoothed it into a mild wave pattern. Peak months at 110% of average, shoulder months at 95%, off-season at 70%. It's more defensible than dramatic roller-coaster projections, and it still forces you to plan for the cash crunch.
Exit strategy matters even if you don't plan to sell.
Lenders want to know how they get paid back. Investors want to know their return timeline. Your business plan template should include a section on your exit options whether that's a sale in five to seven years, a refinance, or a long-term hold with steady distributions. If you don't have a direction, it looks like you're improvising. I've seen people skip this entirely and the answer is always "I plan to operate it indefinitely." That's fine personally. For a business plan, it's insufficient. Even if you're holding forever, you need to show the underlying asset generates enough cash flow to support your debt obligations through market cycles. Run a 20% revenue downturn scenario. See if the numbers still hold. If they don't, you've identified your vulnerability before someone else does.
The template itself should be flexible but structured.
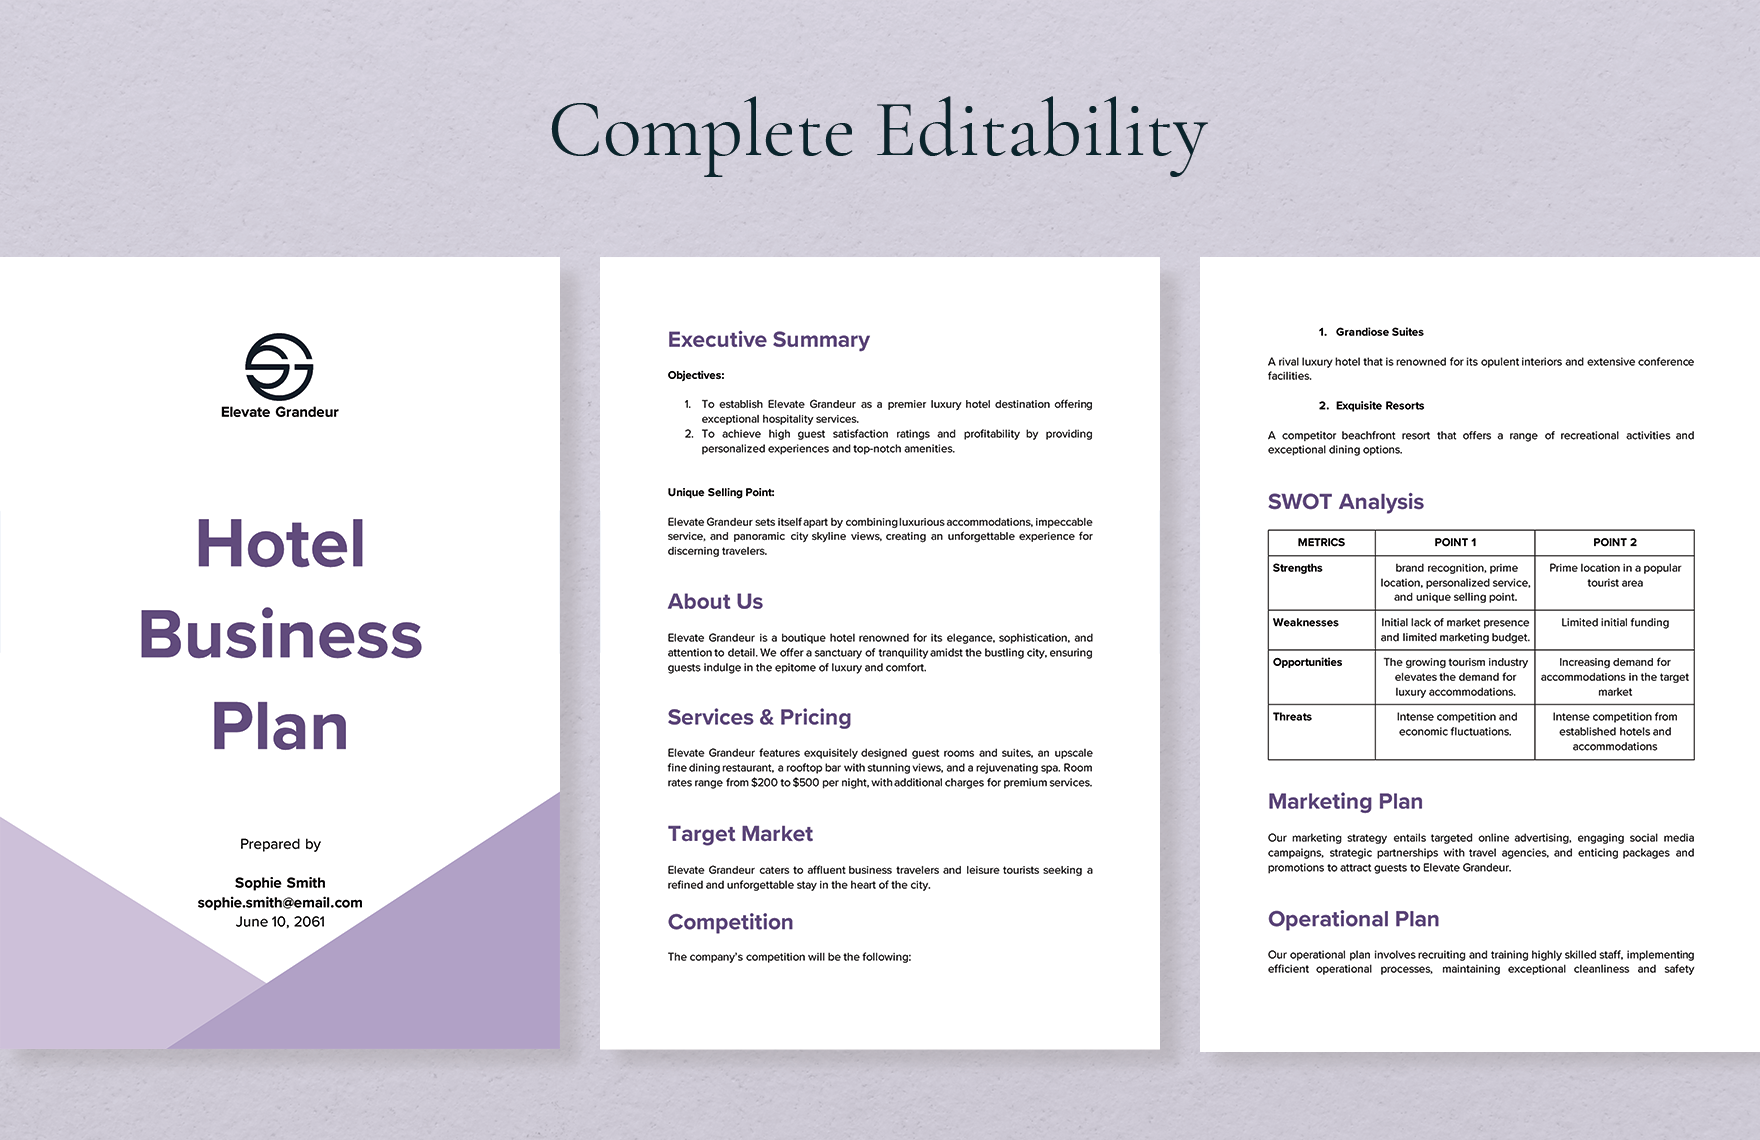
A good template gives you sections without locking you into a format that doesn't fit your property type. A bed and breakfast has completely different economics from a full-service conference hotel. The template should have standard sections executive summary, market analysis, operations plan, financial projections, risk assessment but leave the depth of each section adaptable. Most free templates online are too generic to be useful for hospitality. They'll have a revenue section with one box for "total revenue" and no breakdown by department. That's not a business plan. That's a guess with formatting. Invest time in building or acquiring a template that forces you to think through the departmental P&L, the staffing matrix, and the capital expenditure schedule separately. The capital expenditure section is something I see consistently missing. Hotels are heavy on CapEx. Roof replacements, HVAC overhauls, room renovations, parking lot resurfacing. Budget 3 to 5 percent of gross revenue annually for CapEx unless you're in a brand-new building with warranties. I once reviewed a plan with zero CapEx reserve for a property that was twelve years old. The lender flagged it as unrealistic. You should flag it too.