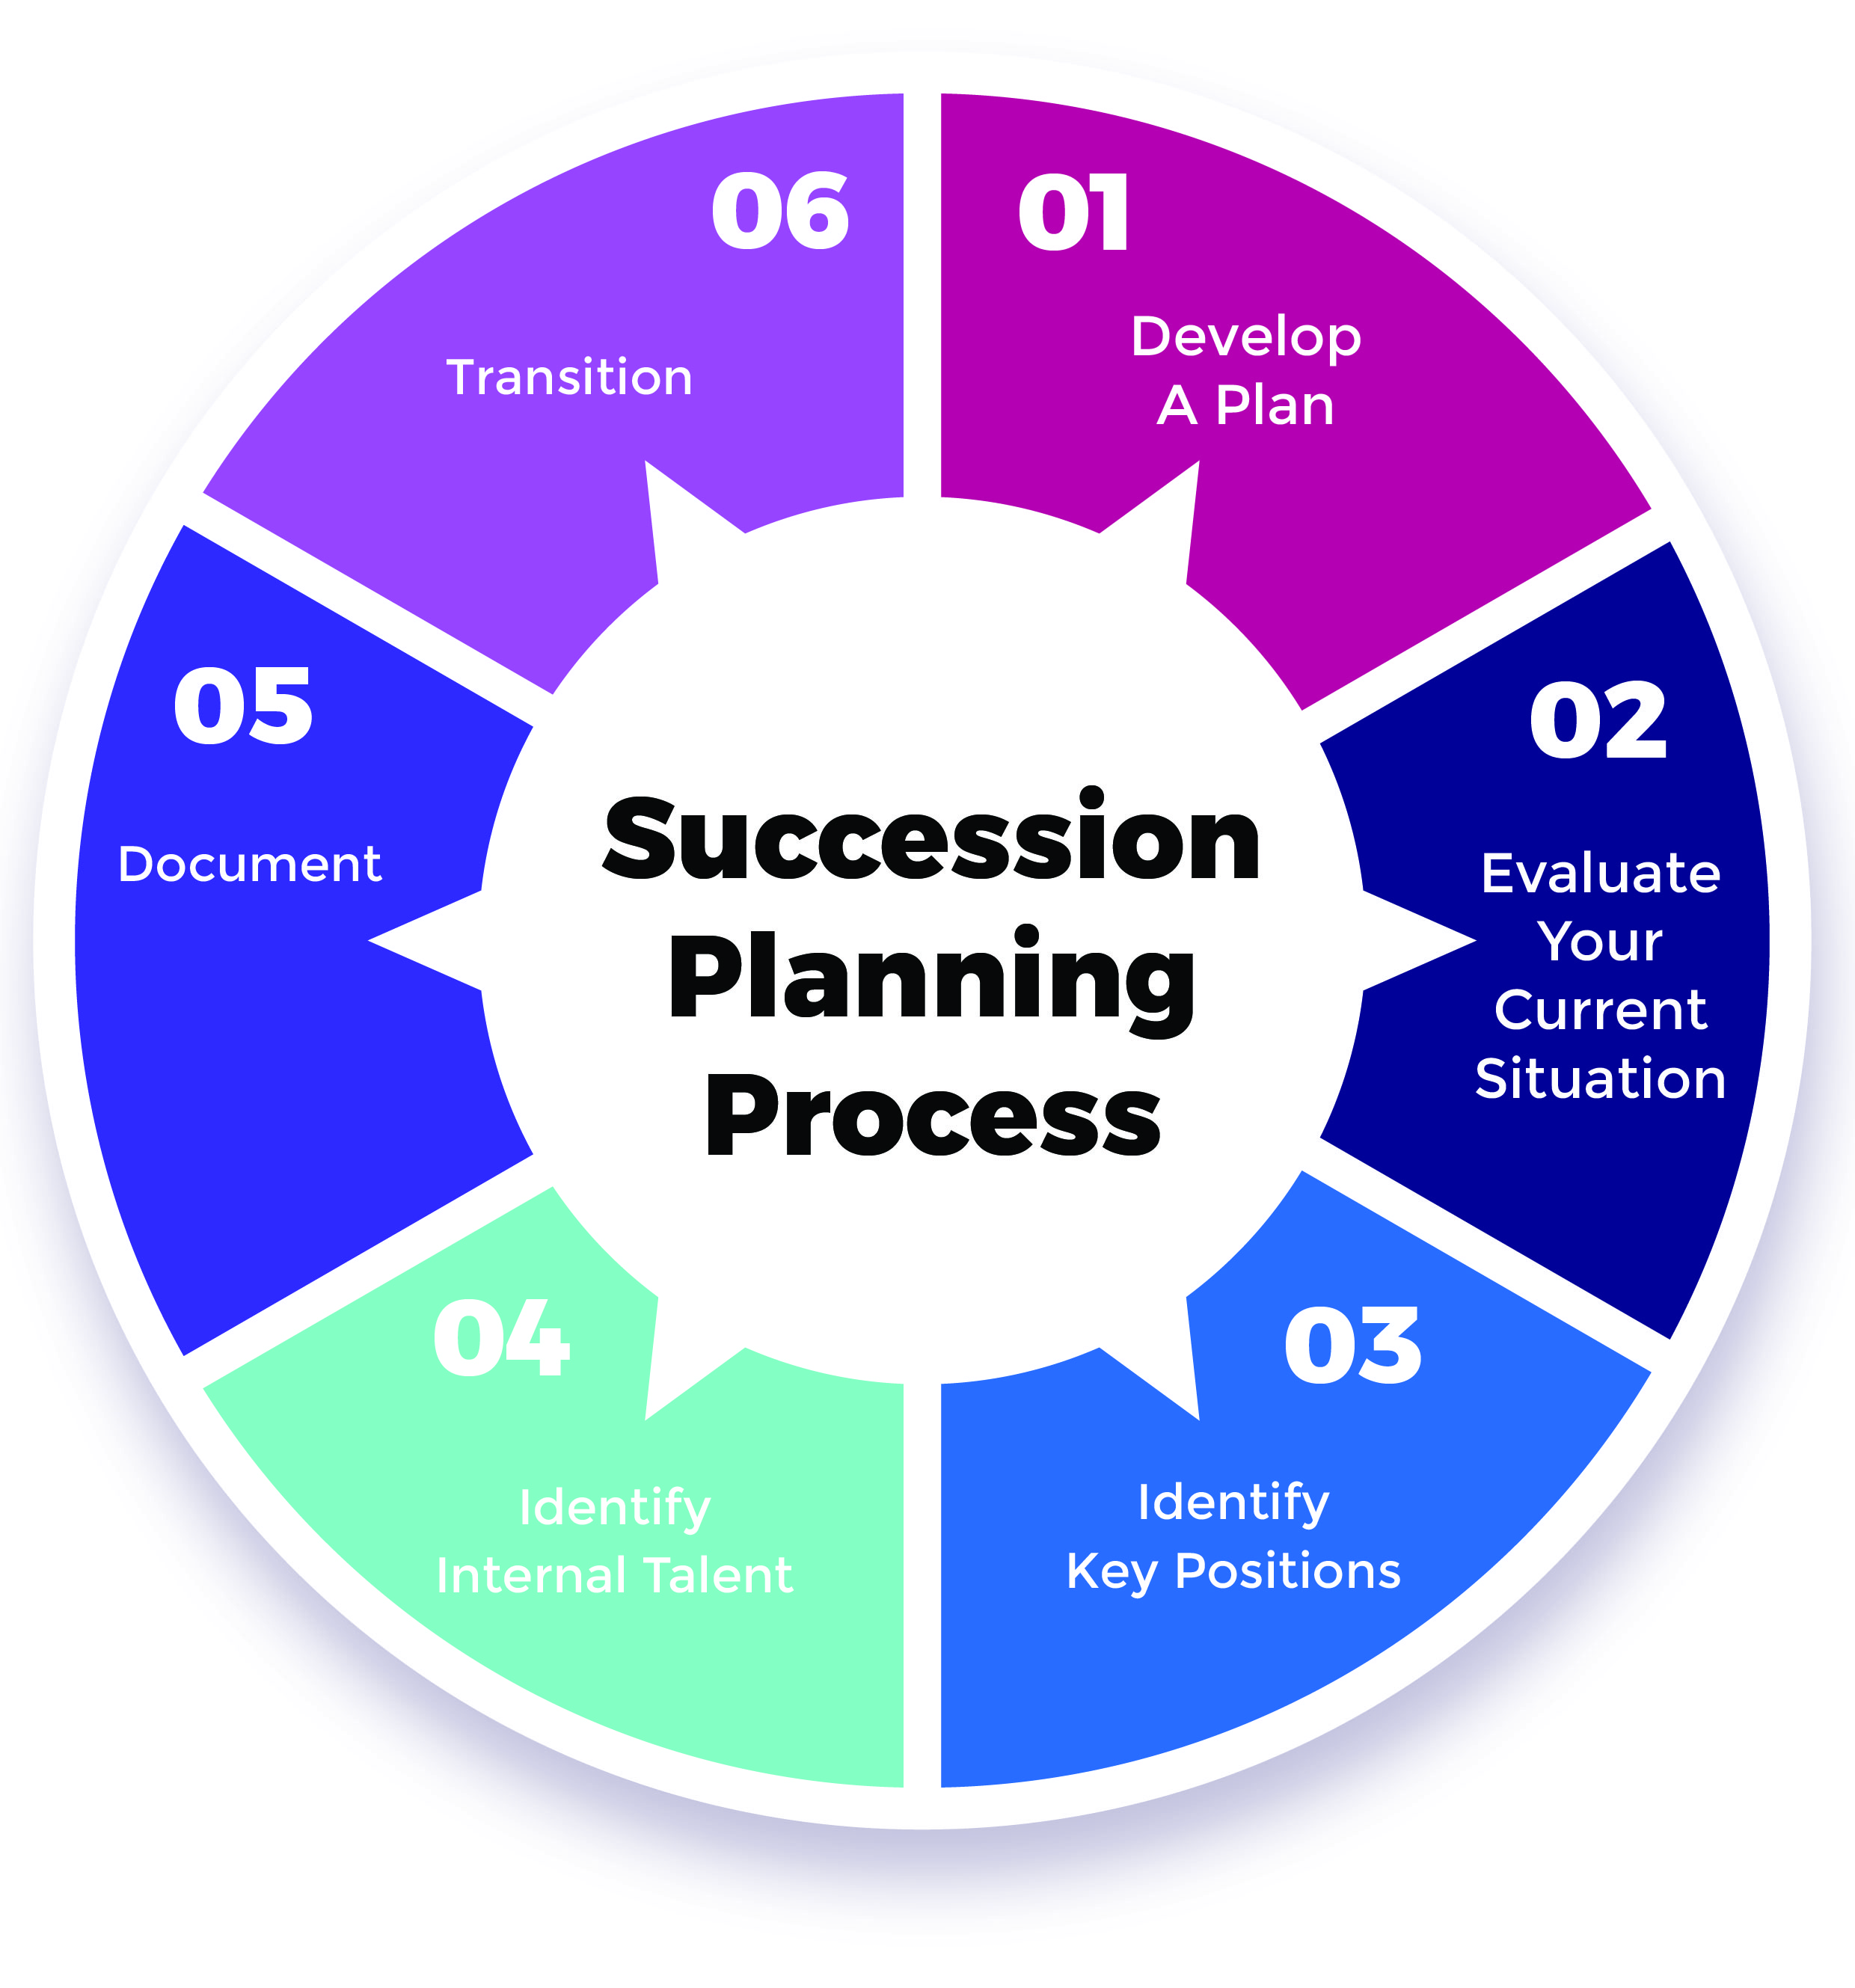
The messy reality of transferring a business before something breaks
Most people don't realize their succession plan is inadequate until they're already in crisis. I went through this with a family-owned manufacturing client whose owner suffered a sudden stroke at age 61. The "plan" was a single paragraph in a will from 2004. There was no valuation methodology, no identified successor, and the buy-sell agreement referenced the original $50,000 capital investment. The siblings fought for 14 months. Two key employees left in month six. That's why having a proper Business Succession Planning Template that actually covers the edge cases matters more than anything else in this process. A succession planning template isn't a legal document. It's a structured worksheet that forces you to make the hard decisions while you're lucid. It captures ownership transfer mechanics, valuation triggers, successor identification, funding strategies, and timeline milestones in one place. The best ones you'll find are shared as spreadsheet formats or detailed Notion templates. I maintain my own and have used it for about nine years across different industries.
Business Succession Planning Template
Here's what my working version contains and why each section exists: Section one is always the equity map. This means listing every owner, their percentage, their acquisition date, and any vesting schedules or restrictions. In my experience, people skip this and then discover mid-process that a silent partner holds 15% from a 2008 buy-in that was never documented in the operating agreement. I found this exact problem with a construction company where the general contractor's brother had a verbal side deal for 10%. The template forces you to document these relationships upfront. You need at least two methods cross-referenced. A multiple-of-EBITDA approach and a book-value floor. The trigger events are what actually matter here. Death, disability, voluntary retirement, divorce, or bankruptcy each require different valuation adjustments. I've seen templates that treat all triggers identically. That's a mistake. Death typically triggers a buy-sell funded by life insurance. Disability requires a longer payout structure because the disabled owner may still need income. One client used a flat discount schedule across all triggers and nearly lost the business when his CFO exercised a divorce provision that valued the company at book rather than fair market value.
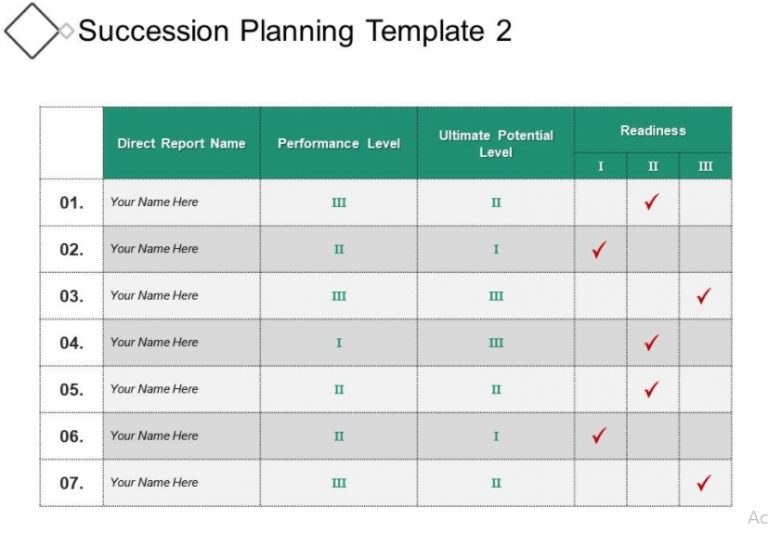
This is where most plans fail. You list potential successors, rate their readiness on a 1-10 scale, identify skill gaps, and set remediation timelines. Not just the obvious candidates. The person best suited to run the business today might not be the person who can run it in five years. I worked with a software firm where the founder's daughter was rated a 9 for cultural fit but a 3 for technical operations. The plan included a mandatory external COO hire within 18 months of transition. Without that clause in the template, she would have been promoted straight into operations with no safety net. Cash reserves, insurance policies, installment payment schedules, or third-party seller financing. Each has tax implications. An installment sale can spread capital gains over several years and reduce estate tax burden. A lump-sum buyout via life insurance is faster but creates a massive premium cost that may strain cash flow. My rule of thumb: never rely on a single funding source. I always structure at least two options into the template. The client who relied solely on an SBA loan for succession funding got denied when rates spiked to 11% in 2023. Having a backup funding track documented in the plan prevented the entire transaction from collapsing. What happens on day one after a triggering event. Who gets notified, within what timeframe, what documents change hands, and who makes the interim decisions. This section should read like an operations manual, not a legal theory exercise. I once had a real estate agency owner die suddenly. The template had a three-day notification requirement to all partners and a named interim decision-maker. It worked exactly as designed because nobody had to guess who was in charge during the first critical week.
Get the Full Details
The actual transition doesn't happen overnight. Most successful transitions span 24 to 60 months. The template should include annual review dates, preparation milestones, and soft launch checkpoints where the successor takes operational control incrementally. A phased approach reduces the shock to employees, clients, and vendors. I track this in a simple Gantt-style grid. The milestone columns are: key hire in place, client introductions complete, vendor contract transfer, and full operational handover. Each column gets a target date and an owner responsible. The single biggest pitfall I encounter is treating the template as a static document. I see people fill it out once and file it away. That's wrong. The template should be reviewed and updated at minimum every 12 months. Every major business event — a new partner, a significant acquisition, a product line launch — requires an immediate update. A template that hasn't been touched in three years is worse than useless. It creates false confidence. Another problem is overcomplicating the valuation section. You don't need a CPA-level appraisal methodology inside the template. You need a clear, agreed-upon formula that all parties signed off on years before any dispute arises. Something as simple as "three times trailing EBITDA, with a 10% discount for lack of marketability" is far more defensible in practice than a 20-page valuation annex nobody understands. I once watched two brothers spend 40 hours debating fair value methodology for their trucking company. They never finished the template. They eventually sold to a third party for roughly what my simplified formula would have produced, minus the legal fees and the relationship damage.
The template should also address what happens when there is no viable successor. This is the part most people avoid. I include a forced sale clause with a predefined buyer identification process. Sell to a key employee via ESOP, sell to a competitor, or liquidate and distribute proceeds. Not having an exit path when succession fails is how family businesses get torn apart. One client's template specified that if no internal successor was ready within five years, the business would be listed for sale through a broker pre-approved in the document. That broker relationship was established during the planning phase. It saved three weeks of panic during an actual triggering event. For people who want to start, I'd suggest building from scratch rather than downloading a generic PDF. Generic templates miss the funding and trigger specifics that matter. A Google Sheet or Excel workbook with the sections I described above, populated with your actual numbers, is more useful than any templated document you'll find online. I keep mine accessible to all ownership parties. Transparency prevents disputes far more effectively than any legal language in the document itself. The version I maintain runs about 12 pages when fully populated. It covers ownership mapping, valuation with dual methodologies, successor assessment with gap analysis, funding scenarios, trigger protocols, and a timeline tracker. I update it quarterly and share the current version with all parties involved. This isn't a perfect system. It requires honest self-assessment, which is uncomfortable. Some owners resist filling in the successor section because it forces them to acknowledge their own limitations. Others skip the funding scenario analysis because they'd rather not think about death or disability. But skipping those sections is exactly what turns a manageable transition into a disaster.