Getting a Business Term Sheet Template Right
A term sheet is just a non-binding outline of the key terms for a potential deal. That's it. Most people treat it like it's more important than it is, or less important than it should be, depending on which side of the table they're sitting on. I've seen founders sign off on term sheets that looked fine until the 50-page definitive agreements came back with completely different mechanics on vesting and liquidation waterfalls. The mismatch costs everyone time and money. A solid Business Term Sheet Template saves you from that headache, but only if you actually use the right structure.
What You Need in a Business Term Sheet Template
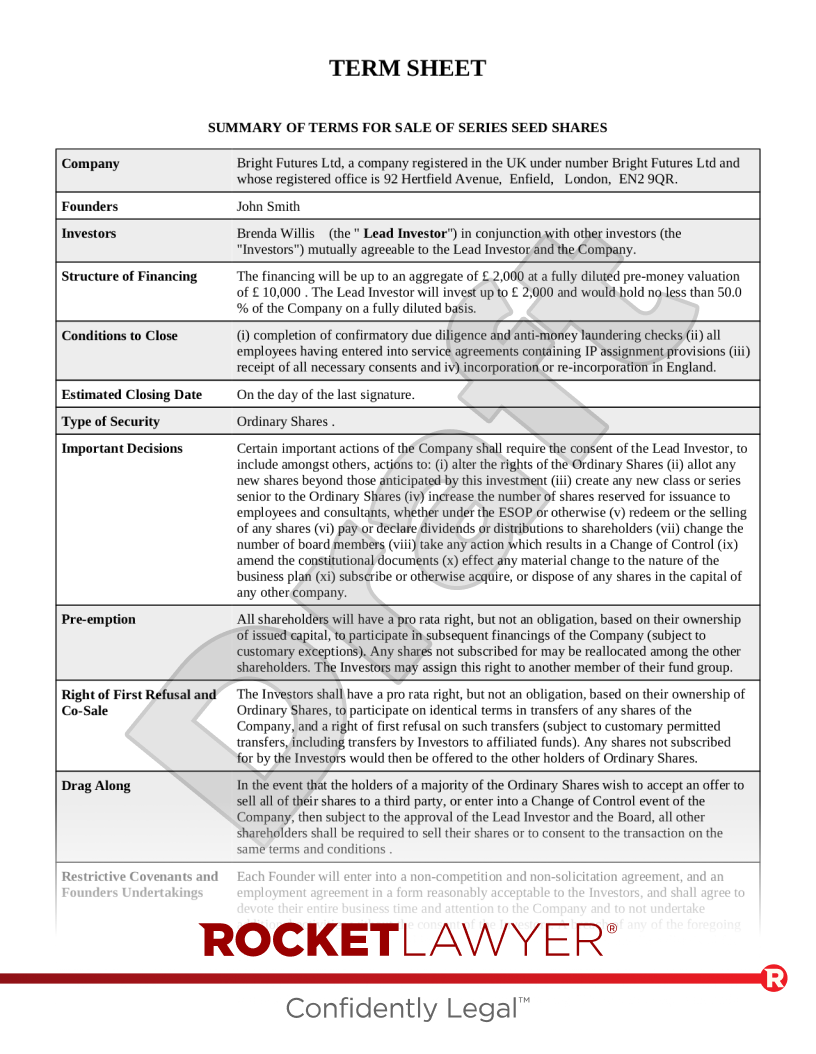
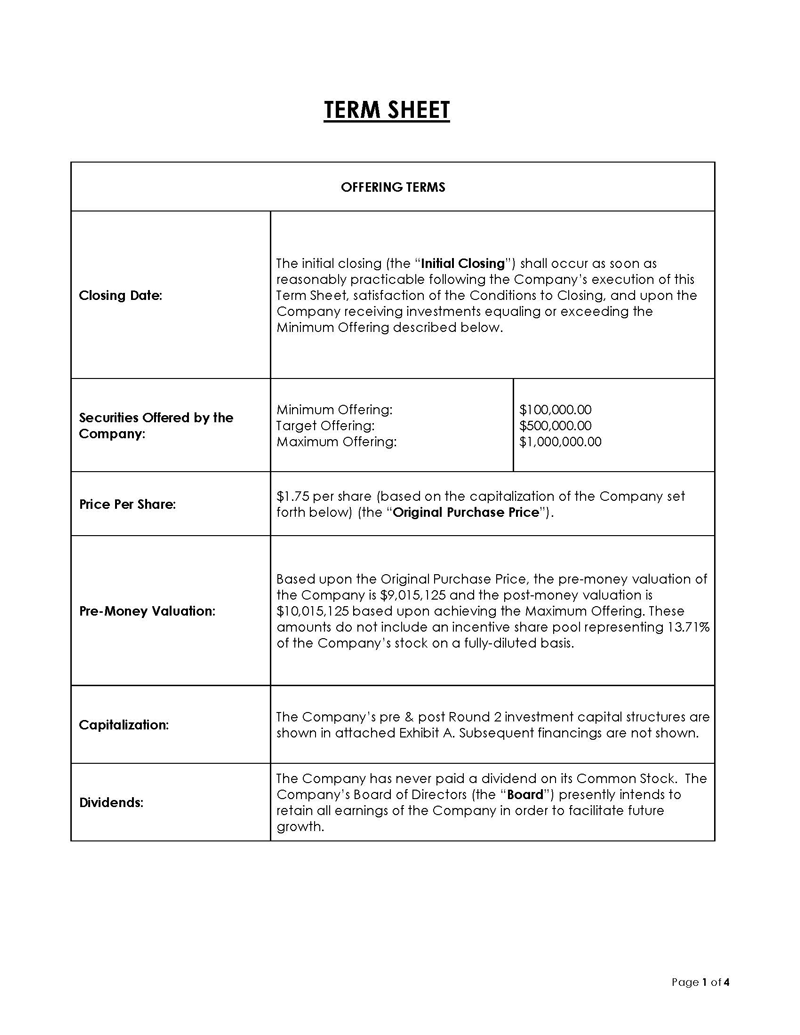
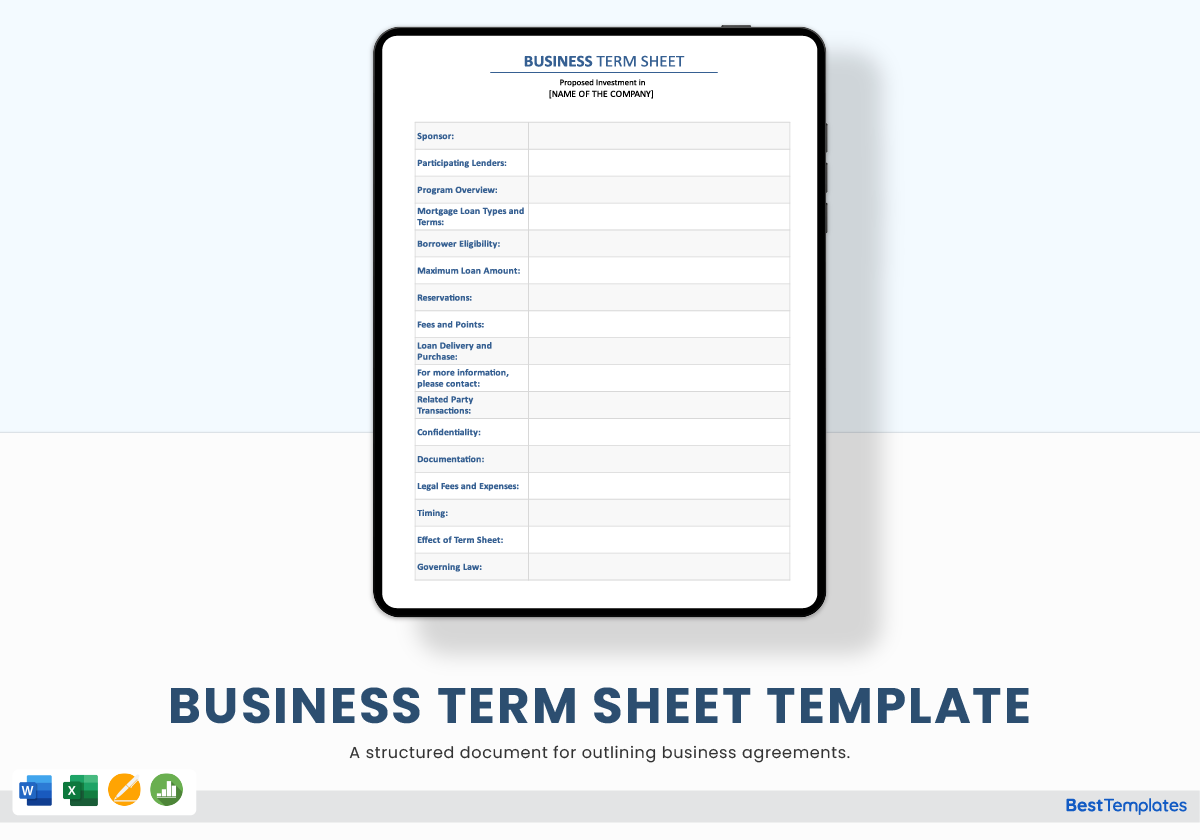
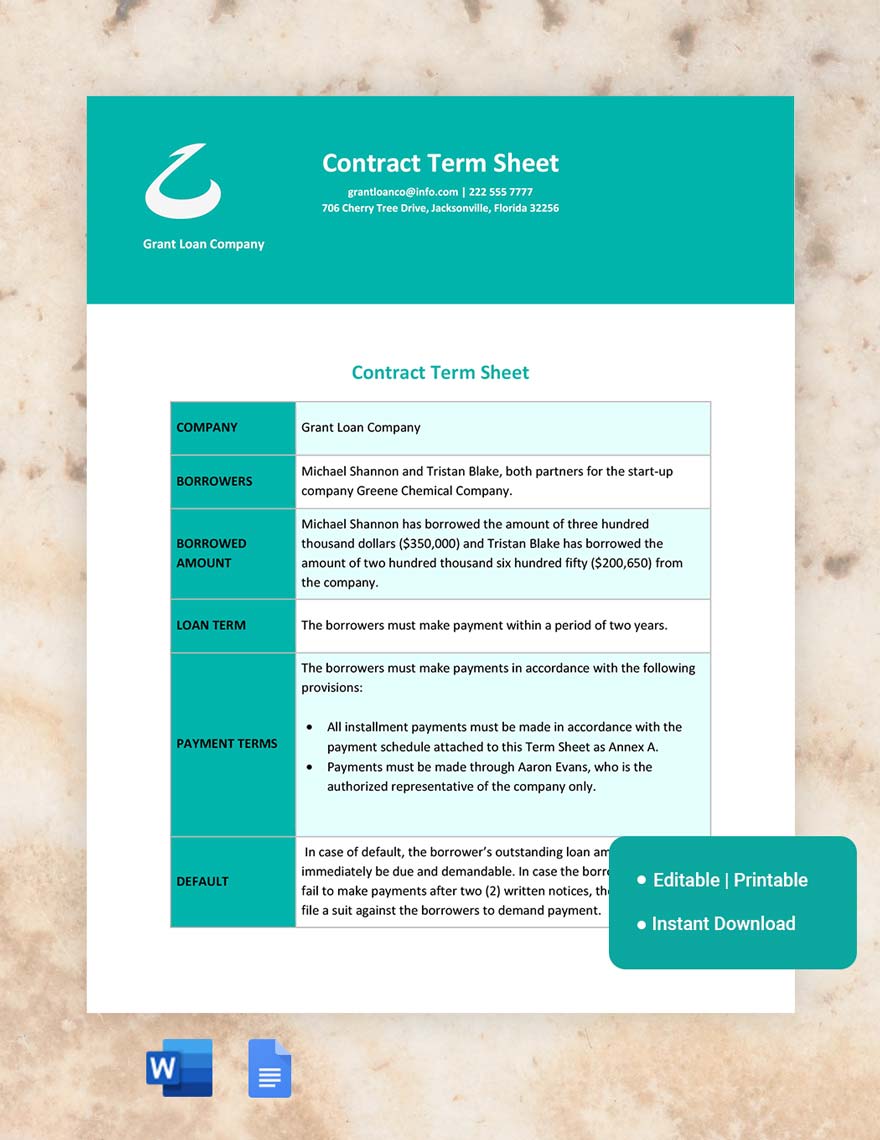
Start with the basics. Every term sheet should cover valuation, equity allocation, voting rights, board composition, and liquidation preferences. Those five items alone will determine whether anyone actually gets paid back if the company exits early. Here's what a working template looks like in practice: Parties: Identify the company and the investors clearly. Include entity names and addresses. I learned this the hard way when we had an investor who turned out to be a blind trust operating out of Delaware, and it took three weeks to figure out who was actually signing.
Valuation: State whether it's pre-money or post-money. This matters more than you think. A $5 million pre-money on a $1 million investment gives the investor 16.7% ownership. Post-money changes that to 16.7% the other way around. Get this wrong once and your cap table looks like nonsense forever after. Equity Allocation: Show the exact percentage or number of shares each party receives. Be specific. Vague language here is how happens. Board Composition: Define who sits on the board and how many seats each side controls. Investors want seats. Founders want to keep control. The compromise is usually a five-person board: two founders, two investors, one independent.
Get the Full Details
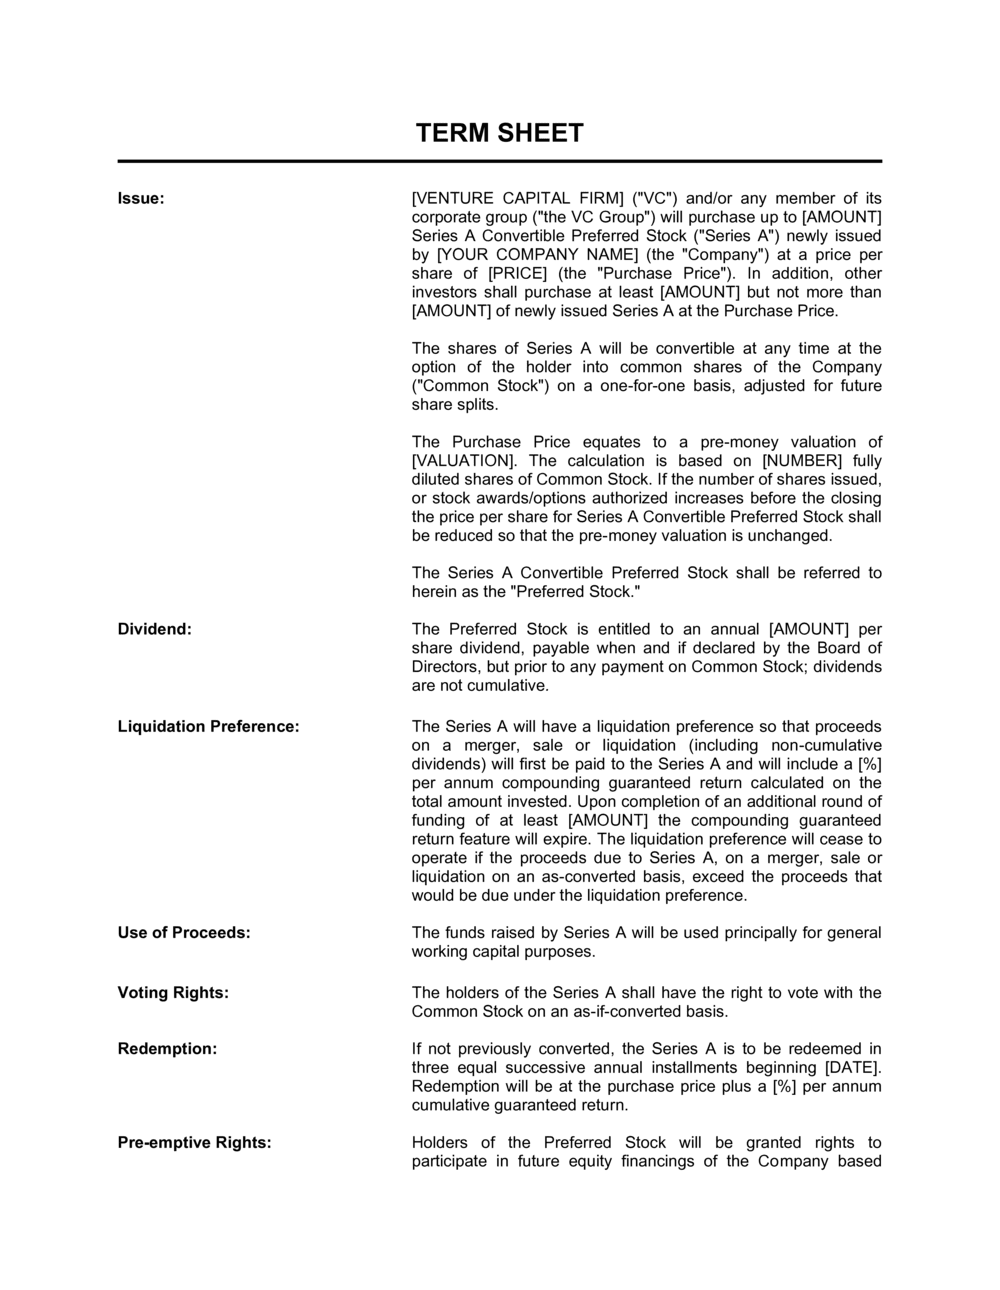
Liquidation Preferences: This is where most term sheets go sideways. The standard is a 1x non-participating preference. Some investors ask for 2x or participating preferences. Don't accept those without understanding the math. A participating 1x preference means the investor gets their money back AND a share of the remaining proceeds. That's double-dipping and it's brutal on founder economics.
How to Actually Use This Template
Fill it out early in negotiations, before you draft the full agreements. It should take 20 to 45 minutes for a straightforward deal. If it takes longer, you haven't got clarity on what you're actually trying to agree to yet. Once both sides initial it, hand it to your lawyer. The lawyer then turns it into the actual binding documents. The term sheet isn't legally binding (except for confidentiality and exclusivity clauses, usually). But the binding docs have to match it, so getting the sheet right matters a lot. I once had a situation where the term sheet said "standard liquidation preference" and the lawyer filled in a 2x participating preference because that's what was common in their practice. The founder didn't catch it until the SPA was 30 pages in. We had to renegotiate the whole thing. Lesson: don't leave anything vague. Write "1x non-participating" explicitly, not "standard."
Common Pitfalls and Counter-Intuitive Truths
Here are a few things that aren't obvious unless you've seen a bunch of deals fall apart: Anti-dilution provisions are more dangerous than most founders realize. A full ratchet anti-dilution can wipe out founder equity completely in a down round. Weighted average is the safer middle ground, but even that has different flavors. Broad-based weighted average is what you want. Narrow-based favors the investor and gets you a bigger correction. Drag-along rights sound harmless but can force you out. If the majority owners can force a sale and you disagree, you have to go along. This is standard in later-stage deals, but early-stage founders often sign drag-alongs too aggressively. Cap the drag-along at a supermajority or require founder consent for anything below a certain price threshold.
Vesting schedules aren't just for founders. If you're bringing on early employees with equity, vest them too. I've seen co-founders walk away after six months with full ownership because no one thought to write in a vesting schedule. That's a dead company problem. Redemption rights are a sleeping bag of sharks. Some term sheets include investor redemption rights, meaning the investor can force the company to buy back their shares after a certain period. This is extremely rare in venture deals and a huge red flag if you see it. Walk away or negotiate it out.
Limitations You Need to Know
A Business Term Sheet Template is only as good as the terms you put into it. It doesn't protect you from bad actors. It doesn't handle complex capital structures with multiple classes of shares. It won't save you from an investor who reads the fine print differently than you do. The template also assumes you're doing a straightforward equity investment. Convertible notes, SAFE notes, and revenue-based financing follow different frameworks entirely. If you're raising on a SAFE, you don't need this template. You need a SAFE form, usually from YC or similar. Don't overcomplicate it. Another limitation: term sheets work best when both sides are reasonably aligned on economics. If the investor wants 40% and you think 10% is fair, no template is going to bridge that gap. You'll just spend weeks circling the same numbers.
Where to Find a Working Template
You can build your own from scratch using the structure above, or pull one from resources like the Securities and Exchange Commission's small business guides, or legal tech platforms like Clerky or Stripe Atlas. If you go the DIY route, make sure someone with deal experience reviews it before you send it out. The template itself is free. Getting it right without professional input is where the cost shows up later. If you're in a jurisdiction outside the US, note that term sheet conventions differ significantly. European deals often use different voting structures. Asian deals sometimes include performance milestones tied to equity release. A US-centric template won't cover those cases.
Bottom line: a Business Term Sheet Template is a tool, not a solution. Use it seriously, fill it in carefully, and don't treat it like a formality before the real negotiation begins. The real negotiation is in the wording.