How The Home Buying Process Actually Unfolds
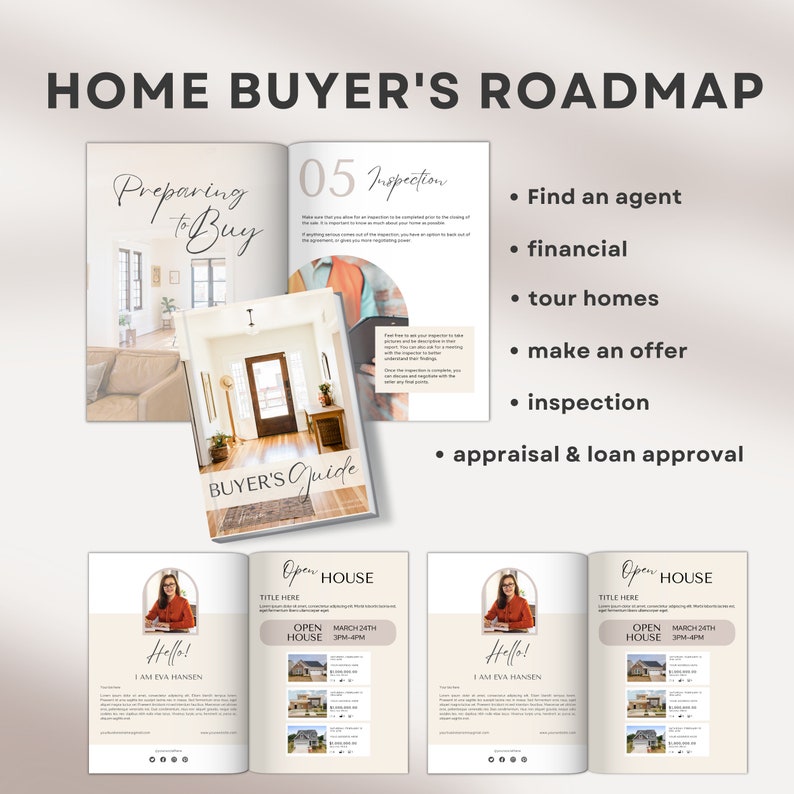
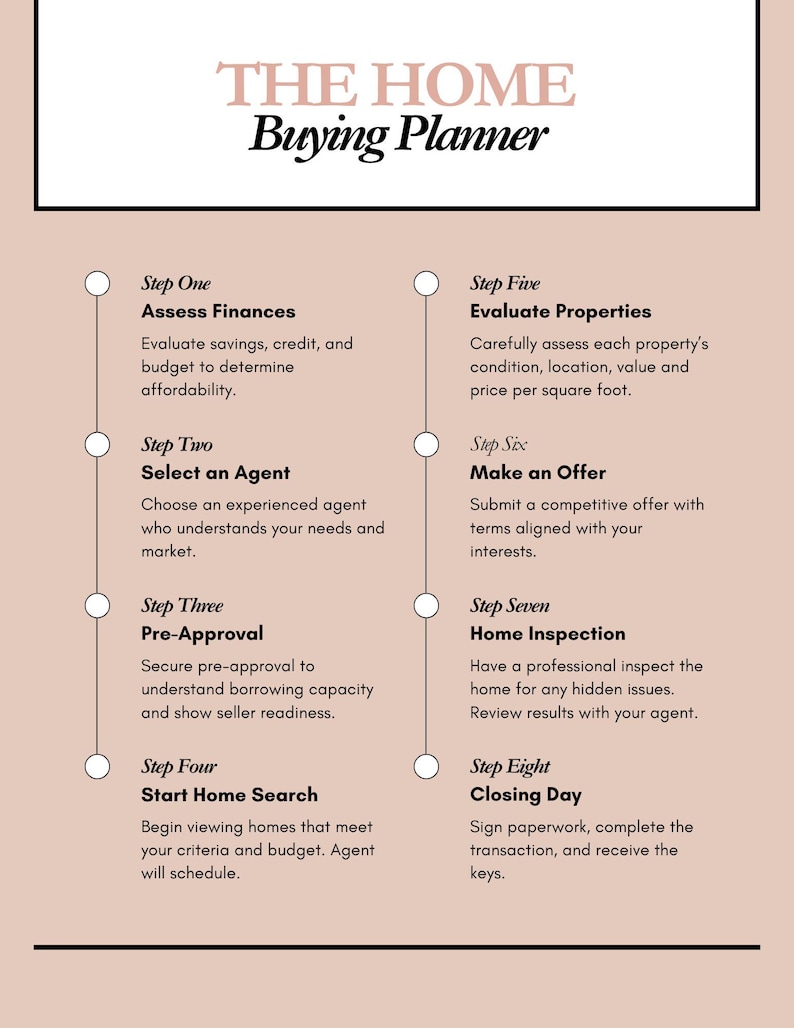
A lot of people approach buying a house backwards. They start scrolling Zillow listings and thinking about closing dates before they understand what they can actually afford. A solid Buyer Guide For Real Estate Step By Step exists to help you avoid that particular mistake, though even with a clear guide in hand, the process has its own quirks that no document fully prepares you for. The fundamental order of operations matters more than most buyers realize. Here is how the process plays out in practice, not in theory.
Get Your Financials In Order Before You Look At Anything
This is where most people lose months. You need a clear picture of your borrowing capacity before you fall in love with a property. Get a formal pre-approval from a lender, not just a pre-qualification letter that a website generates with no verification. Pre-qualification means nothing in a competitive market. A pre-approval letter that includes verified income, assets, and credit review is what sellers care about. I learned this the hard way during a transaction in 2019. The buyer had a pre-approval letter from a big national bank. We got the house under contract in a seller's market. Their loan officer never actually pulled the credit or verified the employment. When the underwriter pulled the full file, the application fell apart. The deal closed two months late and the seller walked away. That pre-approval was worthless paper. The workaround is simple but most people skip it: pick your lender before you even start looking. Call them, give them your documents, and get the pre-approval in writing. Then use that same lender throughout the entire process instead of shopping around mid-deal, which delays everything significantly.
Key Steps In A Typical Purchase
Once your finances are in shape, the actual house hunting begins. But the steps that follow are where a buyer guide matters most, because the sequence itself protects you from costly mistakes. Not all real estate agents represent buyers. Some agents exclusively work with sellers. If you hire someone who has a conflict of interest, you are already at a disadvantage. Look for a designated buyer's agent who understands the local market inside out. Interview at least three. Ask them how many transactions they closed in the past year in the price range you are targeting. Most agents will say they do residential sales, but that covers everything from starter homes to luxury estates, and those are very different skill sets. There is a reason to view houses with a structured approach rather than going on wild open house tours. The standard guidance is to view at least ten to fifteen homes in your target price range before you feel confident about what a fair price looks like. Without that baseline, you will either overpay or second-guess every listing. I keep a simple spreadsheet now with five columns: address, list price, price per square foot, days on market, and a rough condition score. After viewing ten homes in a neighborhood, the pattern becomes obvious. You can spot an overpriced listing immediately.
Get the Full Details
Making an offer feels like the exciting part, but this is where the actual risk enters the picture. Your offer includes contingencies, and understanding what each one does will save you more money than anything else in a Buyer Guide For Real Estate Step By Step. The inspection contingency is non-negotiable. There is almost no scenario where waiving it makes sense unless you are an experienced contractor or planning to gut and rebuild the house anyway. A standard home inspection runs about two hours and costs between three hundred and six hundred dollars. It uncovers issues that a layperson will never see. Foundation cracks, outdated electrical, roof wear, plumbing problems. These items can range from a few hundred dollars to fix to thirty thousand or more. Here is something most buyer guides do not emphasize enough: the inspection contingency is not just about getting repairs done. It is about renegotiation leverage. When an inspector finds a problem, you can ask for a credit, ask for a repair, or walk away entirely depending on how badly the house meets your needs. Use that leverage deliberately instead of panicking and accepting whatever the seller throws back.
The Appraisal Gap Problem
In markets where prices are rising fast, the appraisal comes back lower than your offer price. This is called an appraisal gap. If your offer is four hundred thousand dollars and the appraised value comes in at three hundred eighty-five thousand, your lender will only finance three hundred eighty-five thousand. You are responsible for the difference. Many buyers sign contracts without understanding this risk and then have to bring extra cash to closing or lose their deposit when they cannot cover the gap. The practical solution is to ask your agent to pull comparable sales data before you write the offer. If the comps support a price near your offer, you are safer. If the comps are lower, adjust your offer or include an appraisal gap clause that limits your exposure to a specific dollar amount instead of leaving it open-ended.
Closing And Beyond
Closing involves final walkthrough, signing a mountain of paperwork, and paying closing costs that typically range from two to five percent of the purchase price. I have seen buyers who budgeted for the down payment alone and were caught completely flat-footed when they showed up to closing with thousands short. Closing cost estimates should be requested from your lender at least ten days before closing so there are no surprises. One last detail that nobody discusses but matters enormously: title insurance. Lender's title insurance covers the bank. Owner's title insurance covers you. The cost is a one-time premium, usually around half a percent of the purchase price. I once worked on a transaction where a buyer skipped the owner's policy to save a couple thousand dollars. Six months later, a previous owner's unresolved lien surfaced. The lender's policy did not protect the buyer. The legal fees to clear the title ran well past what the owner's policy would have cost upfront. A Buyer Guide For Real Estate Step By Step will walk you through these stages, but no guide can replicate the judgment calls you make along the way. The best guides give you a framework. The actual decisions depend on your finances, your timeline, and how honest you are willing to be with yourself about what you can afford and what you actually need versus what you want.