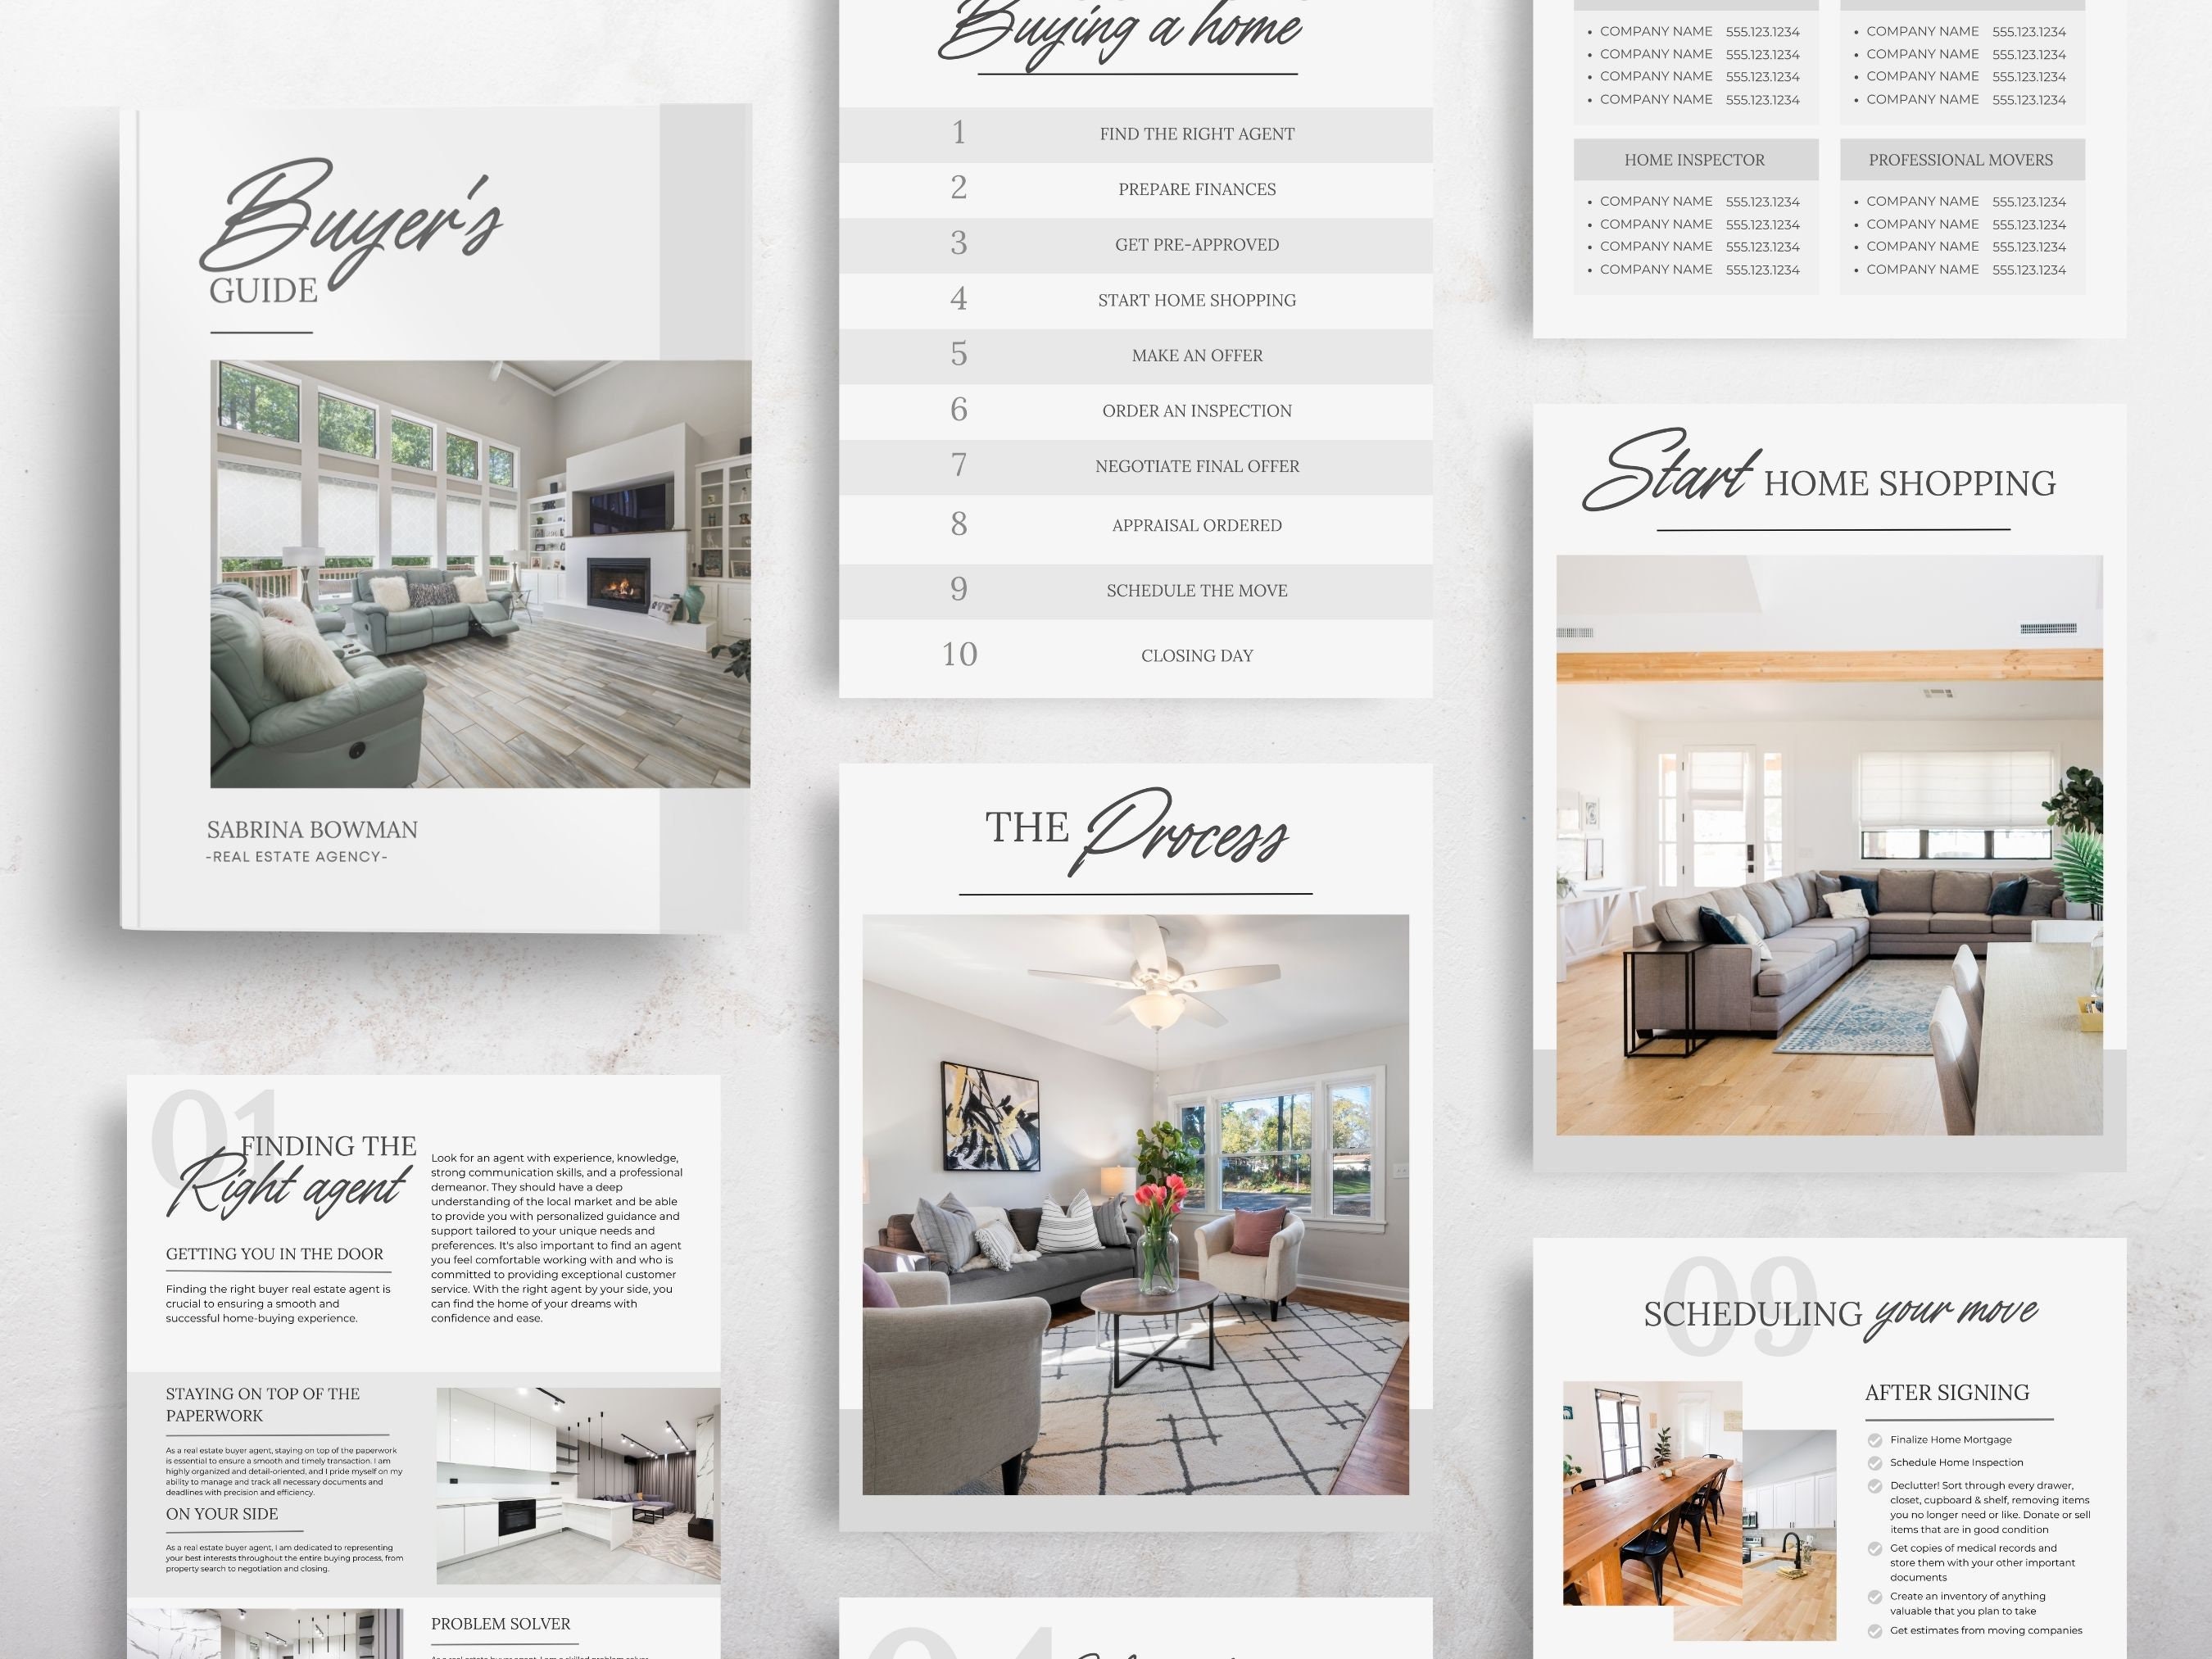
Real estate buying has gotten more complicated since 2020, and most first-time buyers walk into their first transaction completely unprepared.
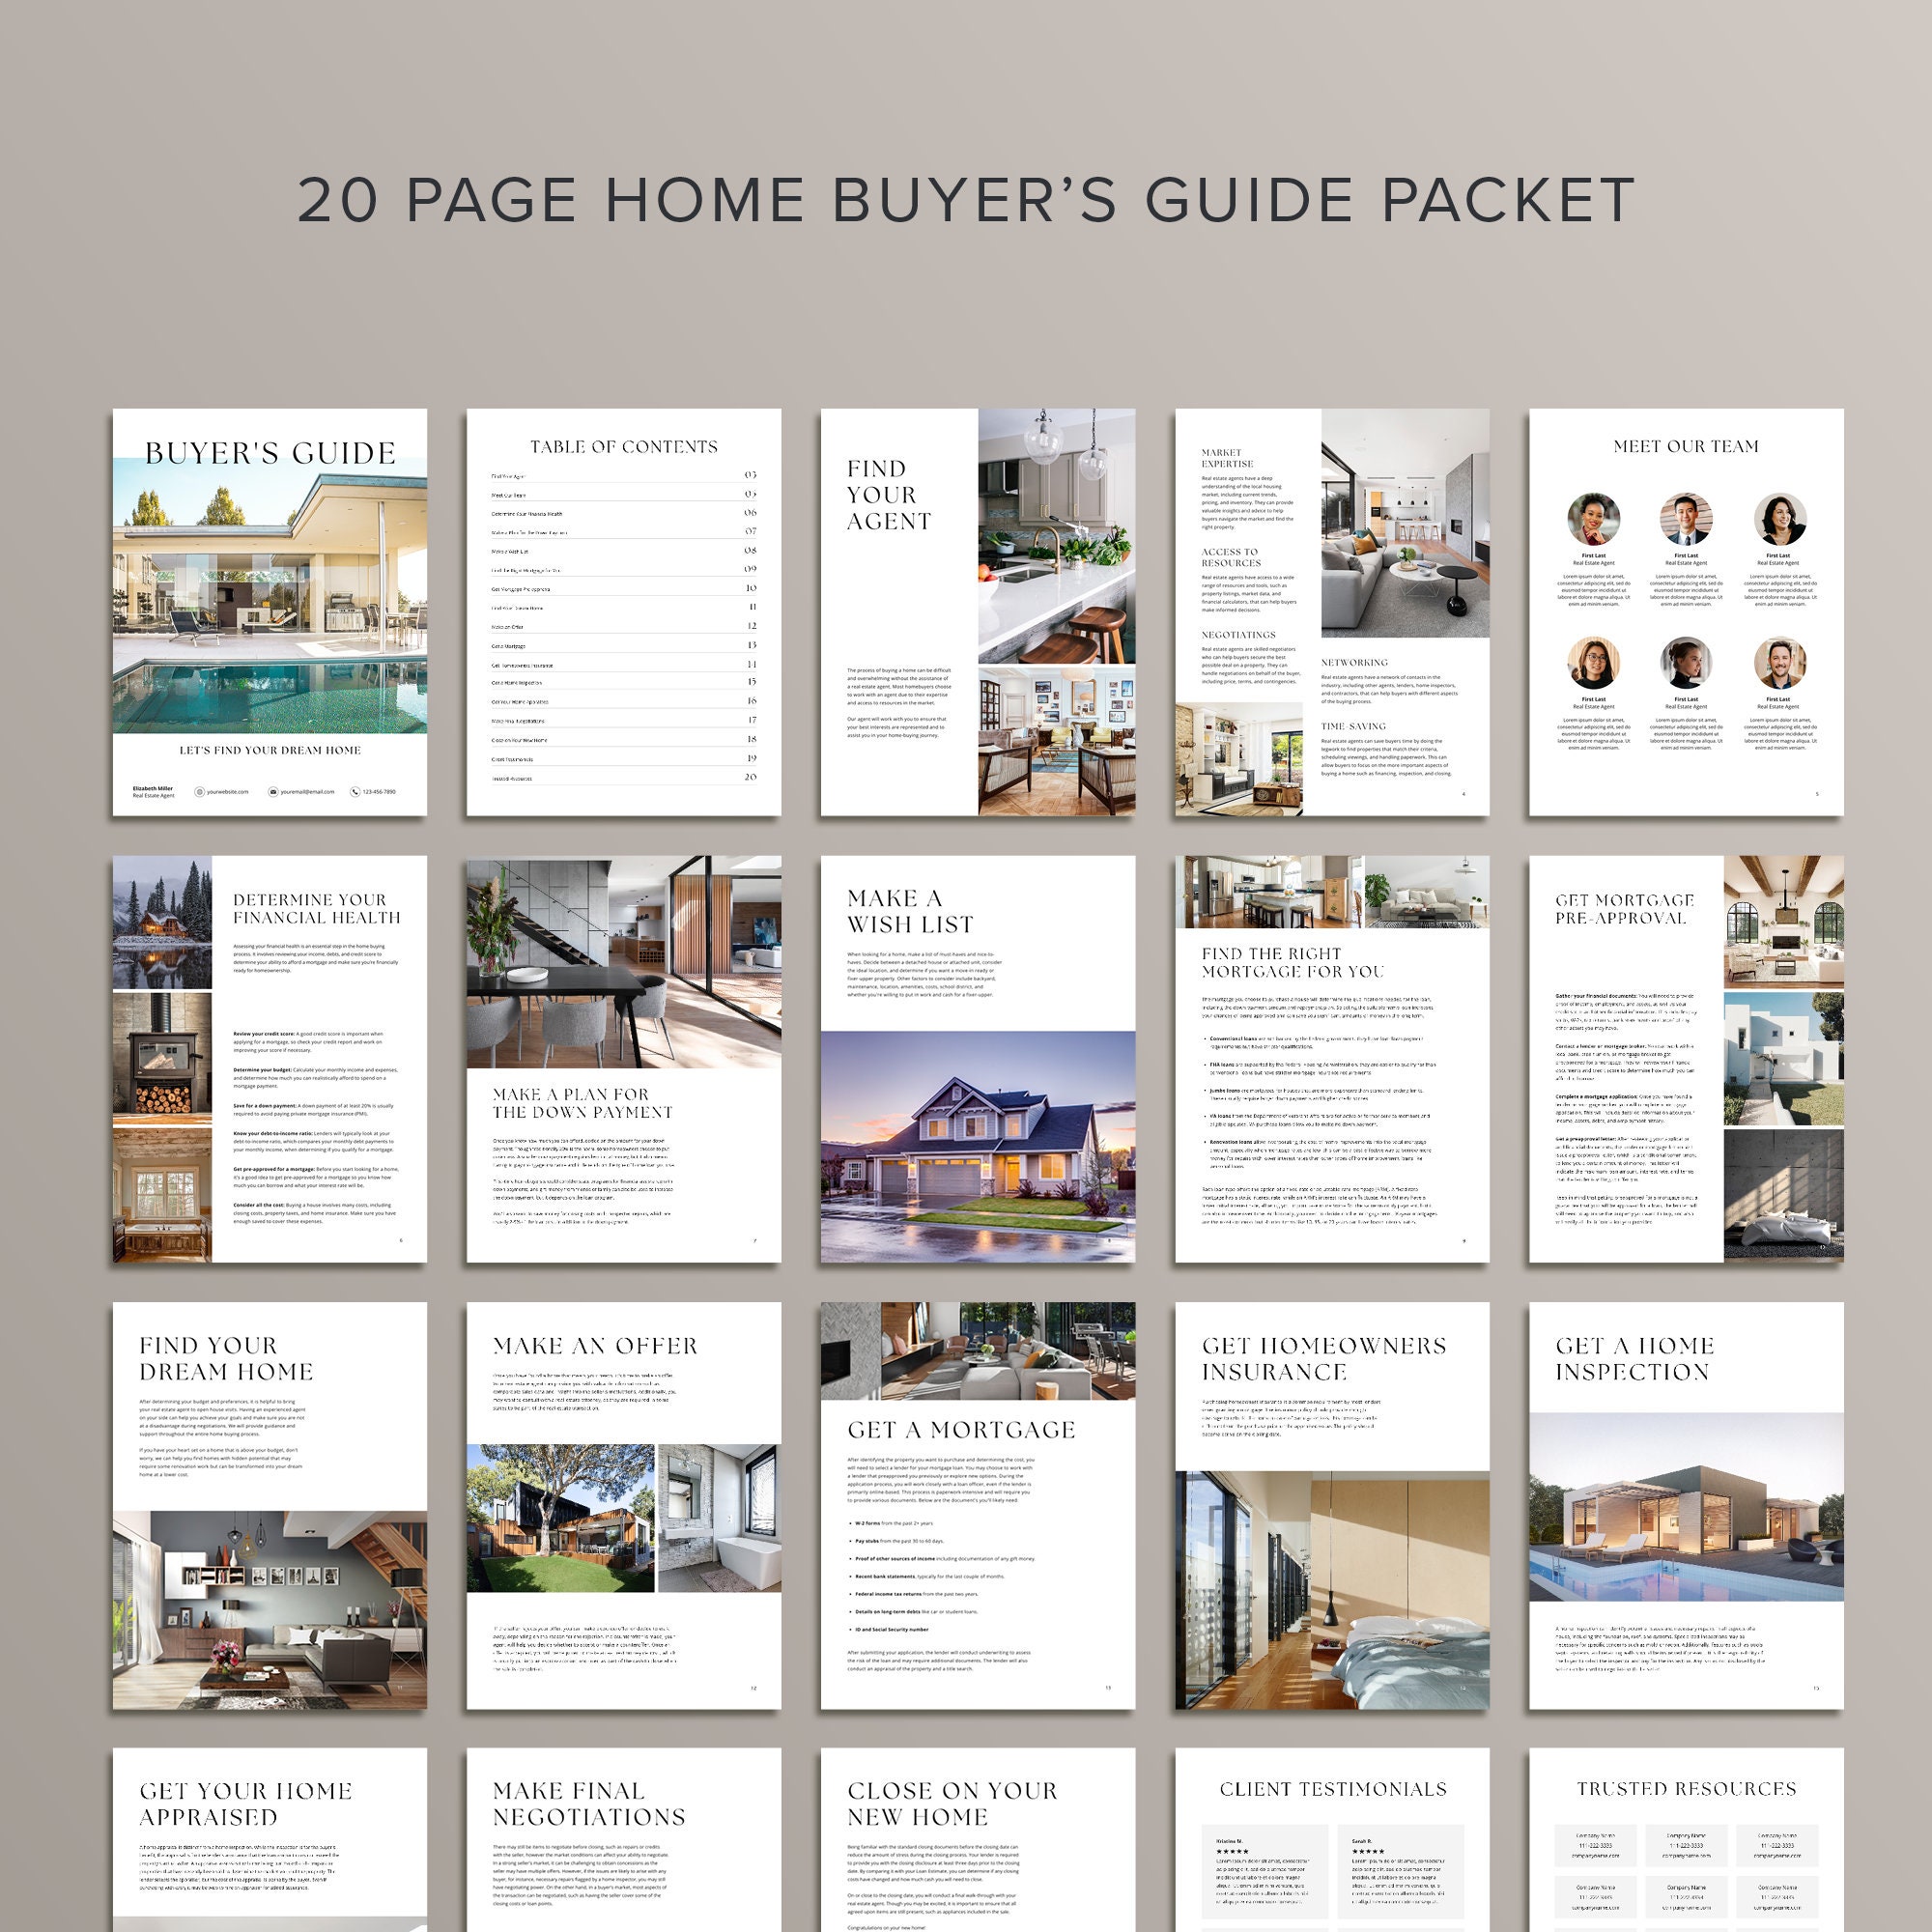
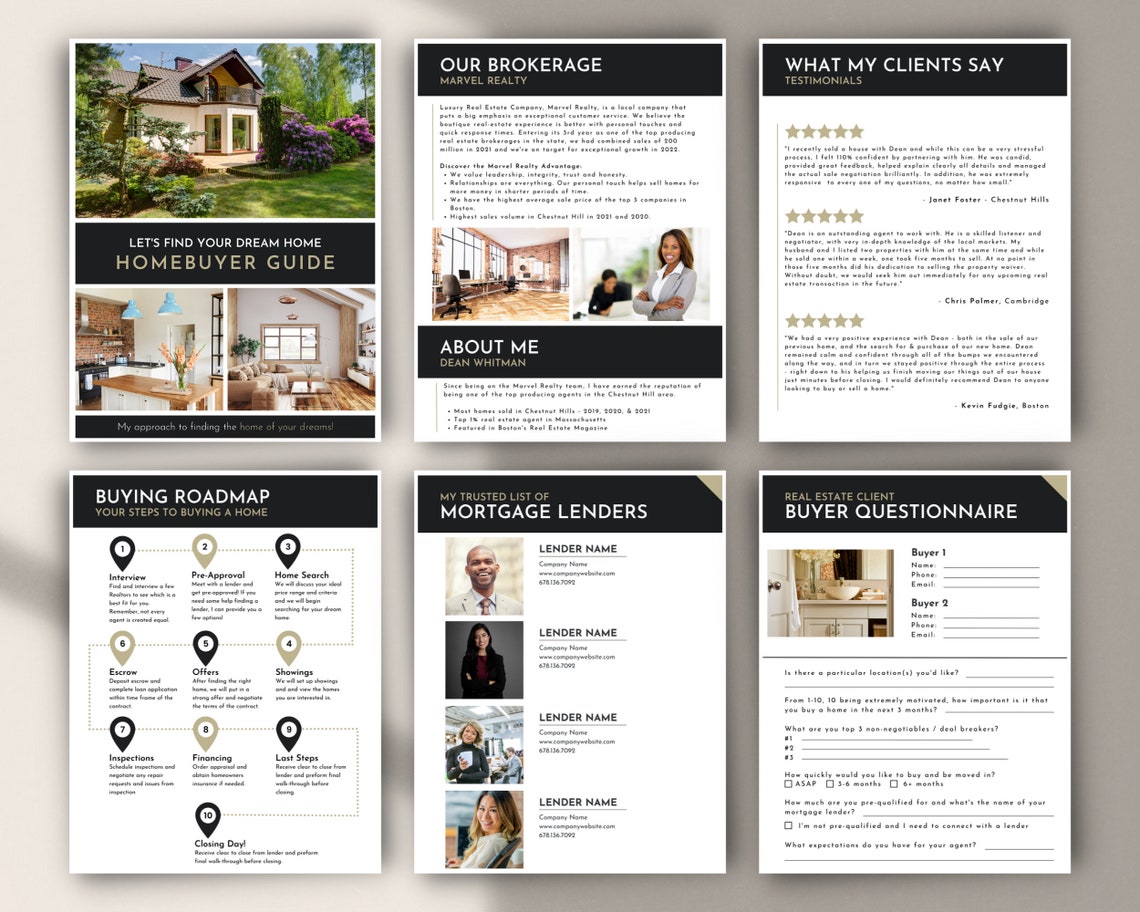
I'm going to lay out how this actually works in practice, not the sanitized version you see in magazine spreads. The process is a sequence of decisions that each have real financial consequences, and most of the damage buyers do comes from skipping steps or trusting the wrong people at the wrong times. A buyer guide in real estate is a structured walkthrough of the purchasing process from the moment you start thinking about buying to the day you hand over the keys. It covers financing, property evaluation, negotiations, inspections, closing, and post-purchase obligations. Most guides are written by agents who want you to sign with them quickly, so you need to cross-reference everything with independent sources before acting on any advice you read. The core components break down into four phases: preparation, search, offer and due diligence, and closing. Preparation is where most buyers fail before they even look at a single property. They haven't spoken to a lender, they don't know their actual budget beyond a rough estimate, and they've looked at Zillow listings until they're numb. This phase alone should take three to six weeks. You need a pre-approval letter, not a pre-qualification. There's a difference that matters enormously when you're making an offer in a competitive market. A pre-approval means a lender has verified your income, assets, credit, and debt-to-income ratio. A pre-qualification is a casual conversation that carries almost no weight with sellers or listing agents.
I learned this the hard way in 2021. I was helping a client buy a condo in Austin and she had a pre-qualification letter from a credit union she'd visited once. The seller's agent rejected the offer outright because they were reviewing multiple bids and hers looked weak on paper. We restructured her financing through a mortgage broker who pulled her full documentation and issued a pre-approval within 48 hours. The seller accepted our second offer at full list price. That pre-qualification vs. pre-approval distinction cost her two months and a $25,000 increase in the median price for the neighborhood she wanted.
The Search Phase: How to Actually Find a Property
Listing platforms show you what the sellers and agents want you to see. Every home on Zillow, Redfin, or Realtor.com is presented at its best angle with edited photos and carefully chosen descriptions. Your job is to read between the lines. Look for listings that have been on the market past 30 days with price reductions. Those properties often have real issues the seller is trying to move past. Look for listings with phrases like "handyman special," "motivated seller," or "as-is sale." These are opportunities if you know what you're doing, and they're disasters if you don't. You also need to understand the local market dynamics before you start driving around neighborhoods. In a seller's market with low inventory, you might receive multiple offers within 48 hours of listing. In a buyer's market with high absorption rates, properties sit for months. Check the days-on-market statistics for the specific neighborhoods you're interested in. The MLS data from your county recorder's office or a real estate data service like Attom or CoreLogic will give you this. It costs about $50 to $150 per report, and it will save you from making emotional decisions based on incomplete information. One thing almost no beginner guide mentions: the HOA financials. If you're buying a condo or a home in a planned community, request the last three years of HOA meeting minutes and the reserve study. I once worked with a buyer who fell in love with a townhouse in Colorado Springs. The monthly HOA fee was reasonable at $180. What the seller didn't disclose was that the board had approved a $42,000 special assessment for roof replacement on the entire complex. The HOA had nearly zero reserves. The buyer signed anyway because he couldn't afford to pass up the house, and six weeks later he was writing a check he didn't have.
Get the Full Details

Making an Offer: Beyond the Price
The offer price is only one variable. The real levers you have are the earnest money deposit, the inspection contingency, the appraisal gap coverage, the closing timeline, and the ask-right-to-repair clause. Each of these has trade-offs that affect both your risk and your competitiveness. In a hot market, Waiving the inspection contingency gets attention, but it's financially reckless. I've seen buyers waive inspections and discover foundation cracks, knob-and-tube wiring, or deferred maintenance that ran $30,000 to $60,000 to fix. The earnest money you put down is typically one to three percent of the purchase price. If you waive contingencies and the deal falls through for any reason, you lose that money. Keep your inspection contingency. At most, you can shorten the inspection period from 10 days to 5 days to make your offer more attractive without surrendering your protections. The appraisal gap is another area where buyers lose money. If the appraised value comes in below your offer price, the lender will only finance based on the appraised value. You need to cover the difference in cash. In markets where prices moved faster than appraisers could adjust comps, appraisal gaps of $20,000 to $50,000 became common in 2022 and 2023. If you're not prepared to cover a potential gap, your offer is likely to be rejected or your transaction will fall apart mid-process. Write in an appraisal gap clause that states the maximum amount you're willing to cover above appraisal, and keep it reasonable. Offering to cover 20 percent above appraised value sounds aggressive but signals to the seller that you might not have enough liquidity to close.
Closing: The Part Everyone Rushes
Closing is where things most commonly go wrong, and it's also the part people pay the least attention to because they're excited to be done. The closing disclosure form you receive three business days before closing is not a formality. Read it. Compare every line item to your original loan estimate. Lenders are required to provide both documents, and if costs have increased beyond certain thresholds, you may have legal recourse. I had a client who noticed the title insurance premium on his closing disclosure was $800 higher than what his title company had quoted him two weeks earlier. It turned out the closing attorney had substituted a different title company without informing anyone. We caught it because he actually read the documents instead of just signing them. Walk-throughs are your last chance to verify the property's condition before you take ownership. Schedule this within 24 hours of closing, not days before. You're looking for things that changed between listing and possession: moved-out items that weren't supposed to move, damage to walls or floors, non-functional appliances, and any repairs the seller was supposed to complete. If something is wrong, you can request repairs or credits before signing the final paperwork. This is not a bargaining session. It's a verification step. If the seller agreed to fix the roof and it's still leaking during your walkthrough, you don't negotiate. You refuse to close until it's corrected. Here's something most guides skip: the occupancy agreement. If the seller needs to rent back the property after closing for any reason, get it in writing with a daily rate, a security deposit, and clear terms about damage and early move-out. Verbal agreements about rent-backs fall apart immediately when interests diverge. I've seen sellers who agreed to a 30-day rent-back walk away from the property and leave it in ruins because there was no enforceable contract governing their post-closing occupancy.
Post-Closing Obligations Most Buyers Forget
Your property tax assessment may change after the purchase. In many jurisdictions, the sale triggers a reassessment that can significantly increase your annual taxes. Get this number early and factor it into your true carrying cost. Similarly, homeowner's insurance premiums vary wildly between carriers and even between zip codes within the same neighborhood. Shop this separately from your mortgage. A $300,000 home might cost $1,200 annually in one area and $3,500 in another depending on flood zones, fire risk, and proximity to a fire station. Set up your utilities in your name before closing day, not after. There are providers that require 48 to 72 hours to activate service. If you close on a Friday and don't set up electricity until Monday, you're without power for the weekend. Schedule the transfer of water, gas, electric, trash, and internet ahead of time. It takes five minutes and prevents a genuinely frustrating situation on your first night in a new home.
When a Buyer Guide Falls Short
No generic guide will prepare you for every edge case. Real estate transactions are governed by state and local law, and the specifics matter enormously. Escrow requirements differ between California and Texas. Title insurance structures differ between the Northeast and the South. Disclosure laws in Florida are not the same as in Massachusetts. Always consult a local real estate attorney or a licensed professional who practices in your jurisdiction before signing anything. The $500 you spend on legal review will prevent a $50,000 mistake. I've reviewed deals where buyers signed standard purchase agreements that included clauses allowing the seller to accept higher offers up to closing. It was buried in paragraph twelve of an eighteen-page contract, and the buyer had no idea they were competing against their own signed offer. Online platforms and automated valuation models are useful for starting research but dangerous for decision-making. An Zestimate or Redfin Estimate can be off by 10 to 20 percent in markets with limited comparable sales. A home in a unique neighborhood, near a highway, or with non-standard square footage will have poor algorithmic accuracy. Use these tools as a directional guide, not as an appraisal. If you need a precise value, hire a licensed appraiser. It costs $400 to $700 and gives you a defensible number that lenders and attorneys will respect. The process is straightforward in theory and complicated in practice. You prepare your financing, you research the market with real data, you make offers with protected contingencies, you inspect thoroughly, you close with your eyes open, and you handle post-closing logistics before they become emergencies. Do it in that order and don't rush any step, and you'll avoid the mistakes that derail most first-time purchases.