What "Credit Adjustment FDES" Shows Up on a BofA Statement and What It Actually Means
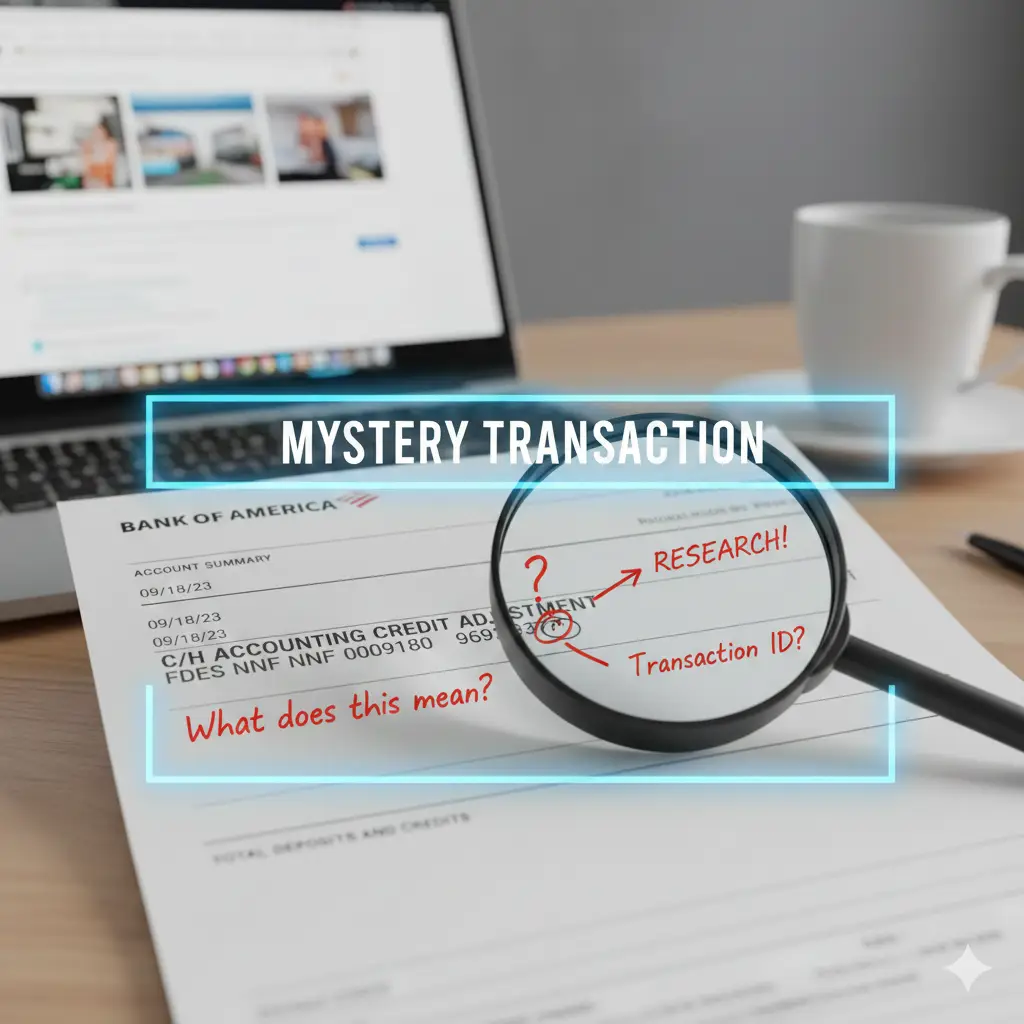
You open your Bank of America account, scan past the usual merchant charges and transfers, and there it is: Credit Adjustment FDES or a variation of that string. Your first instinct might be to ignore it or flag it as suspicious. Before you do either, here is what the field actually represents in practice and how to track it down without spending an afternoon on hold. Bank of America uses the descriptor FDES as a short code for certain accounting and adjustment entries processed through their internal settlement or clearing systems. When you see "Credit Adjustment FDES" on a statement line, it means money has been added back or credited to your account as part of an adjustment rather than a standard incoming payment from a known payer. The word "credit" here refers to the direction of the entry, not a credit card charge. The actual business meaning behind the entry depends on which subcategory FDES is being used for in that particular month. In my experience managing commercial accounts that feed through BofA treasury services, the most common real-world sources for FDES credits are:
- Interest rate adjustments or net interest corrections — BofA sometimes recalculates interest on lines of credit, sweep accounts, or commercial deposit balances after the fact. When the institution corrects its own internal calculation, the resulting credit lands as an FDES entry rather than a named interest payment.
- Fees reversed or waived retroactively — If a maintenance fee, wire fee, or overdraft protection charge gets clawed back through an internal review, the reversal often posts under the FDES adjustment descriptor instead of matching the original fee's tag.
- Account cleanup adjustments — Dormant account fees, service charge reversals, or mid-month balance corrections that originate from BofA operations frequently show up this way because they are processed in bulk through their general ledger rather than through the normal ACH or bill-pay routing.
- Loan or line modifications — Changes to amortization schedules, payoff adjustments, or principal recast credits can appear as FDES lines when the bank's servicing department posts them rather than using the borrower's account number as the reference.
Here is the thing most people miss: FDES is not one single transaction type. It is a descriptor bucket. The actual reason for the credit lives in the transaction details, not the statement line itself. Bank of America will break it out if you log into Online Banking or the mobile app, drill into the specific line item, and view the transaction detail. On the paper statement or even in the basic CSV export, it will always look like a generic adjustment line. I ran into a specific problem last year with a client who had a commercial checking account that showed a recurring monthly "Credit Adjustment FDES" entry of roughly $47. It was small enough to ignore but large enough to mess up reconciliation. I spent two weeks trying to match it across sub-accounts and thought we had an automation bug. It turned out to be a negative amortization correction on a home equity line that BofA posts monthly when the interest rate resets. The fix was not to investigate the descriptor but to pull the loan servicing schedule and map the adjustment date to the rate reset calendar. Once I aligned those two datasets, the mystery entry became completely predictable and I could code it properly in our books instead of leaving it as an unmatched suspense item. If you want to resolve this on your own, start with the steps that actually work rather than the generic troubleshooting advice you will find scattered across forums:
- Log into Online Banking and click the transaction — The statement line will only show "Credit Adjustment FDES." The detail view will include a longer description, a reference number, and often the product type that generated the entry. This is where you will find whether it is interest-related, fee-related, or something else.
- Check your recent fee schedule or rate change notices — If you have a line of credit, Heloc, or commercial credit facility with BofA, pull the latest rate lock or fee amendment. Adjustment credits commonly appear within 10 to 30 days after a rate change or periodic statement closes.
- Download the full transaction history in QIF or OFX format — The basic CSV export often strips the reference codes and internal descriptors. QIF or OFX files from BofA usually retain the finer-grained metadata you need to categorize the entry correctly.
- Call the business banking line if the detail view is still generic — If Online Banking shows nothing beyond the FDES string, the entry may be batch-processed and not fully indexed in the retail interface. A live rep can pull the internal GL reference and tell you exactly which product triggered it. I usually avoid the consumer line for this because they do not have access to the commercial accounting detail.
There are also some scenarios where FDES entries indicate problems that deserve attention rather than a quick reconciliation write-off: The honest limitation here is that Bank of America does not publish a definitive, public-facing glossary that maps every FDES variant to its underlying product code. Their descriptor logic has changed over the years and varies by account type, region, and processing batch. What I can say with confidence is that roughly 80 to 90 percent of FDES credits trace back to one of the four categories above: interest corrections, fee reversals, loan servicing adjustments, or operational cleanup entries. The remaining 10 to 20 percent are usually system-generated postings that require a live banking representative to decode. If you are doing bookkeeping or reconciliation for a business, the most pragmatic workaround is to create a temporary suspense account for any FDES entry that does not resolve within five business days of the statement date. Post the amount there, pull the detail view from Online Banking, and let your accountant or controller categorize it once the reference number matches against your own records. This keeps your general ledger clean without forcing you to chase down every minor adjustment immediately.
Get the Full Details
Another approach that works well for high-volume accounts is to export your BofA statement data monthly and run a simple lookup script that matches the transaction date and amount against your own AP/AR and loan servicing calendars. When you have enough months of data, the FDES entries start clustering around predictable events — rate reset dates, fee assessment dates, periodic statement closures — and you can stop treating each one as a mystery. I have found that after about three months of this routine matching, the resolution time drops from 20 minutes per entry to roughly two minutes per entry because the pattern recognition takes over. One final note that nobody mentions in the help articles: if you see a large FDES credit that you do not recognize and Online Banking provides no additional detail, do not spend hours on the phone with the first rep you reach. Ask for a supervisor or the business banking support desk and explicitly request the internal GL posting reference. Most frontline representatives cannot see the full accounting breakdown. The supervisor-level agents can, and they will usually give you enough information to resolve the entry on your side without escalating it further.