The Math Behind a 40-Year Mortgage
A 40-year mortgage works exactly the same way as any amortizing loan. You borrow a principal amount at a fixed or adjustable rate, and payments are calculated so that the balance reaches zero over 480 months. The formula is standard: M = P [ i(1+i)^n ] / [ (1+i)^n – 1 ] Where M is the monthly payment, P is the principal, i is your monthly interest rate (annual rate divided by 12), and n is 480. That's it. Everything else is just rearranging those numbers.
I've run these calculations for clients going back to the early 2000s, and the mechanics haven't changed. What has changed is how common 40-year terms have become, which means the edge cases are worth talking about.
Calculate 40 Year Mortgage with Real Numbers
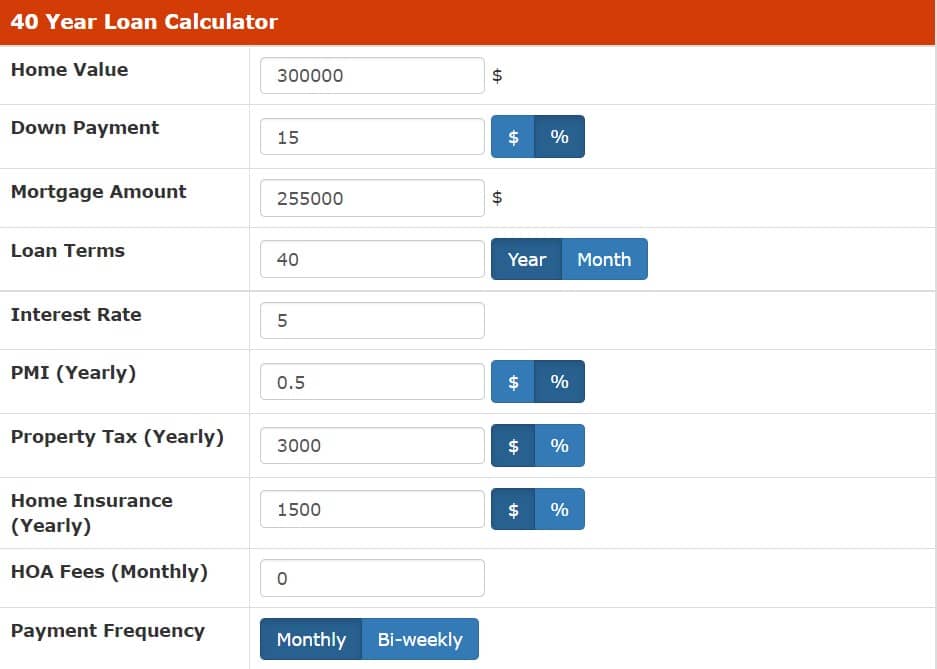
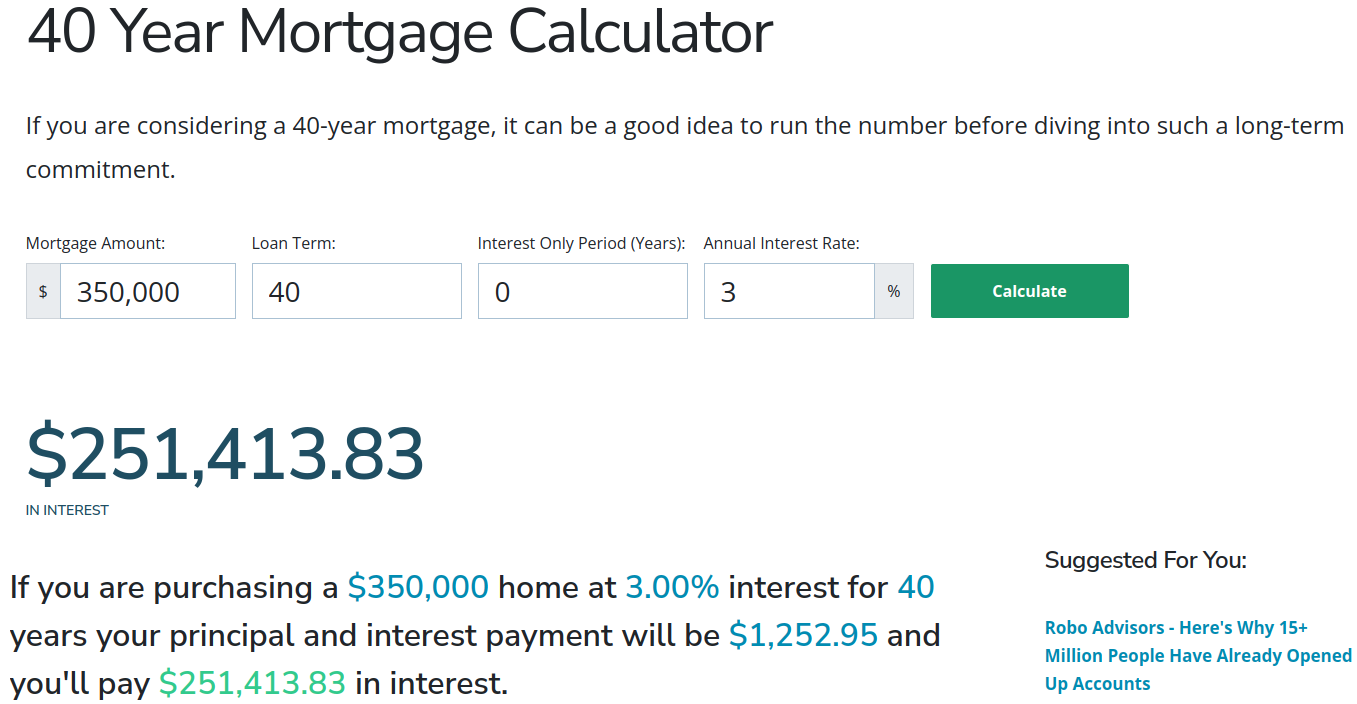
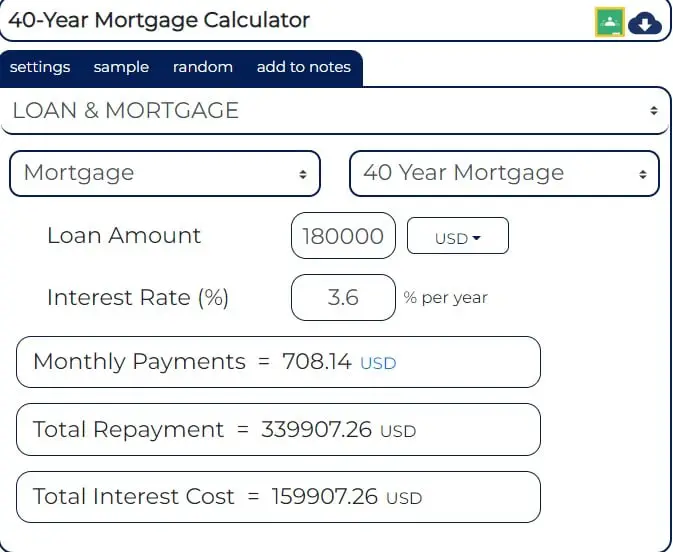
Here's what it looks like in practice. Say someone borrows $300,000 at 6.5% annual interest for 40 years. The monthly rate is 0.54167% (0.065 / 12). Plug that into the formula and you get a monthly payment of roughly $1,971. Over the full life of the loan, that's $946,404 paid total. $646,404 in interest on a $300,000 loan. The payment feels manageable because it's lower than a 30-year version, but the cost is brutal when you see it laid out. For comparison, the same $300,000 at 6.5% over 30 years comes to about $2,132 per month, and $467,550 in total interest paid. So the 40-year saves you roughly $161 a month but costs you an extra $178,854 in interest. That tradeoff is the whole story.
Get the Full Details
Why Lenders Offer Them and Who They Actually Help
40-year mortgages exist primarily because they lower the monthly payment, which improves debt-to-income ratios and helps people qualify. For a self-employed contractor with spotty income documentation, that $161 monthly reduction can be the difference between approved and denied. I've seen that scenario play out repeatedly. They also exist because lenders earn more interest over a longer term. There's a reason promotional emails always seem to push the longer option first. The borrower side is mixed. If you're cash-strapped now and expect income growth later, the lower payment buys you runway. If you're financially stable, you're usually just paying for the privilege of slower payoff. The math doesn't lie, and it's not flattering.
Common Pitfalls People Miss
The biggest issue I see is prepayment assumptions. A lot of people take a 40-year loan thinking they'll pay extra and essentially convert it into something shorter. That works fine if you stay disciplined, but the default trajectory is terrible. Most borrowers don't end up making enough extra principal payments to change the outcome meaningfully. Another overlooked detail: some 40-year products carry slightly higher interest rates than their 30-year counterparts. I had a client in 2019 who was quoted 6.75% for a 40-year at a major regional bank while the 30-year was sitting at 6.50%. She would have saved money on every dollar borrowed by taking the shorter term, despite the higher monthly payment, because the rate differential ate any benefit from the extended term. We restructured her application to the 30-year product and she came out ahead by about $94,000 in total interest, even though her monthly obligation went up $150. Also worth noting: not all servicers handle 40-year loans the same way when it comes to escrow and tax statements. A few had quirks in how they calculated annual disbursements on those longer terms, which caused headaches during the first tax season. Verify your servicer before closing if this is new to them.
When It Makes Sense and When It Doesn't
A 40-year mortgage makes sense if your priority is immediate cash flow preservation and you have a realistic plan to accelerate payoff or refinance into a shorter term within 5 to 10 years. It's a tool, not a lifestyle choice. It doesn't make sense if you're comfortable with a 30-year payment and you're stretching to 40 years solely because the number looks smaller on paper. That's how people end up owing three-quarters of the original balance after twenty years. There's also the refinance angle. If rates drop significantly, you can refinance a 40-year loan into a 15 or 20-year term. But you're at the mercy of whatever the market offers at that future date, and you'll have to go through the full underwriting process again. I've watched people wait years for a refinance window that never materialized because rates stayed stubbornly flat.
Bottom Line
The calculation itself is straightforward. The decisions around whether to use a 40-year mortgage aren't. Lower payments are tempting, but the interest cost over four decades is steep. Run the numbers for your specific principal and rate, compare the total interest against a 30-year alternative, and be honest about whether you'll actually pay it down faster. Most people don't, and the loan structure punishes that assumption hard.