Understanding Balloon Payments in Practice
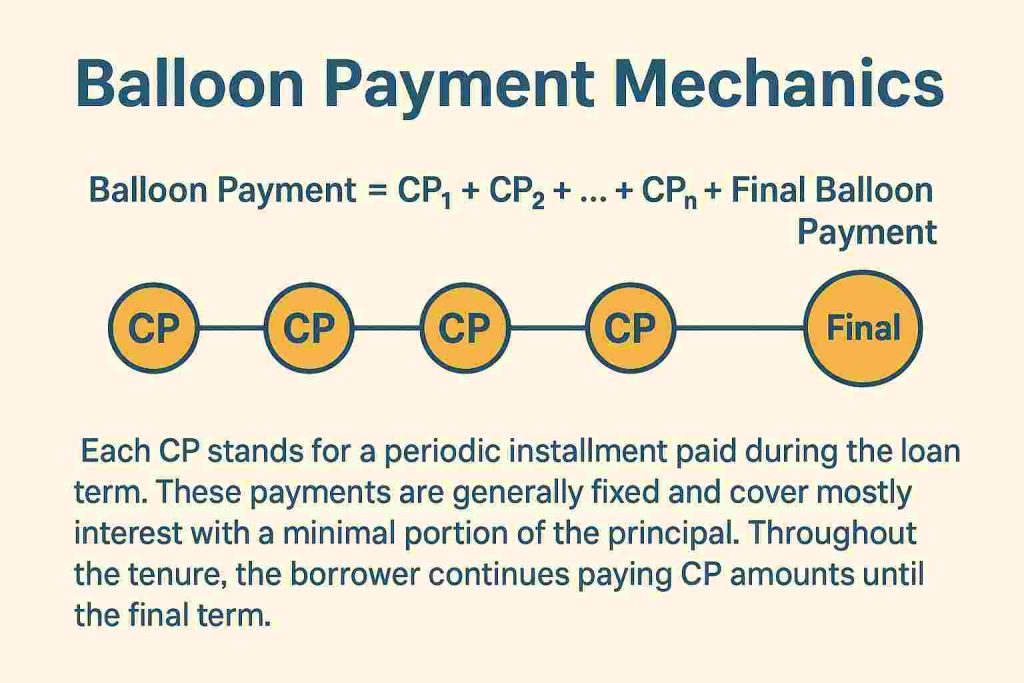
A balloon payment is the large lump sum due at the end of a loan term after you've been making smaller, regular payments based on a longer amortization schedule. It's common in auto loans, equipment financing, and commercial real estate. Most people encounter these when their lender structures a five-year loan with monthly payments calculated as if it were a thirty-year mortgage. At the end of year five, whatever principal remains is due in full. That remaining balance is the balloon. The reason this exists isn't complicated. Lenders use it because it lowers your monthly obligation while keeping the loan short enough that they can offload the risk quickly. Borrowers accept it because they expect to refinance, sell the asset, or have cash coming in by the end of the term. The problem is that expectation doesn't always pan out, which is why understanding how to Calculate A Balloon Payment accurately matters before you ever sign anything.
How to Calculate A Balloon Payment Step by Step
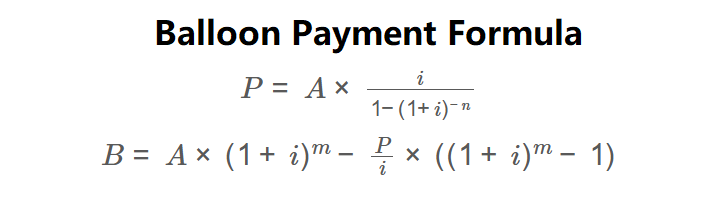
You need four numbers to do this right: the original loan amount, the annual interest rate, the number of monthly payments you'll actually make, and the total amortization period the payments are based on. Everything else follows from those. Start by converting the annual rate to a monthly rate. Divide by 12. So a 7.5 percent annual rate becomes 0.625 percent per month, or 0.00625 as a decimal. Next, figure out your regular monthly payment using the standard amortization formula where the payment is calculated over the full amortization period, not the actual loan term. The formula is: M = P × r × (1 + r)^n divided by (1 + r)^n 1
Where M is the monthly payment, P is the principal, r is the monthly interest rate, and n is the total number of payments over the amortization period. Once you have the monthly payment, you calculate the remaining balance after however many payments you'll actually make during the loan term. The remaining balance formula is: B = P × (1 + r)^k M × [(1 + r)^k 1] / r
Get the Full Details
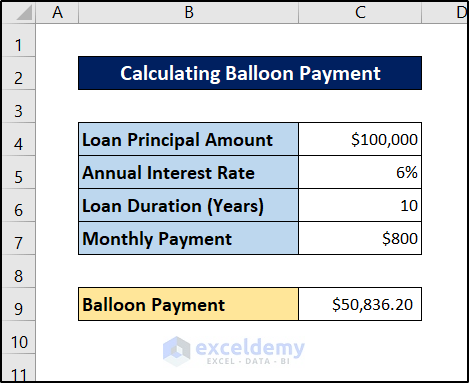
Where B is the balloon payment, k is the number of payments made during the actual loan term, and M is the monthly payment you already calculated. That result B is your balloon payment. I ran through this with an example last month for a client who was looking at a $85,000 equipment loan at 8.2 percent annual rate, structured as a three-year term with payments amortized over seven years. The monthly payment came to $1,194.37. After 36 payments, the remaining balance was $58,742.18. That was the balloon. She hadn't realized how steep that was until I showed her the numbers side by side with what refinancing would have cost her at the time. The tricky part most calculators online gloss over is that the balloon isn't just the unpaid principal. Depending on the loan agreement, it can also include any accrued but unpaid interest, prepayment penalties, or fees that vest at maturity. I learned this the hard way on a commercial lease purchase where the balloon quote I received from the broker didn't account for a 2 percent prepayment penalty that triggered because we paid early. That added another $14,000 to the payoff. Always read the actual contract language around what constitutes the balloon amount.
Here's another thing that catches people off guard: the tax treatment differs depending on whether the balloon is structured as a true bullet payment or a refinance event. A true balloon where you simply pay off the remaining balance doesn't trigger any taxable event. But if the loan terms require you to refinance into a new loan to cover the balloon, that new loan could be treated differently for depreciation recapture purposes on commercial property. This matters more than people think when the balloon hits six figures or more.
Common Pitfalls That Blow Up Balloon Payments
The biggest mistake I see is people assuming the monthly payment stays constant throughout the entire loan. Some balloons are structured with adjustable rates, meaning the payment can change at certain intervals. If the rate resets upward in year two of a three-year balloon loan, your payment jumps and the remaining balance at maturity shrinks slower than you'd expect. Always check whether the rate is fixed or variable before you walk into the end term. Another pitfall is confusing the amortization period with the loan term. These are two different numbers. Your payments are calculated over the amortization period, but you only owe the balloon at the end of the loan term. If someone tells you "monthly payments of $800 for 60 months" without clarifying whether the loan is fully amortized over those 60 months or whether there's a balloon at the end, you need to ask directly. The answer changes everything about your cash flow planning. There's also the issue of partial balloon structures where the loan has multiple balloon events rather than just one at the end. I worked with a borrower who had a loan with a 20 percent balloon at year two and the remaining 80 percent due at year five. Most online calculators can't handle this. You have to manually split the calculation into two phases, calculating the balance after the first balloon payment and then running the amortization forward from there. It adds maybe ten minutes to the work but saves you from being caught flat when the first balloon hits.
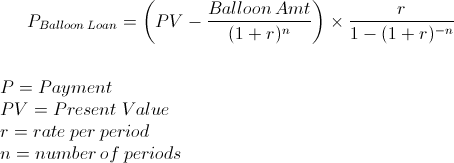
One more edge case that deserves mentioning: some lenders calculate the balloon based on the outstanding balance using a simple interest method rather than standard amortization. In a simple interest loan, each payment covers accrued interest first, and the remainder goes to principal. The daily interest accrual means the balance can differ slightly from what a standard amortization calculator shows. Over a three-year term on a large loan, this difference can be thousands of dollars. Always confirm which method your lender uses.
Practical Tools for Calculate A Balloon Payment
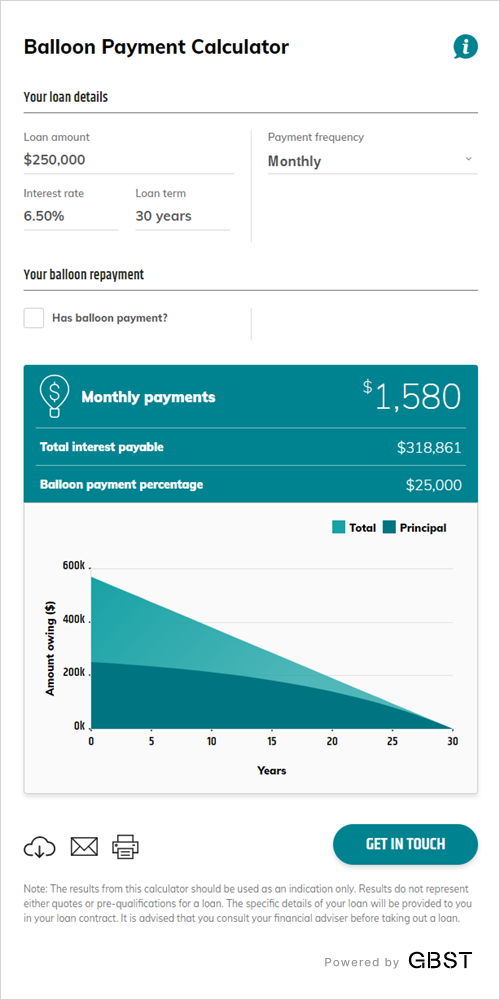
There are several spreadsheets and online tools that automate this. I use a custom Excel model because it lets me build in the edge cases I just described—partial balloons, simple interest adjustments, and prepayment penalty calculations. The free versions you find online will get you in the right ballpark, but they typically assume a simple fixed-rate balloon with no complications. If your loan has any of those complications, the numbers from a free calculator will be optimistic. If you want a straightforward tool to download, the Federal Reserve's consumer finance calculators include a balloon payment module. The one from NerdWallet is also decent for basic scenarios. Neither handles the partial balloon or simple interest variations I mentioned. For anything beyond a simple fixed-rate loan, building your own spreadsheet or using a professional financial model is worth the time investment. A properly built model pays for itself the first time you catch a discrepancy that a generic calculator missed. The bottom line is that balloon payments are a legitimate financing tool, but they require discipline to manage properly. The monthly savings are real, and in the right situation—a business that expects to sell an asset or refinance on favorable terms—they make sense. But if you're counting on the balloon to disappear through magic, you're setting yourself up for a stressful year-end. Know the number before you sign, plan for the worst-case scenario, and don't skip reading the actual contract language around what the balloon includes.