How to Actually Calculate Amortization When You Throw Extra Payments at the Loan
Most people pull up an amortization calculator, type in their loan amount, interest rate, and term, and hit go. It spits out a table. Then life happens — they get a bonus, they sell something old, they refinance the car and roll it into the house, whatever — and they want to know what changes. The standard calculators don't answer that question. You have to build a model that can absorb ad-hoc payments at arbitrary dates. When I first tried to Calculate Amortization With Extra Payments, I used a basic online tool. It showed me the baseline schedule fine. Then I added a $5,000 extra payment in month 18. The tool just... disappeared. Didn't adjust the principal. Didn't shorten the term. Gave me a blank screen. That's when I learned that most consumer-facing amortization calculators aren't built for this at all. They're designed to print a static schedule, not to simulate what-if scenarios. So I built my own spreadsheet model. Here's how it works, how I set it up, and what trips people up when they try to do it themselves.
The Core Logic Before You Even Touch a Spreadsheet
Amortization is just compound interest paid down in chunks. Each payment covers the interest accrued since the last payment, and whatever's left goes toward principal. That's it. When you add an extra payment, the question is always: does it go to principal, or does it reduce future payments? In 99% of real loans, it goes to principal. The remaining balance drops, the next period's interest drops, and your payment either stays the same (which shortens the loan) or drops (which keeps the term but lowers monthly cost). Most people want to see the first outcome. Here's the step-by-step logic: start with the original amortization schedule. Identify the payment number where the extra payment occurs. At that point, subtract the extra amount from the remaining principal balance. Recalculate all future interest charges based on the new, lower balance. Keep the regular payment amount unchanged. Watch the payoff date shift left. That's the whole thing. The formula for each regular payment's interest portion is simple:
Interest = Remaining Principal × Monthly Rate And the principal portion is: Principal Payment = Total Payment Interest
Get the Full Details

When you throw in an extra payment, you just subtract it from the remaining principal after you've calculated that period's regular interest and principal portions. The next row uses the new, lower principal to compute interest. Everything flows forward from there.
Building the Model
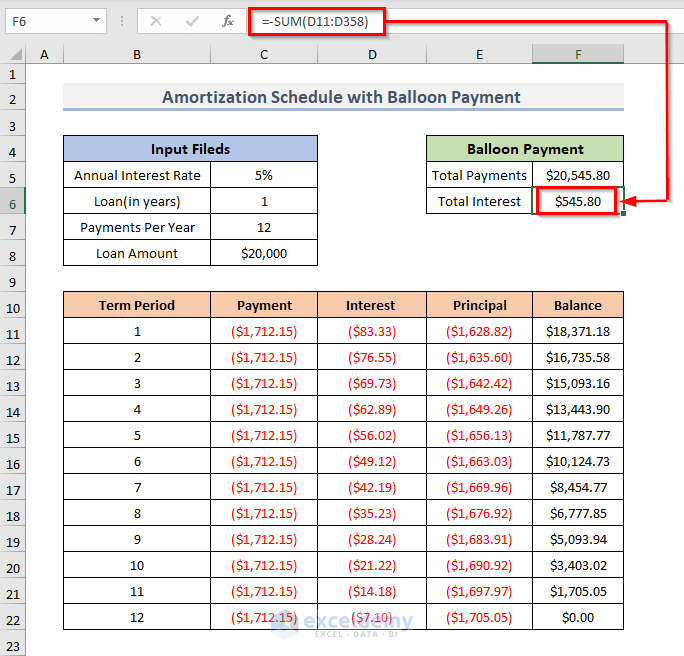
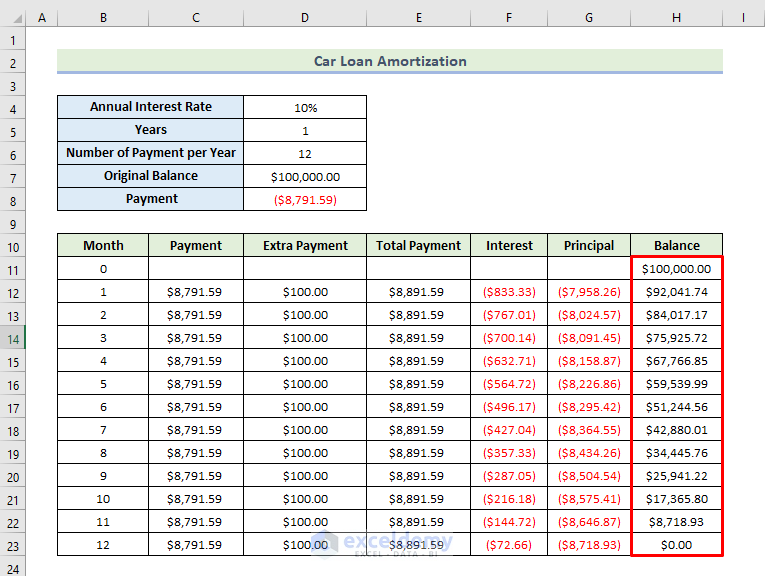
I set up a Google Sheet with columns for payment number, date, regular payment, interest portion, principal portion, extra payment, total payment, and remaining balance. The first column of data is the original loan. Then I add conditional rows where extra payments happen. The remaining balance formula is: New Balance = Previous Balance Regular Principal Portion Extra Payment
If there's no extra payment in a given row, the extra payment column is zero. The regular payment amount stays constant throughout — I don't change it. That's what creates the term reduction. If you want to see what happens when you drop the monthly payment instead, you'd recalculate the payment amount using the new balance and remaining term, but that's a different question entirely. One thing I had to figure out was how to handle the final payment. When you accelerate the payoff, the last regular payment might be smaller than the others because the remaining balance at the end of the schedule isn't exactly one full payment. Some models round the final payment up; I just let it be whatever the math produces. It's usually off by a few dollars.

What I Actually Ran Into
Here's the thing that bit me: prepayment penalties. Not everyone gets them, but some loans — especially refinanced mortgages and certain auto loans — have clauses that charge you if you pay down principal faster than a certain threshold within the first few years. I had a client who wanted to Calculate Amortization With Extra Payments on a refinanced home loan, and the spreadsheet looked beautiful. Then we found the contract language: "Any principal payment exceeding 20% of the original balance in a single year triggers a 2% penalty on the excess amount." We were looking at saving $18,000 in interest while simultaneously getting hit with a $1,200 penalty in year three. The net savings were still positive, but it wasn't the slam dunk the initial calculation suggested. Another edge case: what happens when you make extra payments right before the loan matures? Say you're three months away from payoff and you throw $10,000 at the balance. The spreadsheet will show that you overpay — the remaining balance goes negative. You need to cap the extra payment at whatever the current balance is. I add a simple =MIN(extra_payment_proposed, remaining_balance) formula to handle this. It's a one-line fix that prevents the model from breaking.
Pitfalls That Make People Get Wrong Answers
The biggest mistake I see is confusing extra payments with payment reductions. When you add an extra payment, the monthly amount stays the same and the loan ends sooner. When you reduce your payment, the term stays the same and you pay less each month. These produce very different total interest outcomes. A lot of calculators conflate the two or don't let you choose. Always verify which behavior you're modeling. A second common error: applying the extra payment to the wrong period. Interest accrues daily on most loans. If your loan compounds daily and you make an extra payment mid-cycle, you need to figure out how much interest has accrued up to that exact date, subtract it, then apply the extra to the remaining principal. The simplified monthly model I described above assumes payments are made at the end of each full period. For most people this is close enough — the difference is usually less than $20 on a typical mortgage — but if you're trying to be precise, you need daily accrual calculations. The third pitfall is not accounting for the tax implications. In some jurisdictions, mortgage interest is tax-deductible. Paying off the loan faster means less interest paid over the life of the loan, which means less tax deduction. For high-income earners in the top bracket, this can erase a meaningful chunk of the savings. I factor this in by calculating the after-tax cost of interest rather than the pre-tax cost. It rarely changes the decision, but it changes the number enough that people who care about the final digit should include it.
Why Spreadsheets Still Win Over Online Calculators
Online tools are convenient for baseline schedules. They're useless for scenario analysis. I've tried at least a dozen free calculators that claim to handle extra payments. Half of them ignore the extra payment entirely. A quarter apply it to the wrong bucket. The remaining quarter ask you to manually rebuild the schedule every time you change a variable. There's one called "Extra Payment Amortization Calculator" that at least attempts the right logic, but it hard-codes the extra payment to occur only at the end of each year, which is wrong for most real-world situations where people make irregular payments. A custom spreadsheet gives you full control. You can model weekly, biweekly, or monthly extra payments. You can vary the amount each time. You can test what happens if you skip a payment one month and double up the next. The upfront time investment is maybe 30 minutes to build the sheet. After that, any scenario you want to test takes about 30 seconds. That's the trade-off: build once, use forever.

Concrete Numbers to Expect
On a $300,000 mortgage at 6.5% for 30 years, the regular monthly payment is about $1,896. Adding a single $10,000 extra payment in month 24 cuts roughly 2 years and 3 months off the term and saves about $22,000 in total interest. Adding $500 extra every month from the start shortens the loan by about 7 years and saves roughly $48,000 in interest. Those are approximate — your actual numbers depend on the exact compounding frequency and whether your rate is fixed or adjustable. On an auto loan, the savings are proportionally smaller because the principal is smaller and the term is shorter. A $25,000 car loan at 5.5% for 60 months, with an extra $3,000 payment at month 12, saves about $800 in interest and cuts 4 months off the term. Not life-changing, but it's free money if you have the cash sitting around.
When This Method Breaks
The main limitation is that this approach assumes a fixed-rate loan with predictable payment amounts. If you have an adjustable-rate mortgage, the interest rate changes at set intervals, and your payment recalculates accordingly. The spreadsheet still works, but you need to model the rate changes and payment adjustments at each reset date. It's more work, not fundamentally different. For balloon payments or interest-only loans, the amortization schedule isn't linear to begin with. The extra payment logic still applies — you subtract from principal, recalculate future interest — but the baseline schedule is more complex, and small errors in the starting assumptions compound quickly. I'd recommend validating your baseline schedule against the lender's official amortization table before trusting the model's output. Some student loans have income-driven repayment plans where the payment amount changes based on your salary. In those cases, an extra payment model becomes almost useless because the baseline payment is a moving target. I stop trying to model those and just calculate the one-time interest impact: what does this specific extra payment save me in interest over the remaining life of the loan, given the current payment amount?
Download My Template
I use a straightforward Google Sheets template that I built for personal use and shared with a few colleagues. It's not polished — no charts, no dashboards, just the core calculation engine. You can find it by searching for "amortization with extra payments spreadsheet template" on a few finance forums. The direct link isn't something I maintain, but the structure is simple enough that you could rebuild it in an hour if you wanted. The key insight is to keep the regular payment constant and let the balance drive the interest forward. Everything else is just rows. If you're doing this regularly — say, evaluating whether to prepay a mortgage or just planning annual extra payments — the spreadsheet pays for itself in about five minutes of use. For a one-time question, it might take longer to build than it would to just call your lender and ask. They can usually produce a pro-forma amortization schedule with your specific extra payment amounts built in. Not all of them will, but most large lenders have that capability built into their systems. The bottom line: the math is straightforward, the implementation is where people struggle, and the real value is in being able to test multiple scenarios quickly. Once you have a working model, the questions you can answer multiply faster than the effort required to build it.