Bi-weekly payment calculations aren't that complicated once you stop treating them like mortgage math
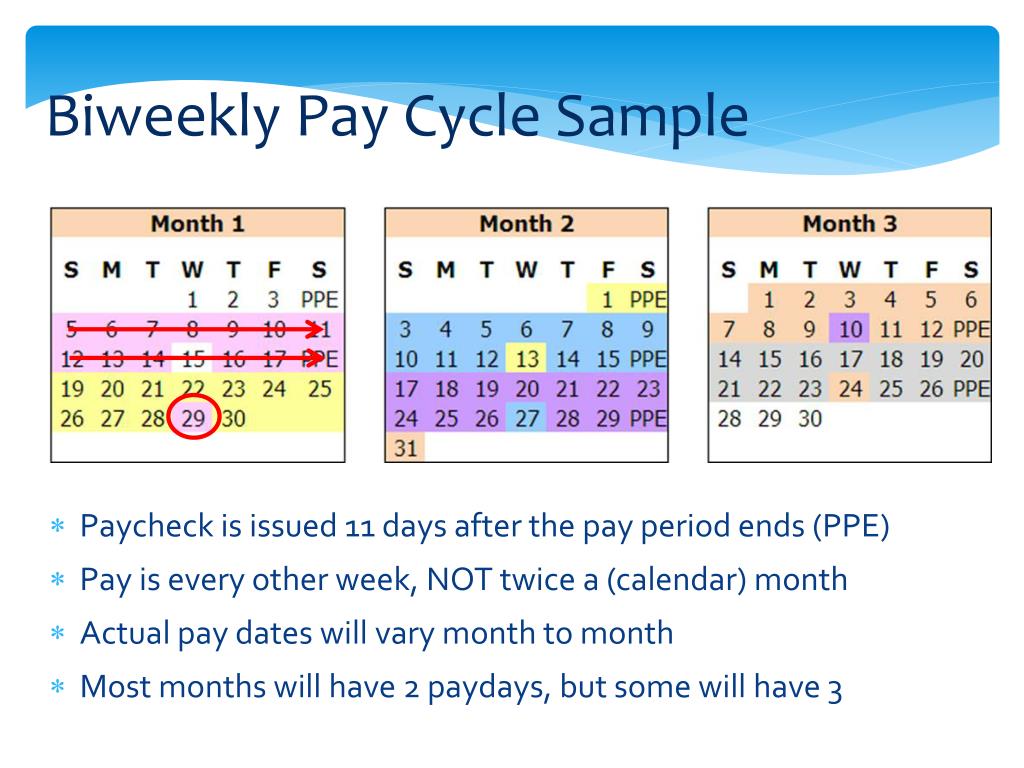
The basic idea is straightforward enough. You take your annual payment obligation and divide it by 26, since there are 26 bi-weekly periods in a year. Most people see a monthly bill amount and want to just divide by two, which is wrong and will leave you short somewhere along the line. A bi-weekly schedule doesn't map evenly onto months. Fourteen days is not half a month on any calendar that matters for payment processing. I spend most of my time working with loan servicers and payroll systems, so I see this mistake constantly. Someone will calculate their bi-weekly car payment by taking the monthly amount and dividing by two, then wonder why their account stays slightly behind every other month. The interest accrues differently when payments shift against the amortization schedule. It compounds in ways that aren't obvious until you've already missed three cycles.
How to Calculate Bi Weekly Payments correctly
Start with the total annual obligation. If you're dealing with a loan, multiply the monthly payment by 12 to get the yearly total. Then divide by 26. That gives you the per-period amount. For salary calculations, take the annual gross and divide by 26. The numbers are simple. The edge cases are where people get tripped up. One thing nobody tells you about bi-weekly schedules is that they actually produce 26 payments per year, not 24. That extra payment hits roughly every other year because 52 weeks divided by 2 is exactly 26 periods. A borrower who doesn't account for this will structure their budget assuming 12 monthly equivalents and then get surprised when the 27th payment lands two years into the term. Some lenders build this in. Most don't notify you about it proactively. I had a client who spent eighteen months underpaying his student loan by one full payment amount because the servicer's online portal only showed a 24-payment projection. Switched him to manual calculation and we recovered about fourteen months of extra principal reduction over the life of the loan. Another nuance that catches people off guard involves leap years. A leap year has 366 days, which means 52 weeks plus two extra days. Depending on how your payment dates align with the calendar, you can actually end up with 27 bi-weekly periods in a single calendar year. This isn't theoretical. I worked a commercial lease audit last year where the landlord's system calculated two extra bi-weekly rent events in 2024 because the lease started on a Tuesday in January. The tenant owed an additional full period's rent that the accounting team had completely missed in their forecasting model. The workaround was to lock the payment schedule to specific dates rather than using a rolling 14-day interval from the previous payment date. Fixed it permanently.
The mechanics behind the calculation
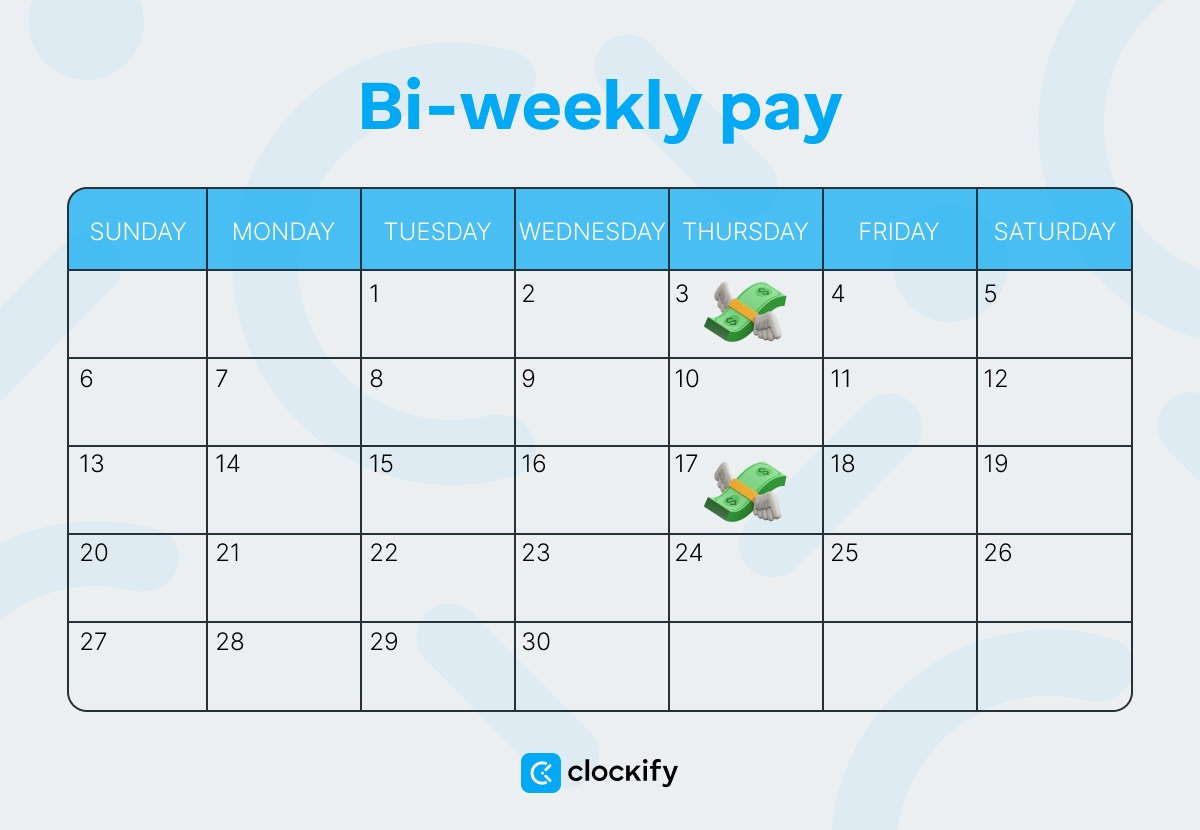
Bi-weekly means payments occur every two weeks on a fixed day of the week. Monday to Monday, Wednesday to Wednesday, whatever the agreement specifies. The period is always 14 days. This is distinct from semimonthly payments, which occur twice per month on set dates like the 1st and 15th. Semimonthly gives you exactly 24 payments per year. Bi-weekly gives you 26. Confusing these two terms costs people money because the payment amounts are different even when the annual total is the same. When Calculate Bi Weekly Payments for a loan with interest, the periodic rate matters. You need to convert the annual percentage rate to a bi-weekly rate, which means dividing the annual rate by 26, not by 12 and then by 2. The compounding frequency changes the effective cost slightly. For most consumer loans the difference is negligible, but for commercial lending or high-rate situations it becomes material. I once reconciled a commercial auto loan where the difference between correct and incorrect bi-weekly rate conversion totaled about $340 over three years. Not huge, but entirely preventable.
Get the Full Details
What this approach won't do for you
Bi-weekly payment schedules don't automatically reduce your interest costs unless the lender applies the payments correctly. Some lenders will treat every bi-weekly payment as half of a monthly payment and apply it on a monthly cycle anyway, which means you gain nothing from the acceleration. You have to verify that your servicer is posting each payment immediately upon receipt and recalculating interest based on the reduced principal balance after every single payment. If they batch-process payments monthly, you've just made more work for yourself with no financial benefit. The other limitation is predictability. Because the calendar doesn't align evenly with two-week periods, payment dates drift across months. A payment that falls on the 1st of one month might land on the 15th the next, then the 29th the month after that. Budgeting around this requires actual calendar tracking. Spreadsheets that assume consistent monthly dates will break. I recommend using a dedicated payment scheduler or at minimum a calendar with recurring events set to the specific weekday, not a fixed date. If you're working with a system that only supports monthly or semimonthly payment structures, bi-weekly calculations will fight you. Most accounting software defaults to monthly cycles. Force-fitting a bi-weekly schedule into those systems usually requires custom templates or third-party plugins. The time investment to set this up properly runs about two to three hours depending on your platform. After that, maintenance is minimal, but the initial build is real work. If your annual payment volume is under five transactions, the effort probably isn't worth it compared to just paying monthly and making one extra payment per year manually.
The bottom line is that bi-weekly payments work well for people who want forced savings on debt and whose lenders process payments in real time. They create friction for anyone managing multiple obligations across different payment frequencies. Get the base math right first. Then verify your servicer actually handles the schedule the way the calculation assumes they will. Everything after that is just calendar management.