HELOC Payment Math: How It Actually Works
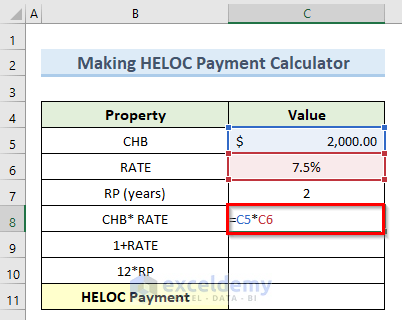
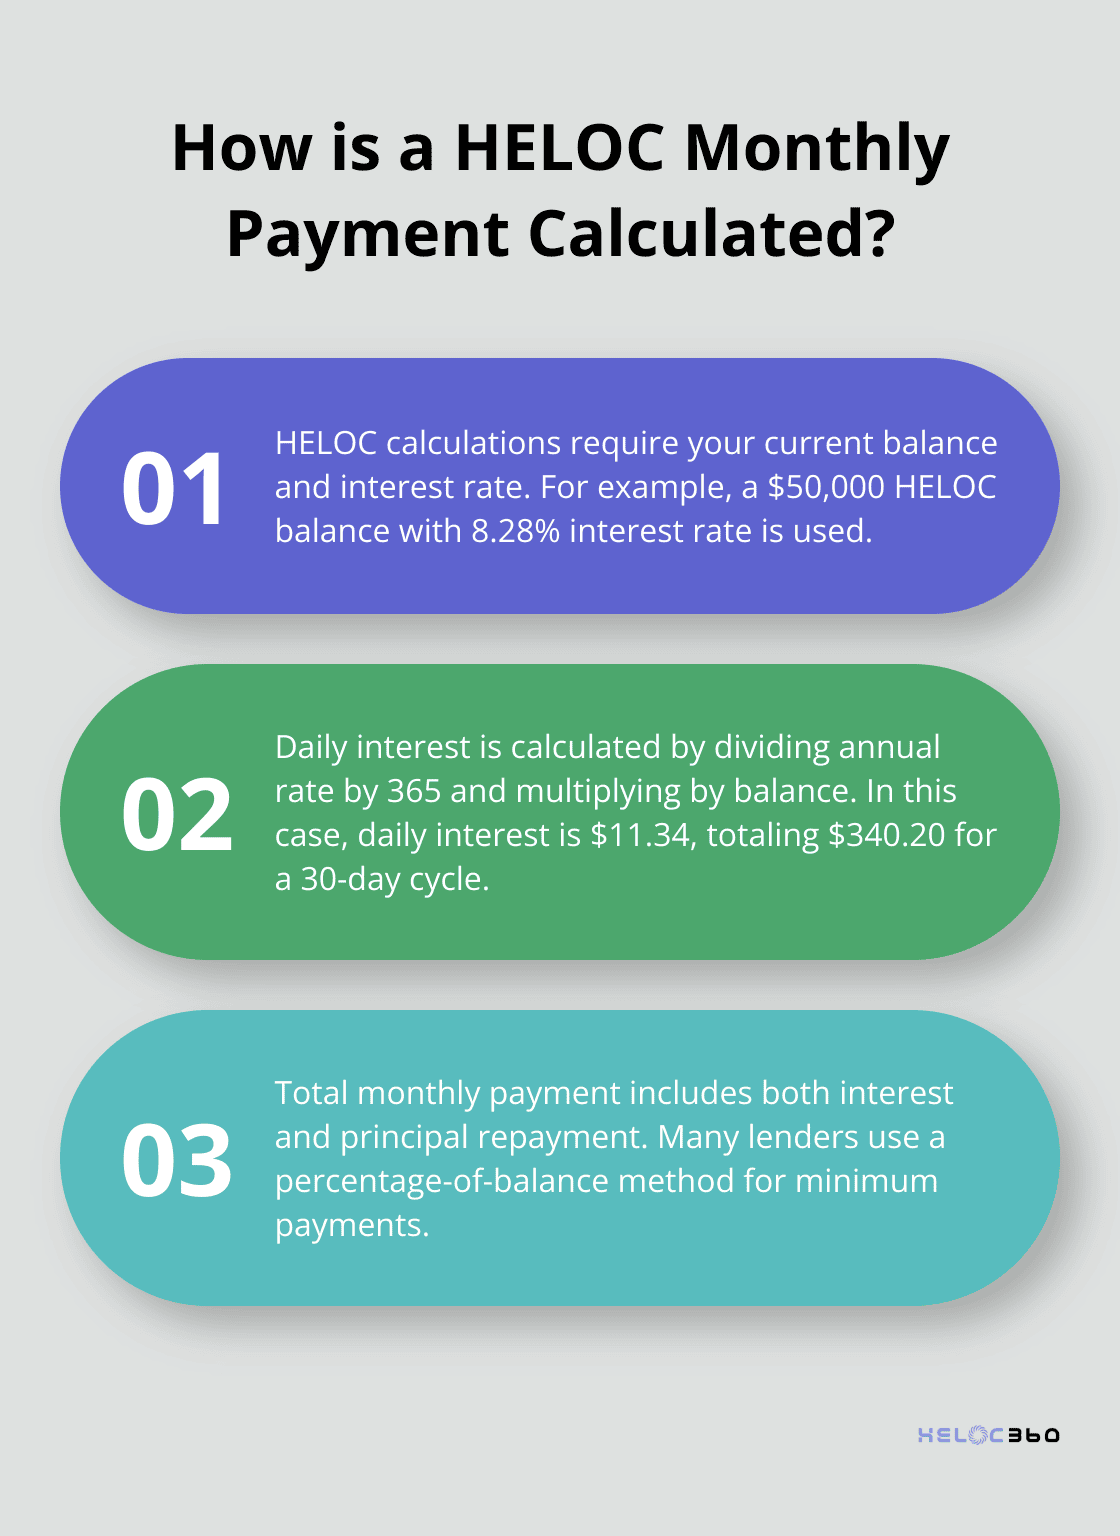
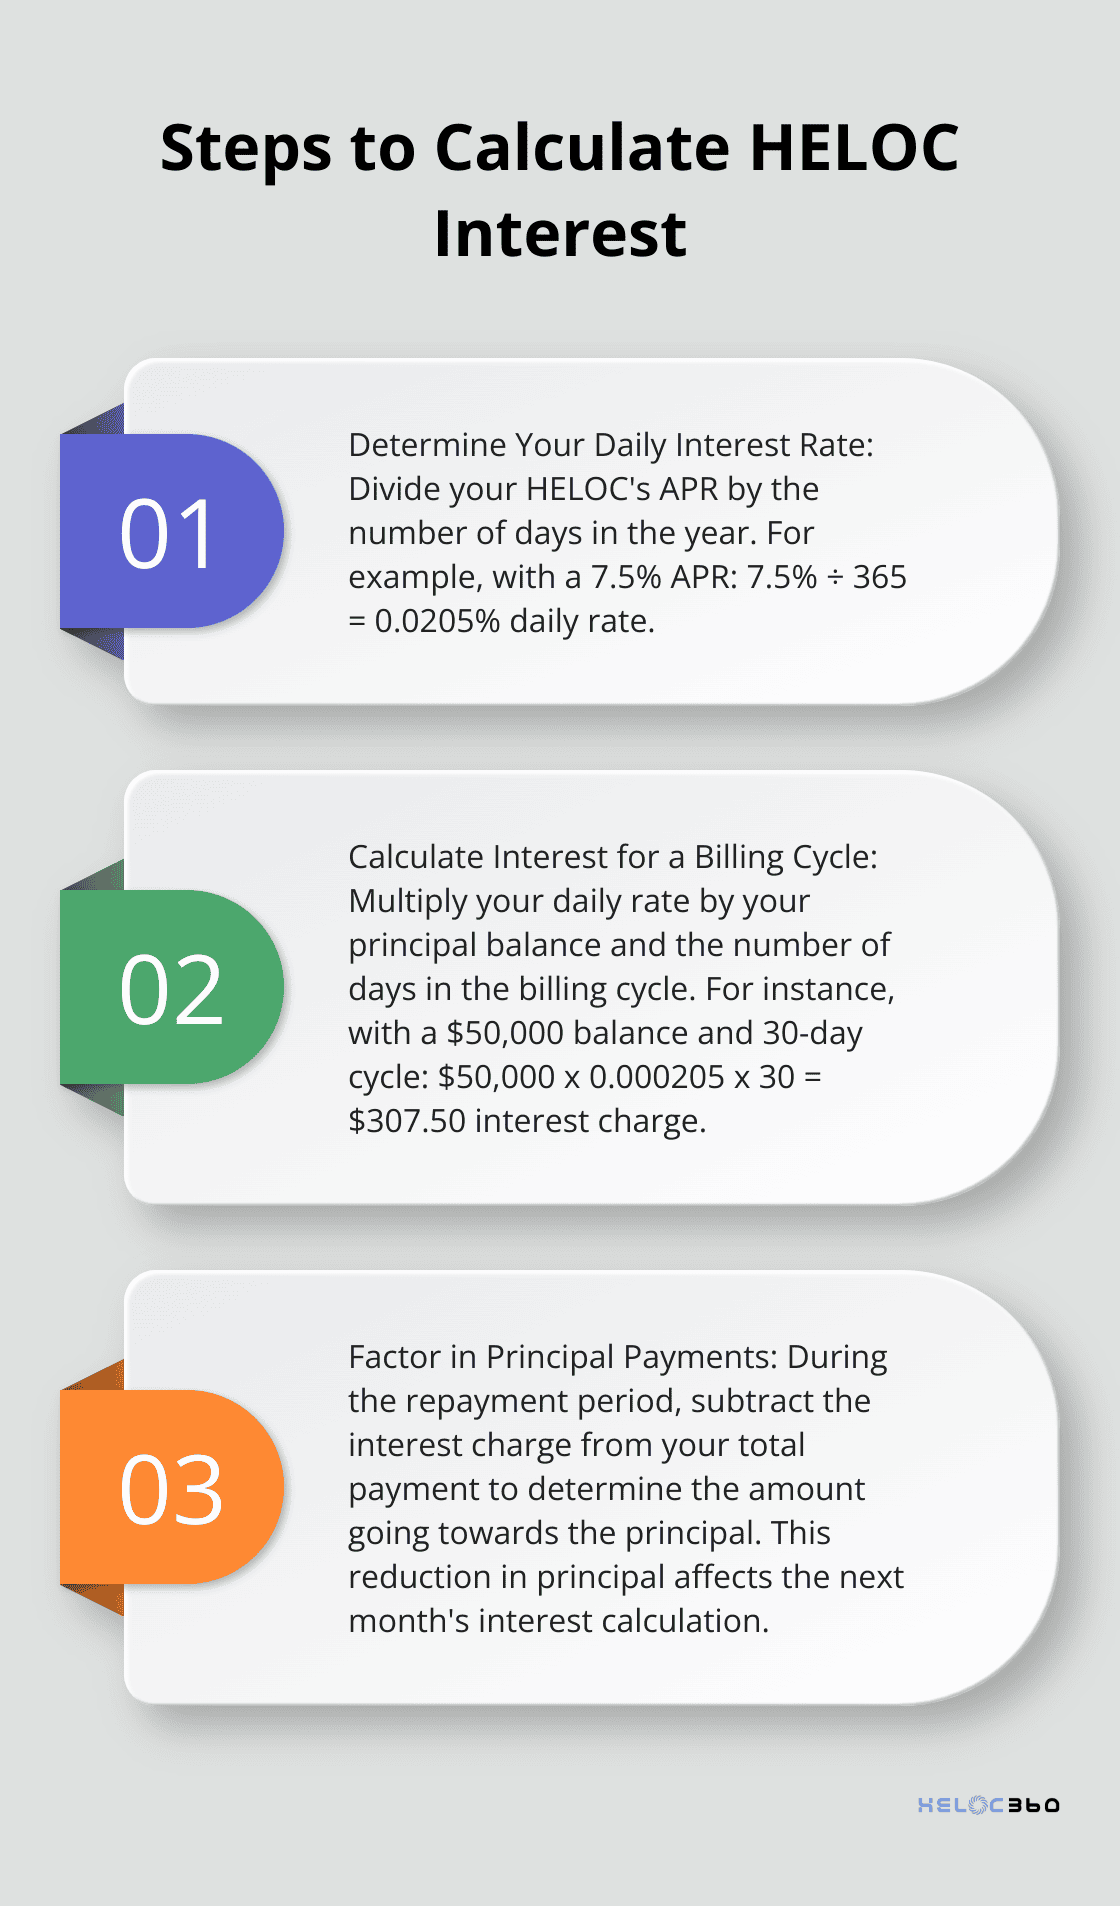
Most people get tripped up on HELOC payments because they assume the calculation is straightforward. It's not. The draw period and repayment period use two entirely different formulas, and mixing them up will throw your numbers off by a significant margin. I learned this the hard way when a client was baffled that their monthly payment jumped from about $400 to nearly $900 with no explanation from their lender. During the draw period, you typically only pay interest on whatever you've actually borrowed, not the full credit limit. The formula is simple enough: multiply your outstanding balance by your annual interest rate, then divide by 12 to get the monthly amount. If you owe $20,000 on a HELOC with a 7.5% rate, your monthly interest payment is roughly $125. That's it. No principal reduction required during this phase. The catch is that most lenders require a minimum payment, usually around $50 to $100, even if the interest calculation comes out lower. Some also allow you to make optional principal payments during the draw period, which is smart if you can afford it since it reduces the balance that accrues interest going forward.
The Repayment Period Changes Everything
Once the draw period ends - usually after 10 years - the calculation shifts to a standard amortization formula. Now you're paying both principal and interest over a set term, commonly 20 years. This is where the payment shock hits people. The amortization formula works like this: your monthly payment equals your remaining balance multiplied by a monthly interest factor, divided by one minus that same factor raised to the negative power of your total number of payments. For a remaining balance of $150,000 at 7.5% over 20 years, your payment would be approximately $1,204 per month. Compare that to the $94 per month you were paying during the draw period on the same balance, and the difference is jarring. I once worked through this exact scenario with a homeowner who had been paying interest-only for nine years. She assumed her payment would stay manageable. It didn't. We had to restructure her payoff plan because the new payment would have eaten into her fixed income. The workaround was refocusing on paying down as much principal as possible during the final year of her draw period, which cut her repayment payment by roughly $200 monthly.
Variable Rates Add Another Layer
Most HELOCs have variable rates tied to the prime rate plus a margin, typically 2 to 5 percentage points. This means your payment can change every adjustment period - usually quarterly or annually. When rates rise, your interest-only payment goes up proportionally. When rates fall, it goes down. There's no stability to budget against unless your lender offers a rate cap or a fixed-rate conversion option. Some lenders also have payment caps that limit how much your interest-only payment can increase at each adjustment, usually capping the rise at 7.5% or $75 per period, whichever is greater. These caps help but don't eliminate the uncertainty. A rate climbing from 6% to 9% over a few years will still meaningfully increase your payment even with caps in place.
Get the Full Details

What the Calculation Doesn't Tell You
The math above covers the base payment. It doesn't include property taxes, homeowner's insurance, or any lender-required fees that might be escrowed into your monthly obligation. Some lenders bundle these into a single payment, which can make the total look substantially higher than your pure loan payment. Always ask for a breakdown so you know what portion is actual debt service versus escrow. There's also the issue of what happens if you draw more money during the repayment period. Some HELOCs allow continued draws during repayment but require immediate principal and interest payments on any new borrowings. This can create a compounding payment increase that catches people off guard. The calculation for those additional draws uses the same amortization formula, but layered on top of your existing payment. If you're trying to figure this out yourself, a spreadsheet with separate tabs for draw-period and repayment-period calculations will save you considerable time compared to relying on online calculators, which often gloss over the transition between periods. Many free calculators online only show the interest-only phase and don't demonstrate the payment jump that follows. That omission matters.