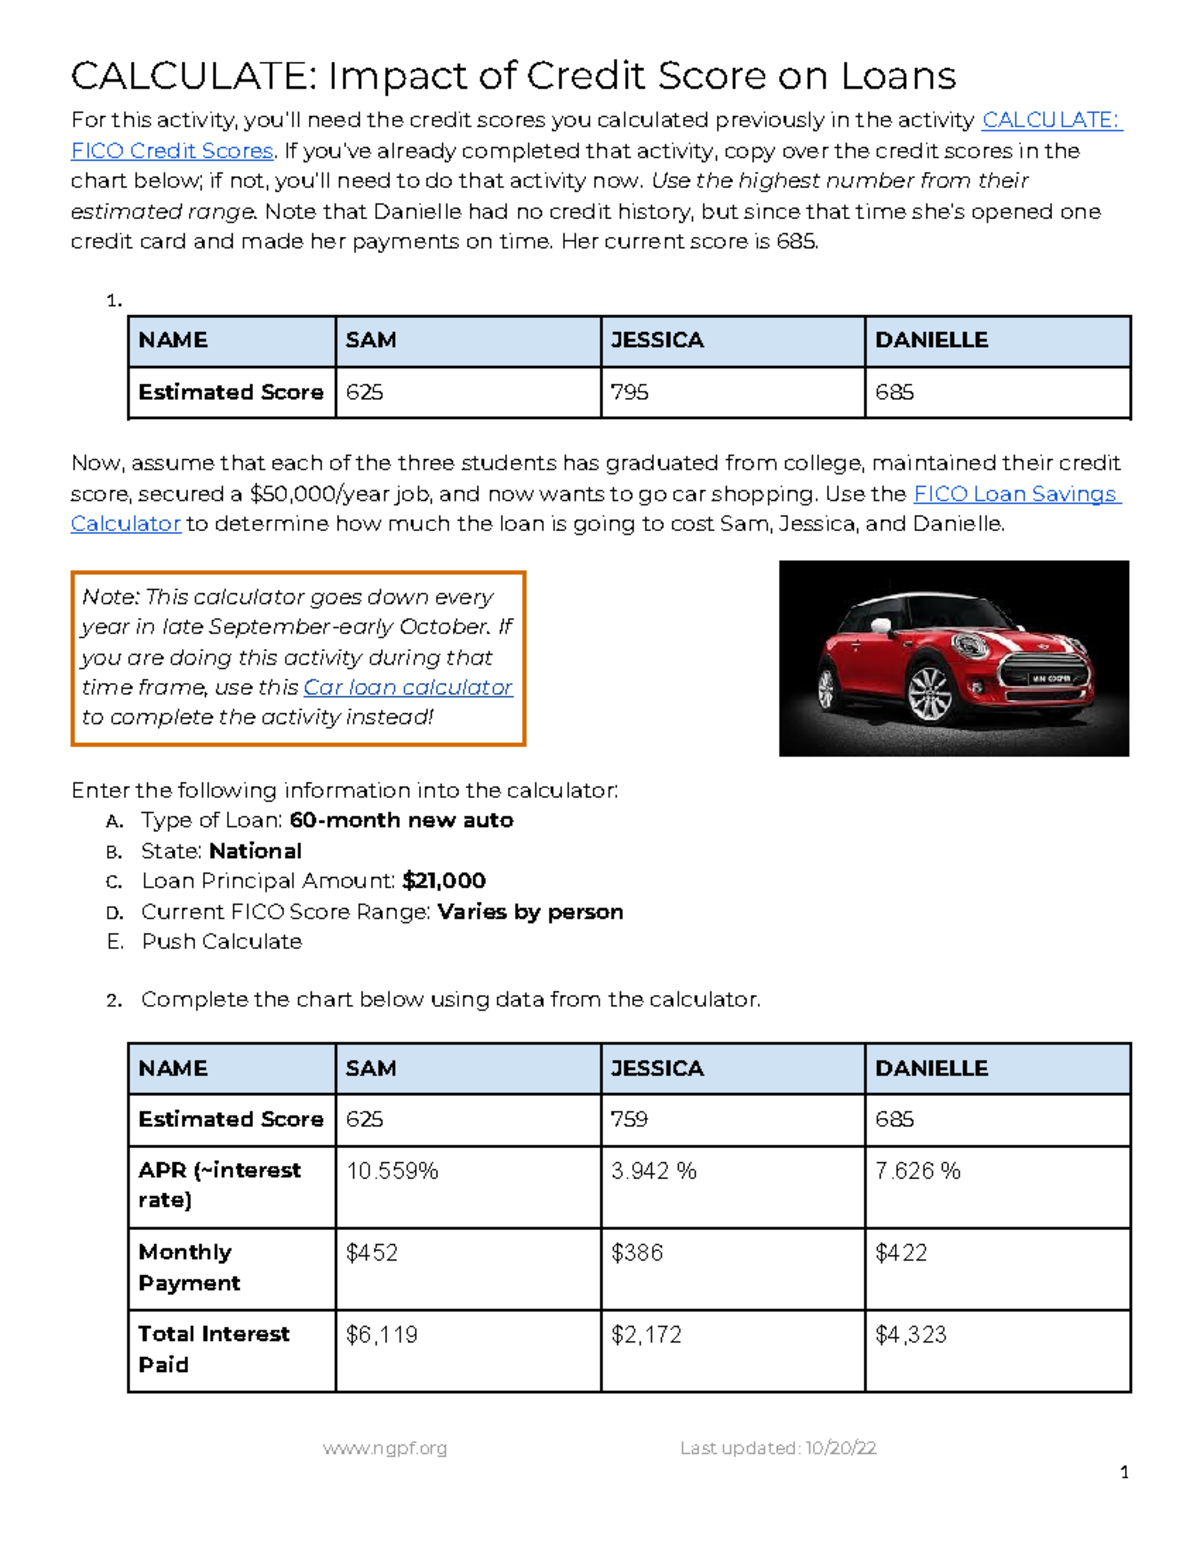
Understanding How Credit Scores Change Loan Terms
Most people have no idea how much a fifty-point swing in their credit score can actually cost them over the life of a loan. I've sat across from clients who were shocked to learn that moving from a 680 to a 720 FICO score dropped their 30-year fixed mortgage rate by nearly a full percentage point. That difference translates to tens of thousands of dollars in interest paid over time. The math isn't complicated, but the way lenders apply it varies enough to trip people up. When you're studying this for a class or trying to understand it on your own, the core concept is straightforward. Lenders use credit scores as a proxy for risk. Higher score means lower perceived risk, which means better terms. But the relationship isn't linear. The jump from 580 to 620 matters enormously. The jump from 760 to 800 matters almost nothing at all. Most scoring models plateau well before you hit perfect credit.
Calculate Impact Of Credit Score On Loans Answer Key Quizlet
If you're looking for study materials on this topic, Quizlet has a bunch of flashcard sets that cover the basic calculations. I used a set like that back when I was training junior analysts. The answer keys are generally accurate for textbook scenarios, but they tend to oversimplify things. Real lending doesn't work the way multiple-choice questions make it look. The flashcards will get you through a test. They won't prepare you for an actual loan application. Here's how the calculation actually works in practice. Take a base interest rate for a given loan product at a given credit tier, then apply the risk premium or discount that corresponds to the borrower's actual score. For a conventional 30-year mortgage, you might see something like this: scores between 620 and 639 carry a roughly 0.5 to 0.75 percent premium over the base rate. Scores above 760 might earn a 0.25 percent discount. Those numbers shift constantly depending on market conditions and which FICO version the lender uses, but the structure stays the same. I ran into a real problem once with a borrower whose credit score was 715. Textbook calculation suggested he'd qualify for a solid rate. What the model didn't account for was a recent hard inquiry from a different lender thirty days earlier. That inquiry, combined with a slightly higher debt-to-income ratio than the standard template allowed, pushed his actual approved rate up by another quarter point. The Quizlet-style problems never include edge cases like that. In the real world, they're the whole story.
The workaround I used was to run a full manual underwriting review instead of relying on automated pricing grids. I pulled the actual lender overlays, checked for recent credit activity, and adjusted the rate sheet manually. It added maybe twenty minutes to the process, but it prevented an offer that would have looked good on paper and fallen apart at closing. If you're studying this material, pay attention to the sections about lender overlays and non-score factors. Those are the things that separate textbook answers from real outcomes.
Get the Full Details
Practical Calculation Steps
Let me walk through a concrete example. Say you're looking at a $300,000 conventional loan at 7 percent interest for 30 years. Your monthly payment comes to about $1,996. If your credit score pushes the rate up to 7.75 percent, that same loan costs roughly $2,155 per month. Over thirty years, that's about $47,700 extra in interest. Not something you'd casually overlook. Now flip it. Drop the rate to 6.5 percent with a strong score, and your monthly payment falls to about $1,896. You save roughly $100 a month and about $35,800 over the life of the loan. These are rough estimates. Actual numbers depend on the loan type, the lender, the market, and a dozen other variables. But they illustrate the scale of what's at stake. One thing most beginners miss is that credit score tiers vary by loan product. A score that lands you in the prime tier for a conventional mortgage might put you in the near-prime tier for an auto loan. Auto lenders tend to use more aggressive pricing gradients. A twenty-point difference can swing an auto loan rate by half a percentage point or more, while the same twenty points barely moves a mortgage rate. The loan type changes the calculus entirely.
Another counter-intuitive detail is that not all credit scoring models work the same way. FICO 8, FICO 9, and VantageScore 3.0 all weight factors differently. A borrower might have a 710 under FICO 8 and a 695 under VantageScore. Some lenders use one, some use the other, and some use median scoring across three bureaus. The number on your dashboard isn't necessarily the number the lender sees.
Limitations and When This Approach Falls Short
The credit score impact calculation is useful, but it's a blunt instrument. It doesn't capture your full credit profile. A high score with a thin file tells a different story than a high score with a long, diverse history. Lenders notice that. Automated underwriting systems flag thin files for additional review even when the score looks good. Another limitation is that credit scores only matter within a certain window. How recent is your score? Most lenders pull a fresh report at application and again at closing. If your score dropped fifteen points between those two pulls, the rate lock could be challenged. I had a client lose his rate lock because a medical collection he thought was resolved actually hadn't been updated on one of the three bureaus. The score dipped, the lender repriced the loan, and he had to bring thousands more to closing. The calculation model doesn't teach you about rate lock expiration windows or the three-bureau discrepancy problem. If you need a more comprehensive view than a Quizlet flashcard set can give you, consider using an actual loan estimator tool from a major lender's website or a platform like NerdWallet or Bankrate. They incorporate current market rates and show side-by-side comparisons across score tiers. For academic purposes, the flashcards are fine. For real decisions, you need live data.
The bottom line is that credit scores matter significantly, but the relationship is neither simple nor uniform. The numbers you see in textbooks are directional, not definitive. Real lending involves overlays, model variations, and timing issues that no multiple-choice question captures. Understanding the calculation is the first step. Understanding what the calculation leaves out is where most people actually get burned.


