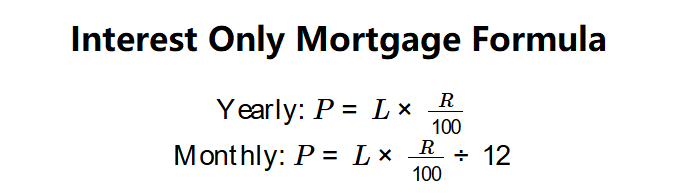Interest-Only Calculations: What Actually Happens
You take the principal balance, multiply it by the annual interest rate, and divide by 12 to get your monthly payment. That is the entire mechanic. Nothing fancy about it. The confusion comes from everything else that surrounds the calculation, not the math itself. Start with your loan amount. Let us say you have a $250,000 investment property loan at 6.5% annual rate. Monthly interest-only payment is $250,000 times 0.065 divided by 12. That gives you $1,354.17. Every month, same number. The principal never touches. Most people mess up the compounding assumption. Some loans use daily interest accrual, especially in commercial real estate or construction lending. Daily accrual means your monthly payment fluctuates slightly depending on how many days are in the month. A 30-day month costs more than a 28-day one. I learned this the hard way when I was running pro forma for a multi-family deal in Austin. The broker gave me a simple annual rate and said "interest only." I built the model with flat monthly payments, closed the deal, and then the actual payment schedule showed $47 variance per month. Over 60 months, that adds up to nearly $3,000 in unexpected cash outflows. The fix was switching my model to daily accrual using the actual/360 day count convention that the loan documents specified. Took me about twenty minutes to adjust the spreadsheet once I knew what convention to look for.
The other thing people miss is the distinction between the note rate and the effective rate. If your loan has points or origination fees rolled into the balance, your actual yield is higher than the stated rate. On a $500,000 loan with 1.5 points, you are actually borrowing $507,500 but paying interest on $500,000 at the stated rate. The gap is small in absolute terms but it changes your debt service coverage ratio calculations enough to matter when you are underwriting.
Where This Breaks Down
Interest-only is fine if you are holding the asset for a short period and exiting before the amortization cliff hits. The problem is most people treat the low initial payment as a permanent feature rather than a deferred cost. The principal remains untouched during the IO period, which means you are not building equity through paydown. You are entirely dependent on appreciation or refinancing to generate any return. If the property does not appreciate and you need to refinance at the end of the IO term, you are exposed to rate risk and credit risk simultaneously. I have seen this play out twice in the last five years. Once with a client who took a 5-year IO on a class B office building in Nashville, and again with a fix-and-flip investor who extended an IO period three times on a residential deal. Both ended poorly because the underlying assumption was that the asset would generate enough value to sell or refinance before the payment reset. It did not work out. The alternative most people should be considering is a standard amortizing loan if they plan to hold longer than five to seven years. The monthly payment is higher from day one, but you are not facing a payment shock or needing to sell under potentially unfavorable conditions just to escape the structure. For short-term holds where you are flipping or refinancing within 18 to 36 months, interest-only makes mathematical sense. Beyond that window, the advantage disappears quickly.
Get the Full Details

One more practical detail: make sure you verify whether your lender capitalizes unpaid interest if the IO payment does not cover the full accrued amount. Some junior mezzanine loans and hard money structures do this, and it silently increases your principal balance each month. I catch it by pulling the actual amortization schedule from the lender portal instead of relying on what the closing documents summarize. The schedule tells you everything.