What PITI Actually Covers
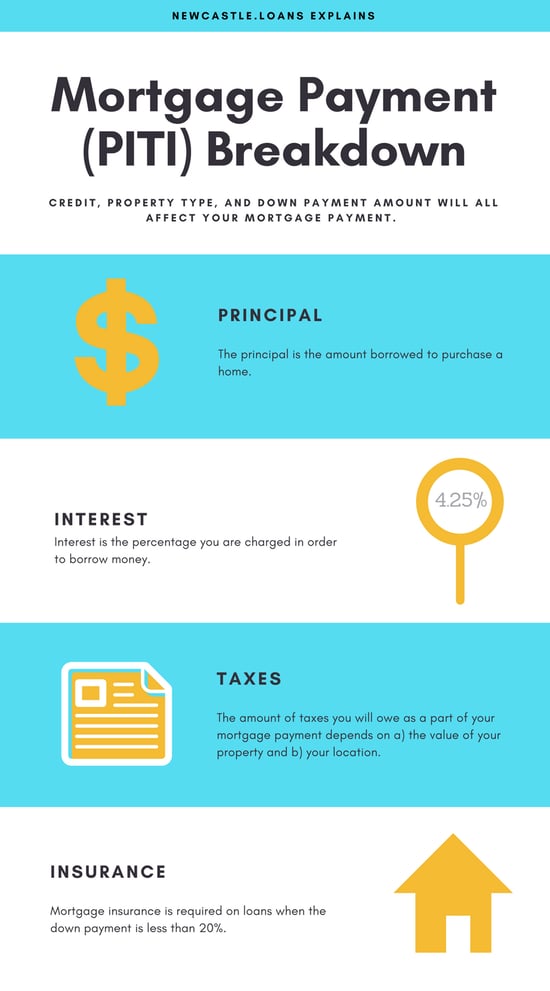
PITI stands for Principal, Interest, Taxes, and Insurance. It is the full monthly housing payment that lenders use to evaluate whether you qualify for a mortgage. Most people only think about principal and interest when they look at a loan estimate, but the other two components are just as important and can completely change your approval numbers. The principal is the amount you borrowed. The interest is what the lender charges for lending you that money. Property taxes come from your county assessor and get collected into an escrow account. Homeowners insurance is required by the lender to protect their collateral. Combine all four and you get a single monthly figure that determines your debt-to-income ratio.How to Calculate Piti Step by Step
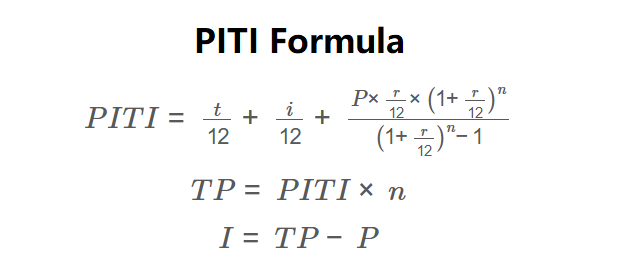
Start with the loan amount and interest rate. For a $350,000 loan at 6.5% over 30 years, your principal and interest come out to roughly $2,212 per month using the standard amortization formula. You can type that into any mortgage calculator or work it out manually with the formula: M = P [i(1+i)^n] / [(1+i)^n – 1], where P is the principal, i is the monthly interest rate, and n is the number of payments. Next, factor in property taxes. Take your home's assessed value and multiply it by the local tax rate. If your county rates properties at 1.2% annually and the assessed value is $350,000, that is $4,200 per year, or $350 per month. Tax rates vary wildly by location. In some areas they hover around 0.5%. In others they exceed 2.5%. Always check your specific jurisdiction instead of guessing. Then add homeowners insurance. Get a quote from at least two carriers. A standard policy on a $350,000 home typically runs between $80 and $150 monthly, though hurricane zones and wildfire areas can push that significantly higher. Divide the annual premium by 12 to get your monthly figure.
Add all three components together. In this example: $2,212 + $350 + $120 = $2,682 monthly PITI. That is the number that goes on your loan application and the number the underwriter will stress-test against your income. I ran into a specific issue a while back working with a borrower in Cook County, Illinois. The property tax bill had just been reassessed upward by about 18% due to a market reset, but the county hadn't mailed the new bill yet. The borrower had last year's numbers on file. If I used the old tax figure, the PITI would have been understated by roughly $180 per month. That pushed the debt-to-income ratio under the lender's 43% threshold when it should have been over. I pulled the reassessment notice directly from the county portal and used the projected annual amount instead. The loan got re-underwritten with the corrected number. Nothing messy happened because we caught it early, but this kind of timing gap shows up more often than you would expect, especially during periods of rapid assessment changes.
Why PITI Matters More Than You Think
Lenders cap your PITI at a percentage of your gross monthly income. Conventional loans typically allow front-end ratios up to 28%, though some programs go as high as 31%. Back-end ratios, which include all your debt obligations, usually max out around 43% for qualified mortgages, with some exceptions pushing toward 50% depending on the program and compensating factors. Here is a detail most first-time buyers miss: private mortgage insurance, or PMI, is not part of PITI. It is a separate monthly cost that sits on top of your PITI payment if you put down less than 20%. When a lender says your monthly housing payment cannot exceed $2,000, they mean PITI only. Add PMI separately to that, usually between 0.3% and 1.2% of the loan amount annually divided by 12. On a $350,000 loan at 0.85% PMI, that is another $248 per month on top of your PITI. Another counter-intuitive point: escrow shortages and overages are real and they do not show up on your initial estimate. If your property tax or insurance bill jumps mid-year, your servicer may request a higher escrow contribution to cover the shortfall. This can increase your monthly payment without warning. I had a client in Arizona whose insurance premium doubled after a cluster of claims in his zip code. His PITI estimate was accurate at closing, but the actual payment increased by $210 the following year when the servicer recalculated the escrow. He had budgeted for the original number and nearly went delinquent.
Get the Full Details

HUD-1 and Closing Disclosure forms list PITI clearly, but the breakdown is sometimes buried in Section B of the Closing Disclosure under "Estimated Monthly Payment." Look for the line that reads "Principal and Interest" and the lines below it for taxes and insurance. If any of those three categories is missing or listed as zero, double-check before signing. It happens more frequently than it should on rushed closings. If you are trying to minimize your PITI without reducing the loan amount, your levers are limited. You can shop lenders for a better rate, which might save you a few hundred dollars monthly over the life of the loan. You can choose a shorter term if your cash flow allows it, though that increases the monthly principal and interest portion. Refinancing later when rates drop is another option, but that introduces closing costs you need to weigh against projected savings. There is no clean way to lower property taxes unless you successfully appeal your assessment, which is a separate process entirely.
When PITI Calculation Breaks Down
Fixed-rate mortgages are straightforward. Variable-rate loans introduce uncertainty because the interest component fluctuates. Some lenders use a cap rate or a starter rate for qualification purposes, which can make your calculated PITI artificially low during the initial period. Always ask which rate they used for qualification and what the fully indexed rate is. Condo and co-op purchases add another layer. HOA fees are technically not part of PITI, but many lenders fold them into your housing expense ratio anyway. FHA loans sometimes require mortgage insurance premiums that get baked into the loan amount or paid monthly. VA funding fees are rolled into the principal rather than added monthly. Each program handles these extras differently, and the impact on your actual monthly outlay can differ substantially from what a basic PITI calculation suggests. There is no free tool that handles every edge case correctly. Generic online calculators will give you a rough number, but if you need accuracy for underwriting or negotiation, run the numbers yourself using the actual loan documents and local tax data. Spend twenty minutes pulling the right figures and you will avoid the kind of surprises that cost people their approvals.