Retirement Savings Calculations Are More Messy Than Most Tools Admit
Most retirement calculators you find online give you a single number and call it a day. They assume your expenses stay level, your investment returns are consistent, and inflation behaves nicely. None of that is true. I ran through enough of these back when I was doing estate and retirement planning for clients to know that the real answer is a range, not a point value. The gap between a naive calculation and a realistic one can easily be $200,000 to $400,000 depending on how much stress-testing you actually do. Here is how the process works when you stop treating it like a textbook problem and start treating it like something that will actually happen to a real person with real market exposure.
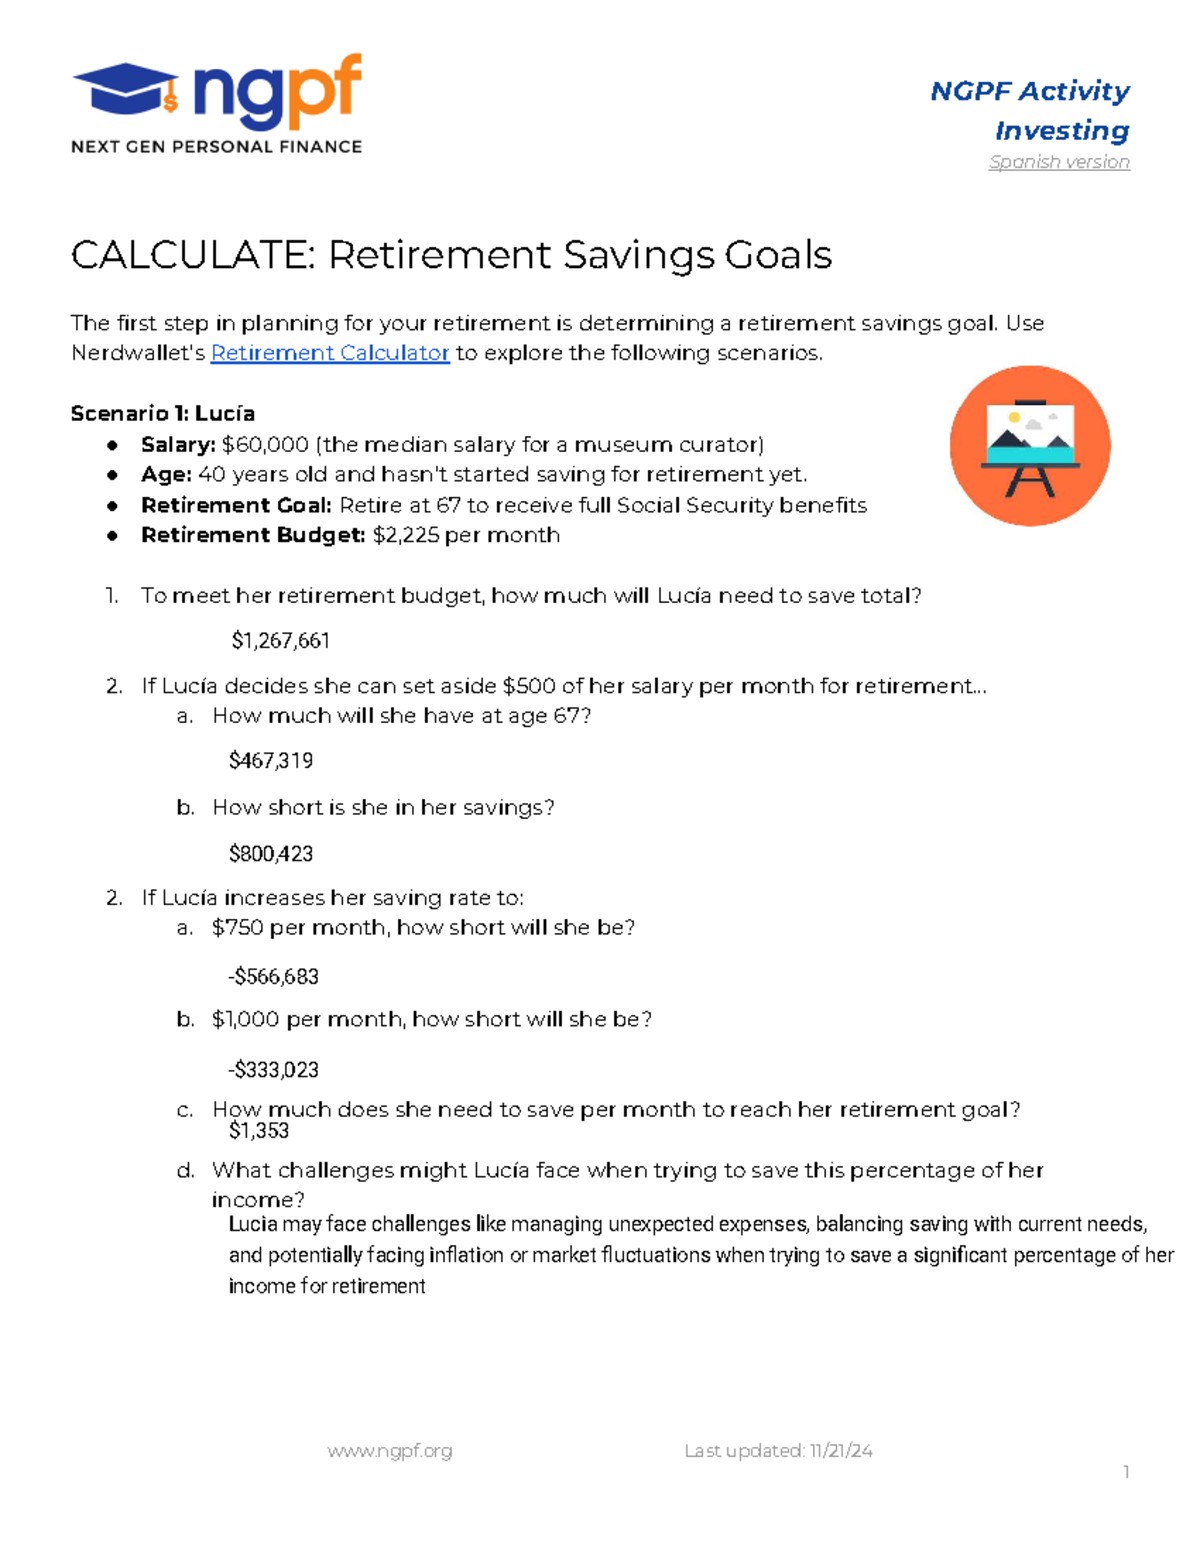
Understanding the Calculate Retirement Savings Goals Answer Key
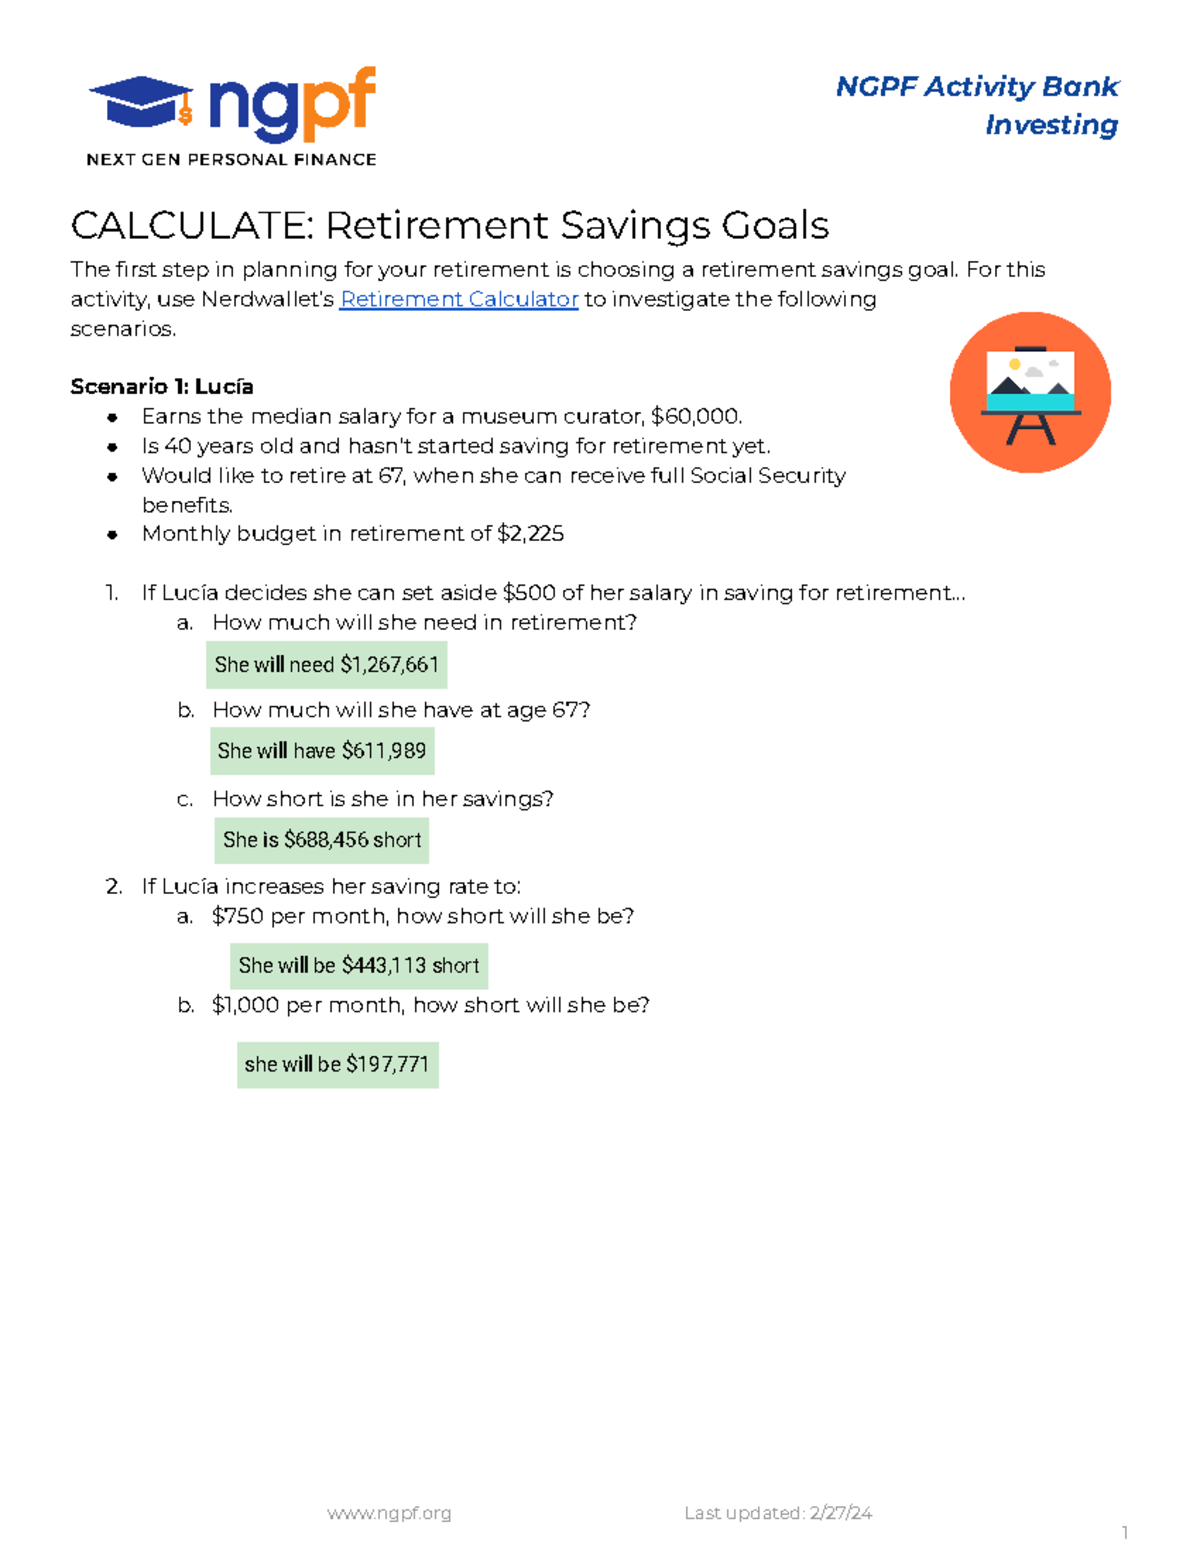
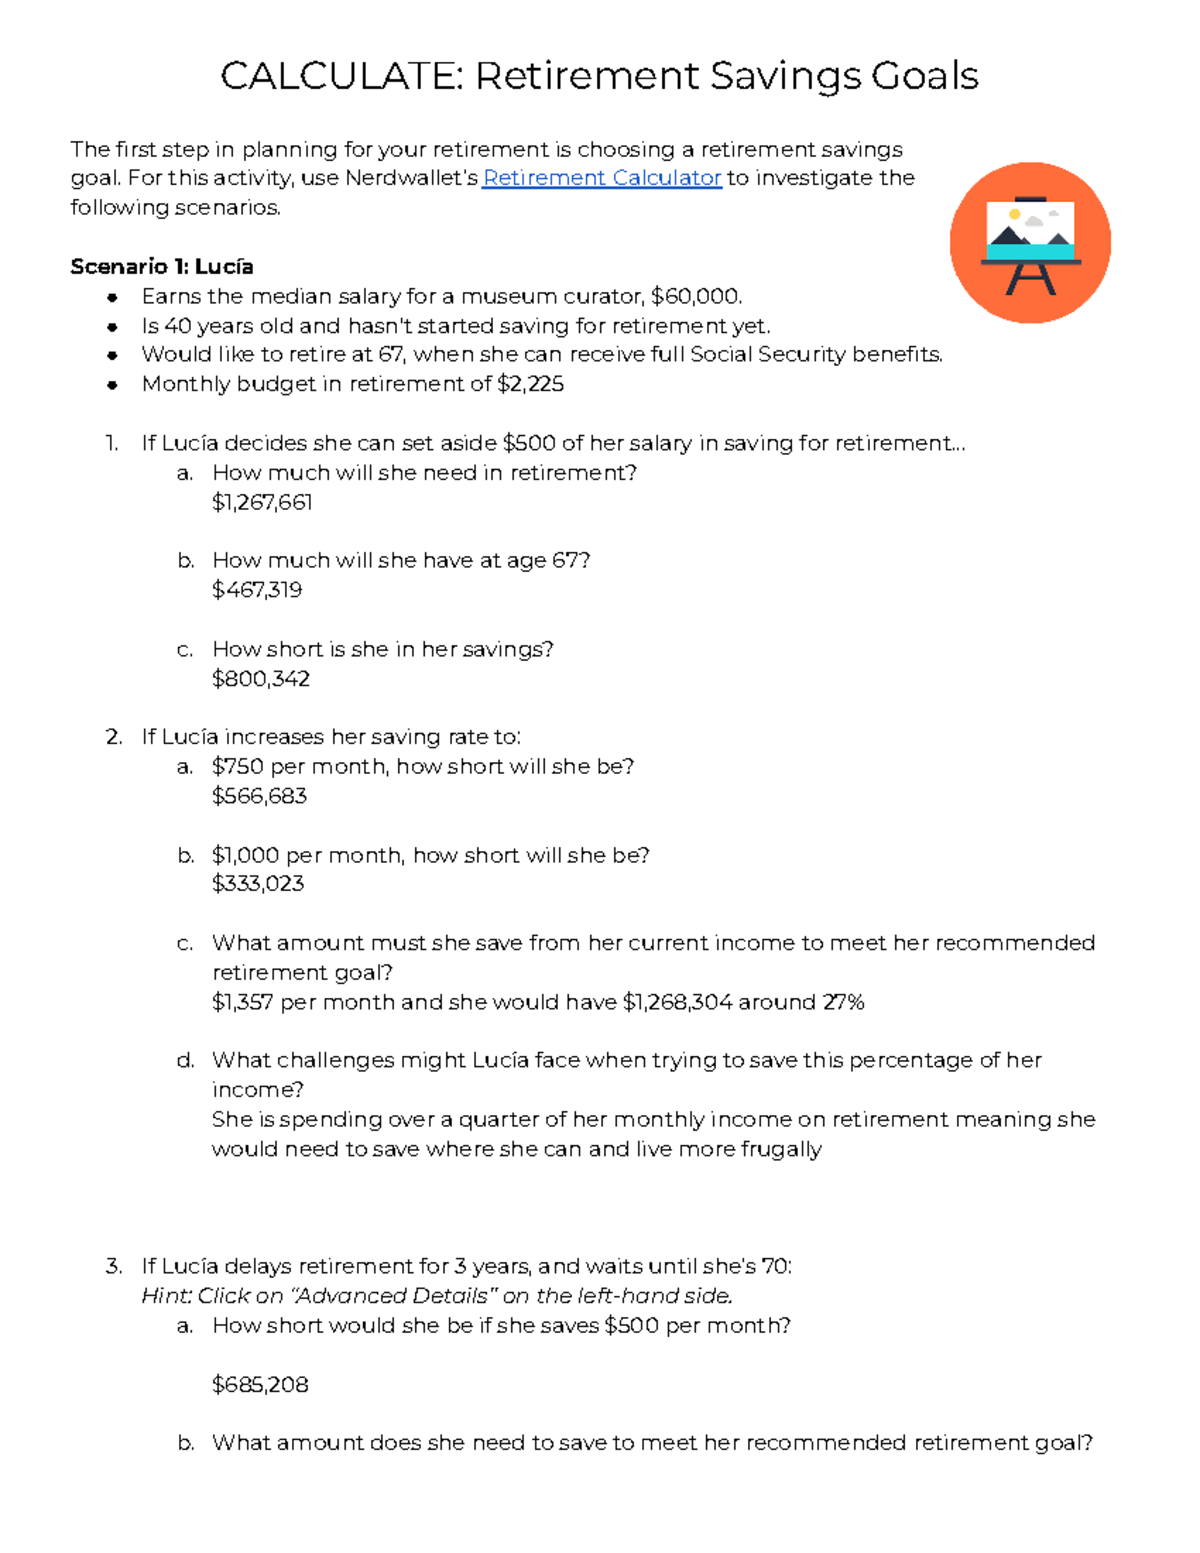
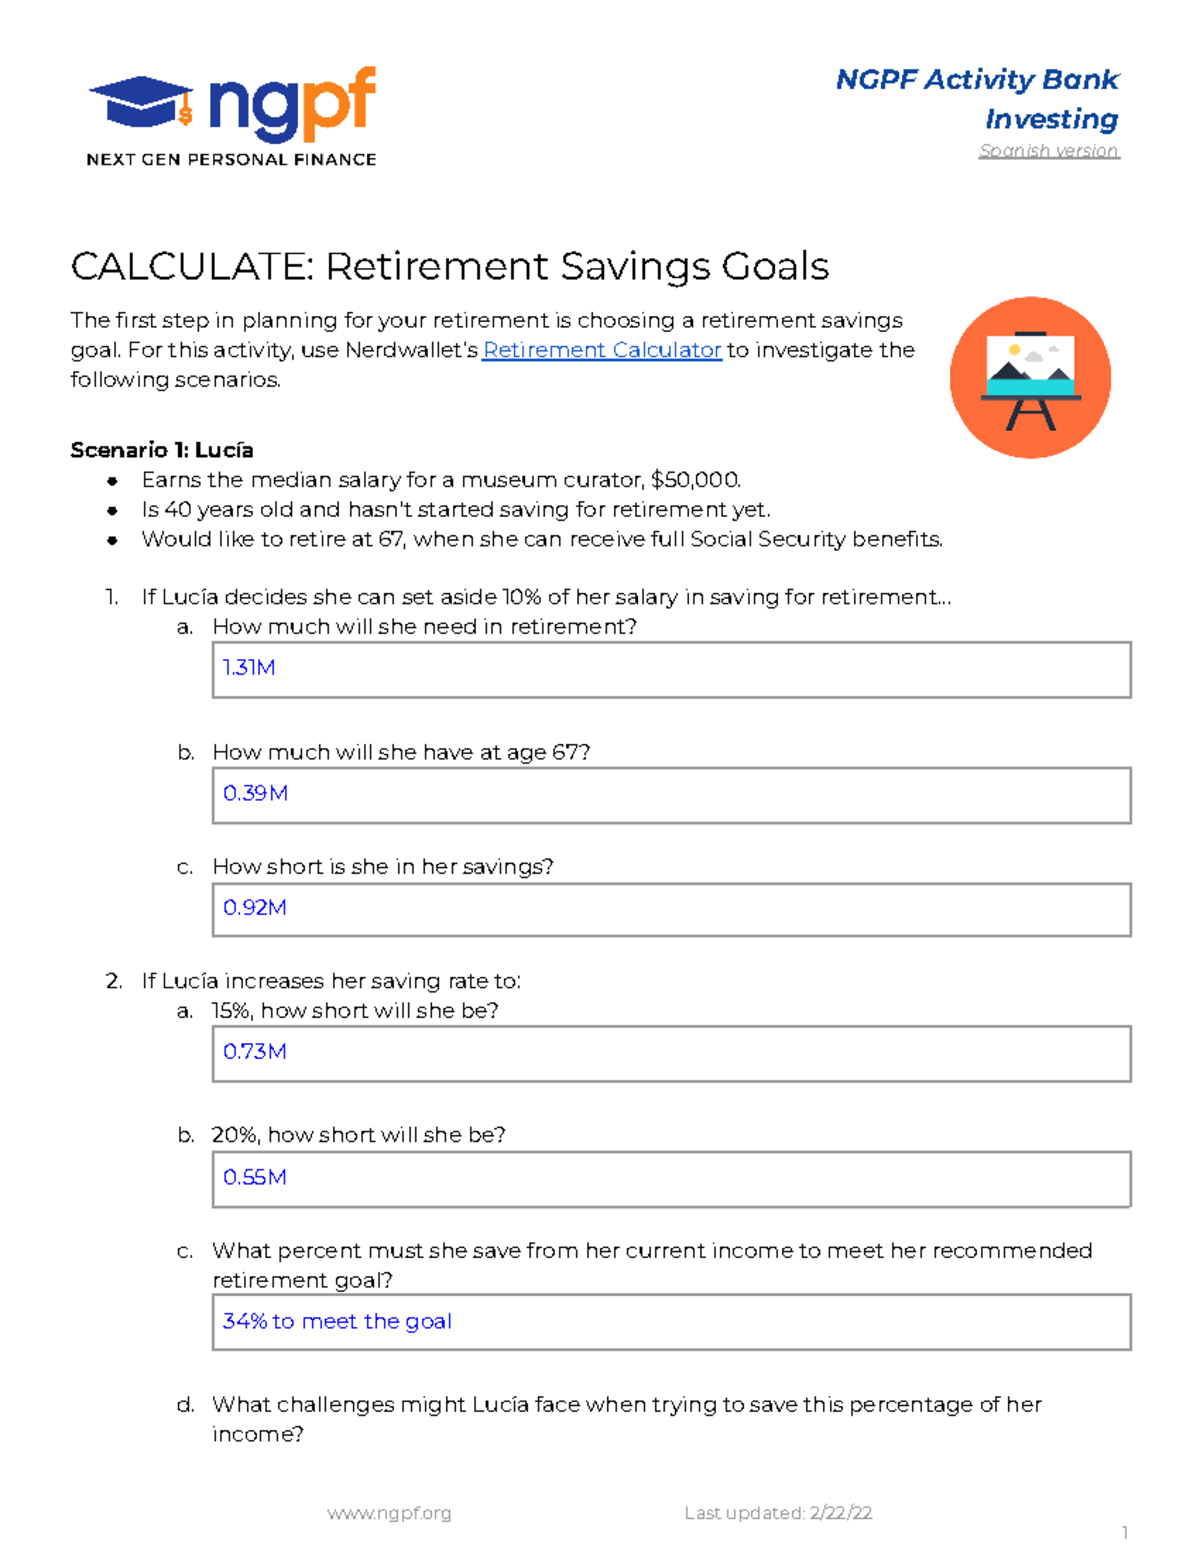
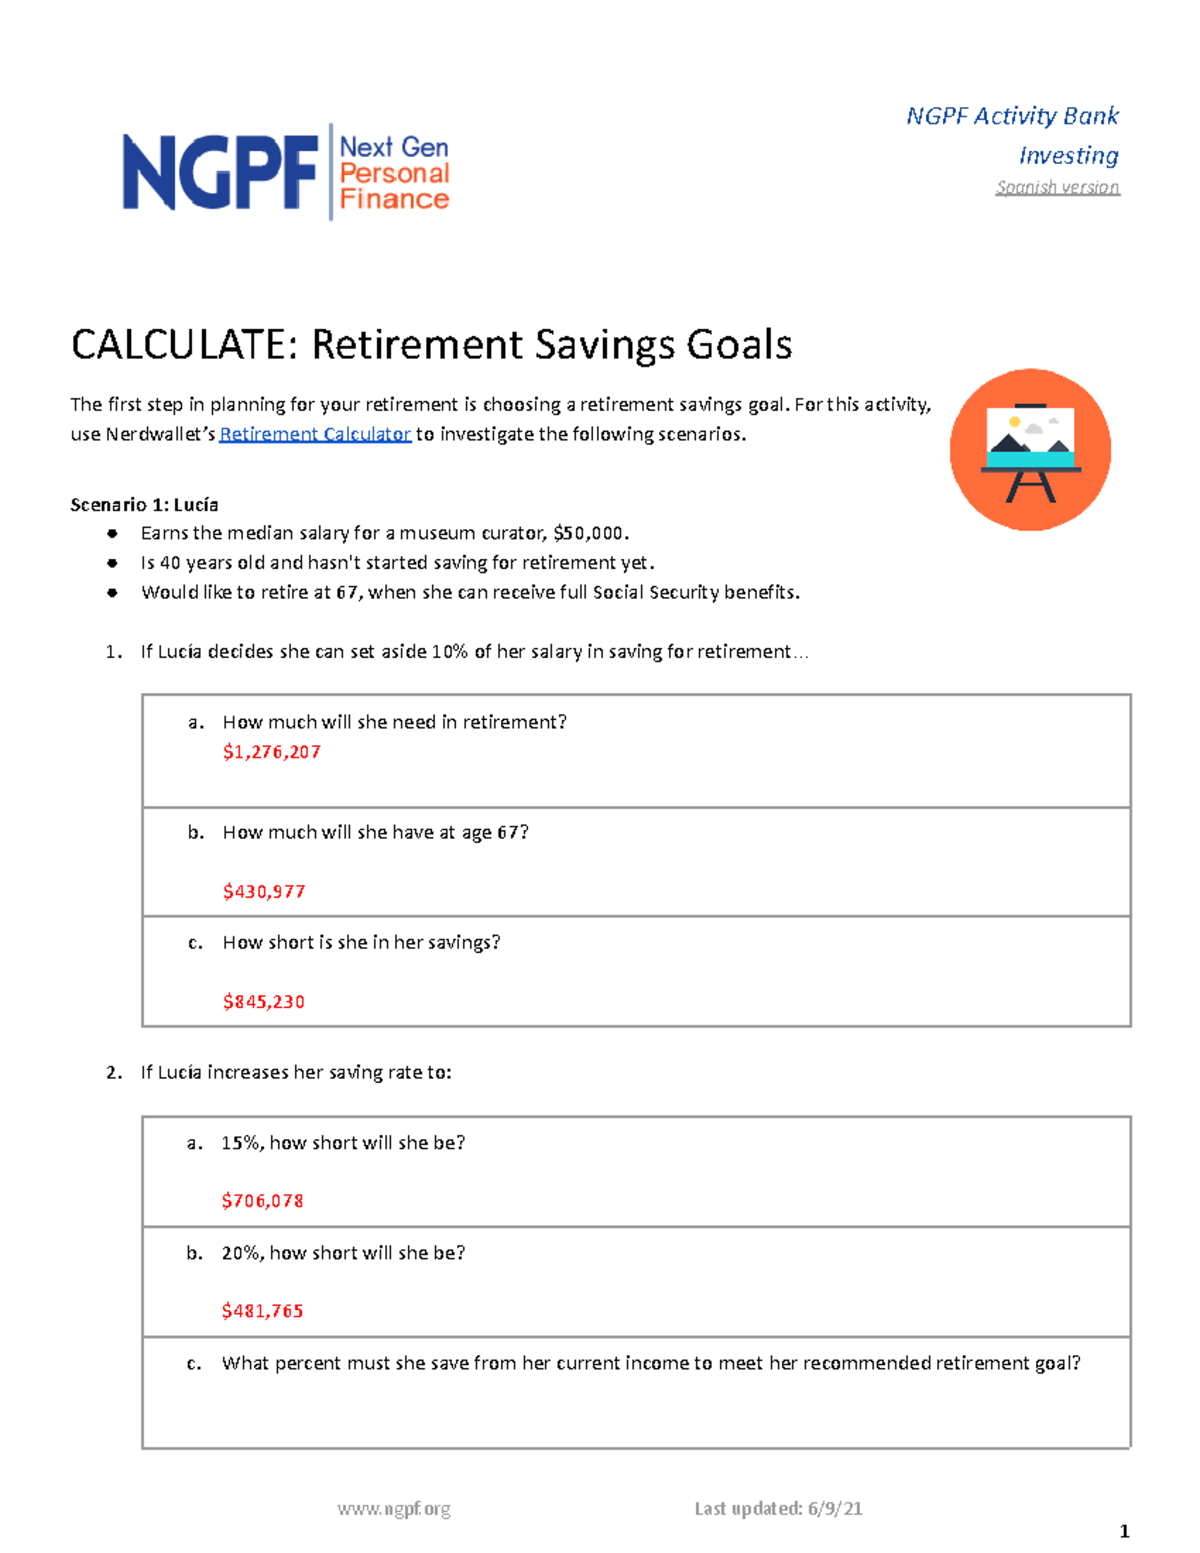
The term Calculate Retirement Savings Goals Answer Key refers to a structured framework or reference sheet that maps the variables you need to plug into a retirement projection model and gives you the resulting target number. Think of it as a checklist that forces you to account for every input that actually moves the needle, rather than leaving half the fields blank and hoping the default values are close enough. The core inputs are current age, desired retirement age, estimated annual expenses in retirement, expected rate of return before retirement, expected rate of return during retirement, inflation assumption, Social Security or pension income, and current portfolio balance. That last one is where most people skip. They enter zero because they have nothing saved yet. That is fine, but it changes the monthly contribution requirement significantly, and you need to see that number to understand whether your current savings rate is anywhere near sufficient. I once worked with a client who had been using a basic online calculator that defaulted his inflation rate to 3 percent and his pre-retirement return to 7 percent. When we rebuilt it with 2.8 percent inflation, 6 percent pre-retirement return, and 5 percent post-retirement return to reflect a more conservative allocation shift, the target savings number jumped from about $1.2 million to roughly $1.85 million. The difference was not a rounding error. It was a structural assumption issue that no default setting caught.
Building a Working Model Step by Step
Start with your expense baseline. Not your income. Your expenses. People consistently overestimate what they need because they conflate current lifestyle spending with retirement spending. Your commute costs disappear. Your work wardrobe budget shrinks. Your children stop needing things you were paying for. On the other hand, healthcare costs rise. Travel might increase. Property taxes do not go away just because you retired. I spent three months tracking a client's actual quarterly spending before we ever opened a retirement projection. The difference between what he thought he spent and what he actually spent was 18 percent. That gap propagated directly into the final number. If you skip the expense audit and just use a rough estimate, your target is likely wrong by enough to matter. Once you have expenses, apply a withdrawal rate framework. The traditional 4 percent rule is a starting point, not a law. For someone retiring in a market environment with lower expected equity returns and higher longevity, a 3.5 percent or even 3 percent initial withdrawal rate is more realistic. This adjustment alone can add six figures to your target. The sequence-of-returns risk in the first five years of retirement makes a conservative withdrawal floor important. A market crash right after you retire can irreparably damage a portfolio that was calculated using optimistic assumptions.
Get the Full Details
Common Pitfalls That Ruin the Output
The most frequent error is ignoring taxes. A portfolio calculated on a pre-tax basis looks adequate until you factor in required minimum distributions and the tax bracket you will be in during retirement. For a client with a large traditional IRA balance and moderate Social Security income, we found that the effective tax drag reduced usable withdrawal capacity by roughly 22 percent compared to a tax-free projection. That meant her portfolio needed to be materially larger than the initial calculation suggested to sustain the same standard of living. Another pitfall is assuming your investment return stays constant across both the accumulation and decumulation phases. Younger savers can reasonably target higher nominal returns because they hold more equities. At retirement, the allocation typically shifts toward bonds and cash equivalents, which lowers expected returns. Using the same rate for both phases creates a false sense of security. Run separate return assumptions for each period. A 6 to 7 percent nominal return during accumulation and 4 to 5 percent during retirement reflects how actual portfolios behave. I had a situation where a client wanted to retire at 62 instead of 65. The calculator output showed she was fine because she had saved aggressively. But when we ran the numbers through age 95 with sequence-of-returns sensitivity testing, the portfolio had a roughly 38 percent probability of being exhausted before death. She ultimately pushed retirement to 64, which dropped the exhaustion probability below 15 percent. The three-year delay changed everything, and the base calculator never flagged it because it did not model lifespan risk.
What to Do When the Number Looks Impossible
If your target savings goal is far out of reach based on current contribution rates, you have three levers: save more, retire later, or adjust expected income sources. Increasing your monthly contribution by $300 can close a significant gap if you are still in your accumulation phase. Delaying retirement by two years has a compounding effect that goes beyond just adding contributions. It reduces the number of withdrawal years and allows your portfolio to grow for two additional years. Lowering your expected retirement expenses through downsizing or geographic arbitrage is the least talked about option but often the most impactful. The framework is only as good as the assumptions you put into it. Build it conservatively. Stress-test it against a couple of bad market scenarios. If the answer still works under those conditions, you have something you can actually rely on. If it does not, you now know what needs to change before you hit the finish line instead of after.