Working Through Shopping With Interest Calculations
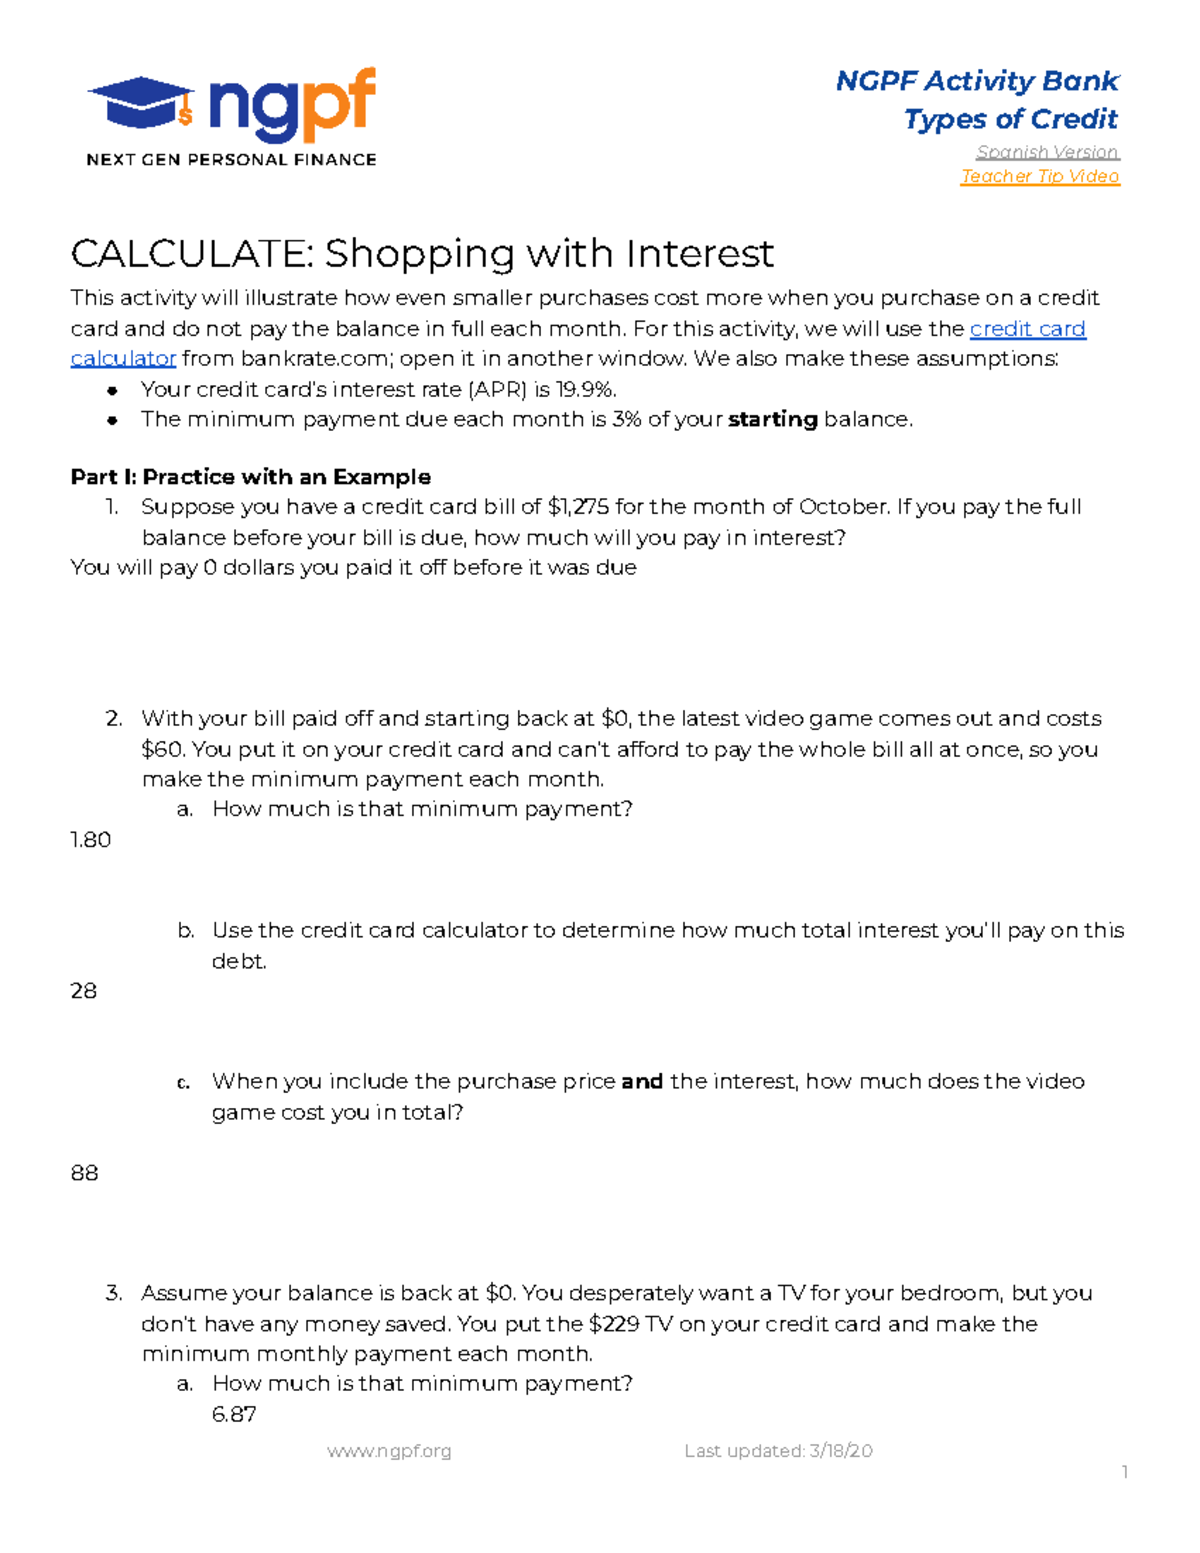
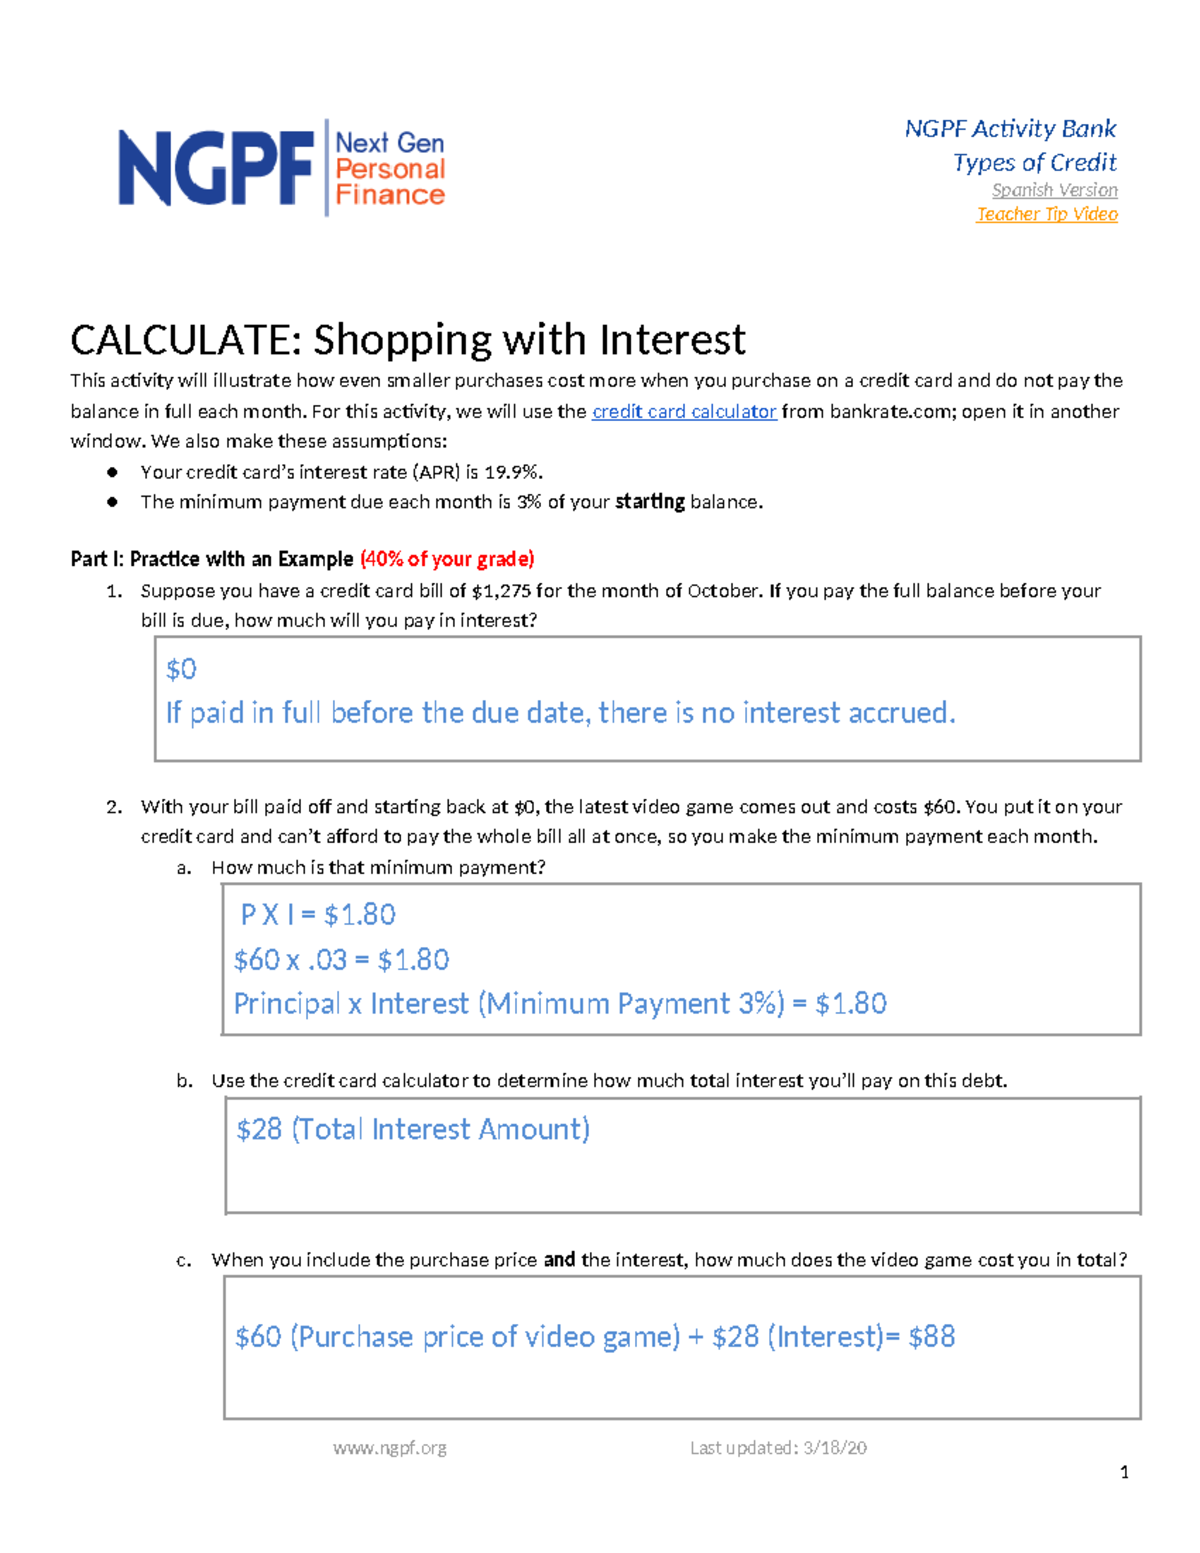
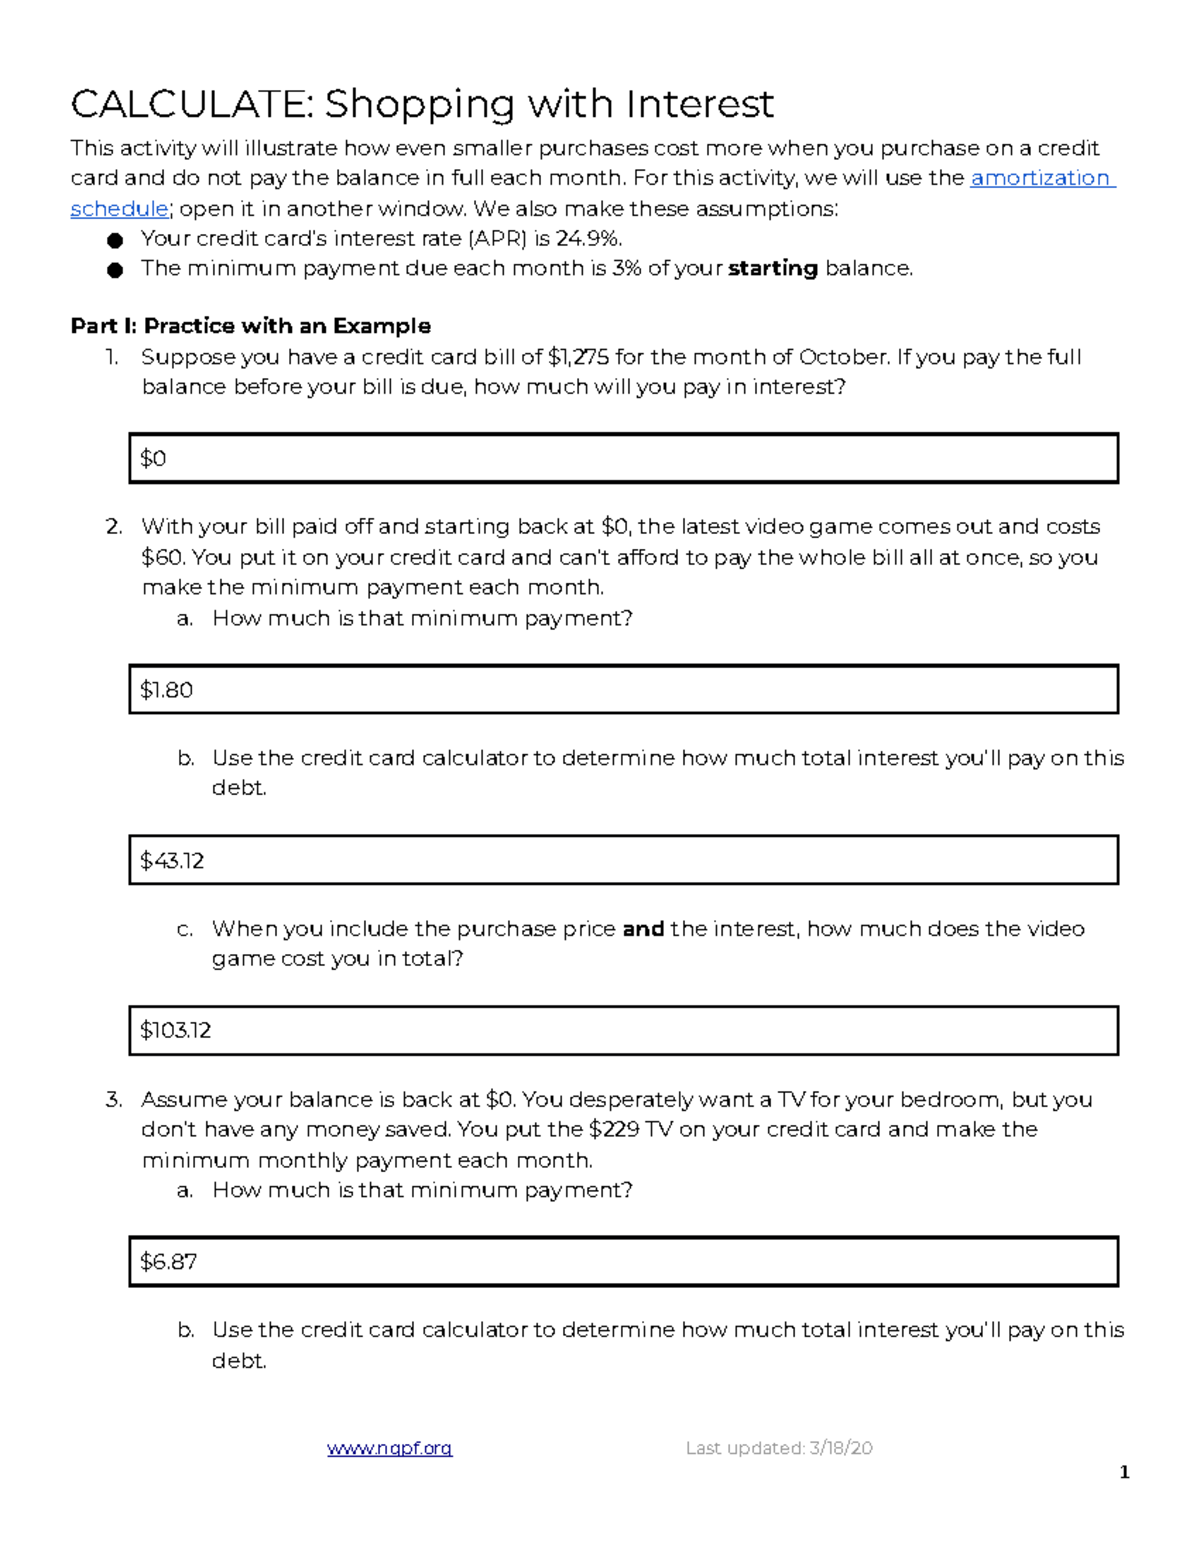
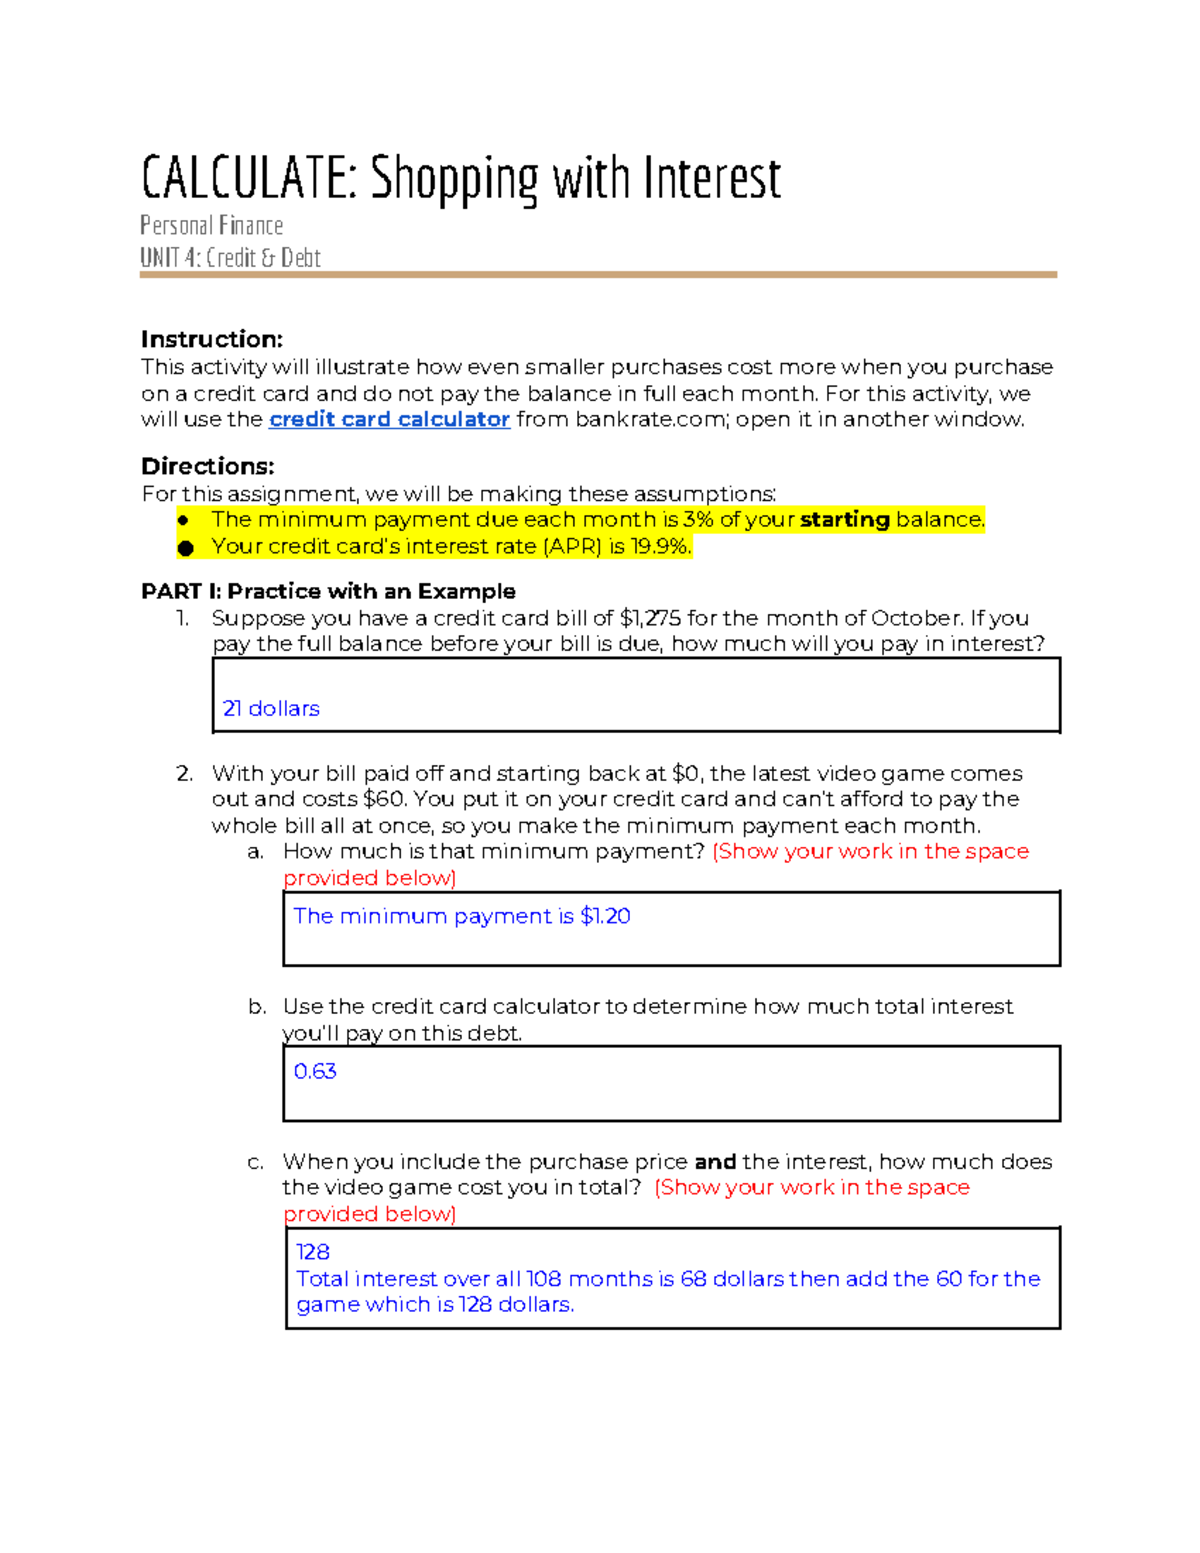
The answers key for shopping with interest problems is one of those things that looks straightforward on paper but gets messy the moment you try to apply it to real numbers. Most people who ask about it are either teachers trying to grade quickly, students stuck on a problem set, or someone actually trying to figure out whether a layaway plan at a furniture store is worth it. The concept itself isn't complicated, but the way it's presented in worksheets often skips the parts that actually matter in practice. The core idea is simple enough: when you buy something and don't pay the full price upfront, you end up paying more because interest accrues over time. The formula most classes use is the simple interest formula, A = P(1 + rt), where A is the total amount owed, P is the principal or starting price, r is the interest rate expressed as a decimal, and t is the time in years. Everything after that is just plugging in the numbers they give you and doing the arithmetic. The answers key will walk through each problem step by step, showing the substitution and the final result.
How to Use the Calculate Shopping With Interest Answers Key
I ran into a specific issue with one of these answer keys recently that wasn't obvious from just reading it. A student had a problem about buying a laptop for $800 with an 8% annual interest rate over 18 months, and the answer key said $920 was the total. When I checked my own work, I got $920 too, but only after realizing the key treated 18 months as 1.5 years. The problem didn't explicitly state the time conversion, and a couple of the other problems in the same set had time given in months instead of years without any hint to convert. That's the kind of thing the answers key assumes you already know, which is annoying when you're still learning it. The practical workaround is to scan every problem for the units on the time variable before you plug anything in. If the rate is annual and the time is in months, divide the months by 12. If the rate is monthly, keep the time in months. Mixing those up is the most common error I see, and it accounts for probably half the wrong answers on these worksheets. Another thing to watch: some keys round at intermediate steps while others round only at the end. On a three-part problem where each sub-question feeds into the next, rounding early can shift your final answer by a dollar or two. I usually do the calculation all the way through and then round at the very end, which is what most of the answer keys seem to follow. Here's a quick walkthrough of how the first few problems typically play out. You have a television listed at $650 with a 6% interest charge over one year. Multiply 650 by 0.06 to get the interest amount of $39, then add that to the principal to get $689. For a two-year problem at the same rate, you'd multiply 650 by 0.06 by 2, giving $78 in interest and a total of $728. The answers key will show both the intermediate interest calculation and the final total, so you can see where your work diverges if it doesn't match.
One counter-intuitive detail that usually trips people up is that simple interest shopping problems don't account for compounding the way real credit cards do. The answers key will give you a clean total based on simple interest, but if you were actually financing a purchase on a credit card with the same rate, you'd owe more because interest compounds on interest. I had someone once compare a worksheet answer to their actual credit card statement and think the textbook was wrong. It wasn't wrong, it was just modeling a different scenario. Knowing the difference between simple interest as presented in these problems and how compound interest actually works on a revolving balance is important, even though most introductory worksheets don't mention it. Another thing that rarely gets covered is the effective cost of installment plans that advertise "no interest." Sometimes those are legitimate zero-percent promotions, but often they're structured so that if you miss a single payment or pay late, the retroactive interest kicks in at a much higher rate. The answer keys for basic shopping with interest problems won't touch on that, but it's worth keeping in mind if you're actually using these calculations to make a purchasing decision rather than just completing homework. There are also limitations to be aware of. These answer keys assume the interest rate stays constant throughout the entire period, which is fine for textbook problems but unrealistic for most real-world financing. They also ignore fees, taxes, and other charges that actually show up on a receipt. A $400 appliance bought on an installment plan might look like it costs $440 according to the interest formula, but after tax and any processing fees it could be $470 or more. The answer key isn't going to include those variables, and that's by design for the level of the course, but it means the numbers you get from the key are an underestimate of what you'd really pay.
Get the Full Details
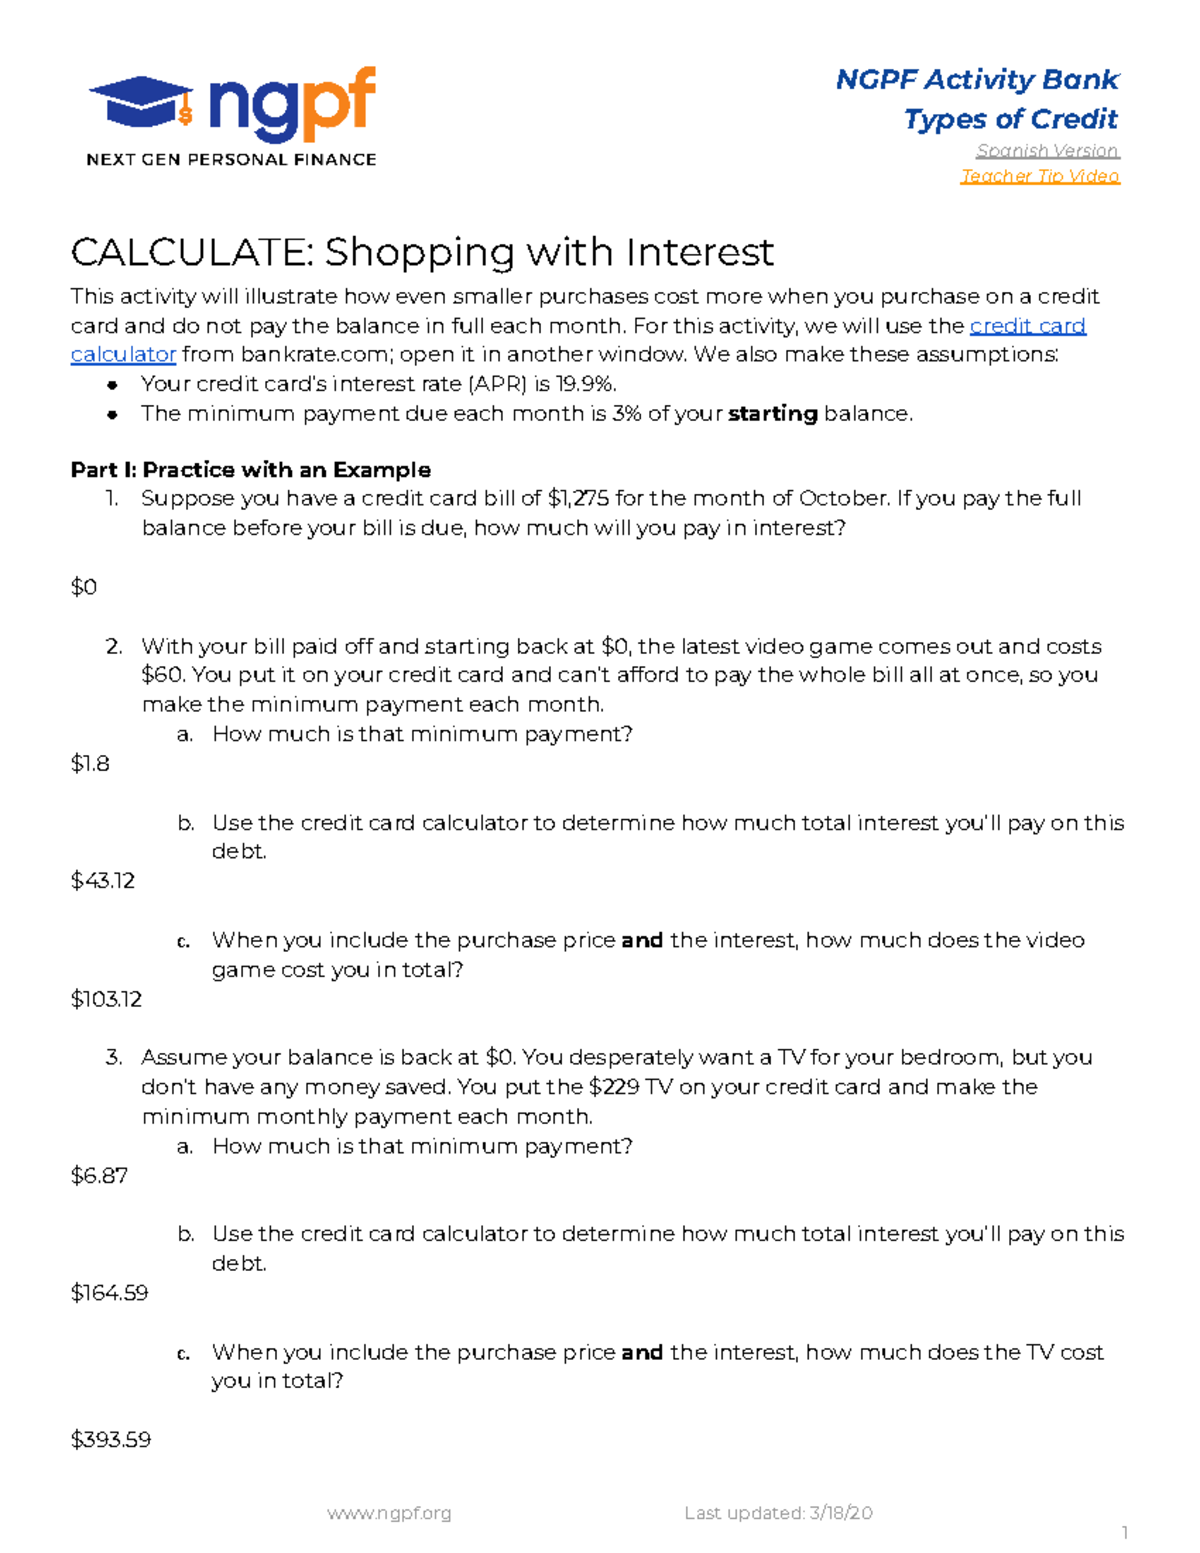
If you're grading these or checking your own work against the key, the fastest approach is to verify the time conversion first, then check whether the rate and time units are consistent, then recalculate the interest amount, and finally add the principal. If all three steps match the key, your answer is correct. If the interest amount matches but the total doesn't, you probably rounded differently. If the time conversion is the issue, it's an easy fix and something to note for the next problem. For a downloadable version of the answers key, most schools and textbook publishers host these on their educator resource pages. Check the publisher's website for the corresponding textbook chapter, usually under a section labeled something like "Teacher Resources" or "Answer Keys." The PDFs are generally free and just require a login if your school has a partnership with the publisher. Third-party sites sometimes host these too, but the versions from official sources are more likely to match your edition exactly, which matters because different printings sometimes renumber or slightly modify the problems. At the end of the day, the answer key is a tool for checking your work, not a substitute for understanding the underlying calculation. If you can redo each problem without looking at the key and get the same result, you've got the material. If you're only able to match the answers by reverse-engineering them, it's worth going back through the problems with a fresh copy of the formula and working each one from scratch. That's usually where the gaps show up.