
Getting the Mortgage Interest Deduction Right Without Losing Your Mind
The mortgage interest deduction is one of those tax benefits that sounds straightforward until you actually sit down to work it out. You paid interest on a loan secured by your home, so you can deduct some of it from your taxable income. That's the elevator pitch. The actual mechanics involve a few specific forms, some limits that changed with the 2017 tax reform, and a bunch of edge cases that trip people up every single filing season. I've been filling out these returns for longer than I care to admit, and I still get caught by the same traps. The main one most people miss is that the deduction only applies if you itemize. If you're taking the standard deduction, which about 90 percent of taxpayers do now that the standard amounts nearly doubled, the mortgage interest deduction is irrelevant to you for that tax year. It doesn't disappear entirely though — unused itemized deductions don't roll over, but the interest paid still matters for other purposes like calculating your basis or determining capital gains when you sell.
Calculate Tax Deduction On Mortgage Interest Step by Step
Here's the actual workflow. First, you need your Form 1098 from your mortgage lender. This form reports the interest you paid during the year, plus any points refunded at closing, your mortgage balance at the end of the year, and the date the mortgage was originated. If you have more than one mortgage, you'll get multiple 1098s. Add up the interest from all of them — that's your starting number. Next, check whether your total itemized deductions exceed the standard deduction for your filing status. For 2024, the standard deduction is $14,600 for single filers and $29,200 for married filing jointly. If your itemized deductions — mortgage interest, state and local taxes capped at $10,000, charitable contributions, and medical expenses over 7.5 percent of AGI — don't beat that threshold, there's no point claiming the mortgage interest deduction. You're just doing extra work. If you do itemize, the mortgage interest goes on Schedule A, line 8d for acquisition debt interest and line 8e for home equity debt interest. The distinction matters because the rules differ. Acquisition debt — money used to buy, build, or substantially improve your home — can go up to $750,000 in principal for mortgages taken out after December 15, 2017. That's the TCJA limit. For older mortgages, the cap is $1 million. Home equity debt interest is trickier because under current law, interest on home equity loans is only deductible if the proceeds were used to buy, build, or substantially improve the taxpayer's home that secures the loan. Just having a HELOC doesn't automatically make the interest deductible. I've seen too many people assume their home equity loan interest is fully deductible when it's not, and that creates problems during an audit.
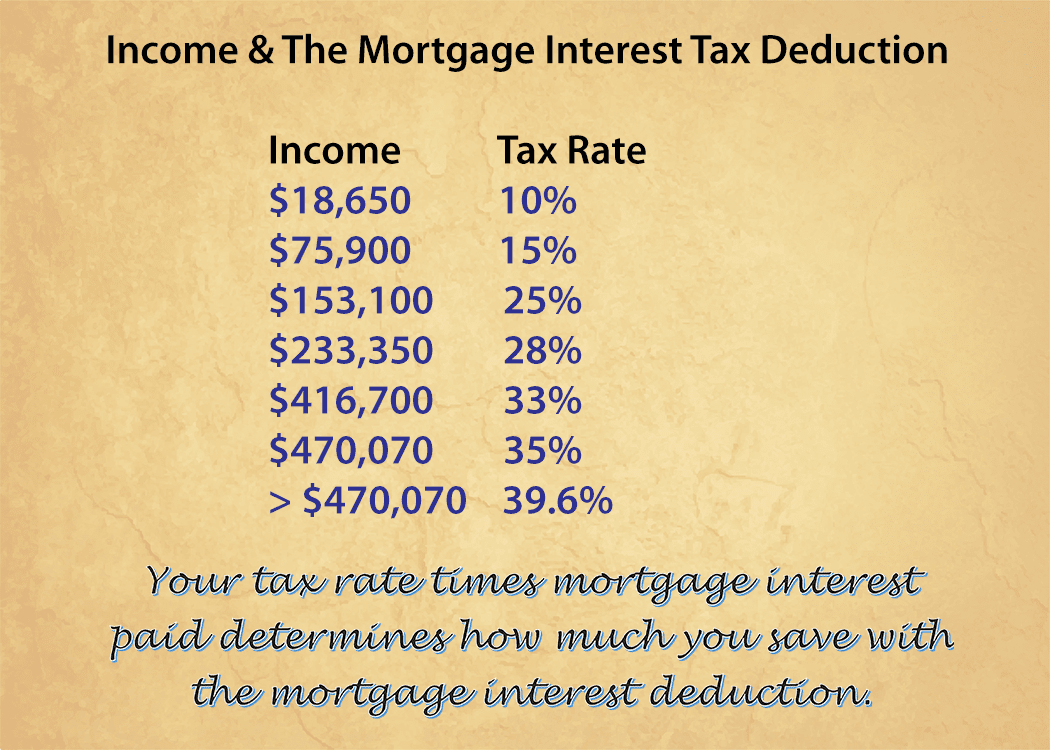
One practical note about points. If you paid discount points on your mortgage, those are generally deducted over the life of the loan unless they meet specific requirements for full deduction in the year paid. The requirements are: the loan must be secured by your main home, the charging of points must be an established business practice in your area, the points charged can't exceed the points generally charged in your area, and the funds you provided at closing must have been at least 1 percent of the loan amount. I had a client once who paid points on a refinanced investment property and tried to deduct them all in year one. The IRS disallowed the bulk of it. Points on a refinance have to be amortized over the life of the new loan regardless of whether the original mortgage rules are met. After you figure out the allowable amounts, you enter them on Schedule A and carry the total itemized deduction to your Form 1040. The actual tax savings depends on your marginal tax rate. If you're in the 22 percent bracket and you deduct $8,000 in mortgage interest, you save $1,760 in federal taxes. Simple math, but people rarely calculate the real after-tax cost of their mortgage, which is a useful metric for comparing refinancing options.
Get the Full Details
Common Pitfalls and What to Watch For
There are a few situations where the calculation gets messier. If you owned a home before 2018 and your mortgage was above $750,000 but below $1 million, you're grandfathered under the old rules. The limit stays at $1 million for acquisition debt on that original mortgage, but any new borrowing after 2017 falls under the $750,000 cap. Mixing old and new debt requires careful tracking, and lenders don't always provide that breakdown on the 1098. Another thing that catches people off guard is rental property mortgage interest. That's not a Schedule A deduction. Rental interest goes on Schedule E and offsets rental income. Mixing these two up is a common error that shows up on a lot of returns I review. The interest itself is the same kind of expense, but the tax treatment is completely different depending on whether the property is your personal residence or a rental. Then there's the issue of mortgage credit certificates and the interaction with the deduction. If you have a MCC, you can claim a dollar-for-dollar credit for a portion of the interest paid, but you also have to reduce your itemized deduction by the amount of the credit. The mechanics are on Form 8396, and getting the interaction wrong can either overstate or understate your liability. I worked a return last year where a taxpayer had a MCC and claimed the full mortgage interest deduction without any reduction. The IRS sent a correction notice within six months. These programs are worth using if you qualify — the credit can be substantial — but they require extra attention.
The deduction also doesn't apply to the first $600 of reported forgiven mortgage debt on certain qualified principal residence indebtedness. The Coronavirus Aid, Relief, and Economic Security Act extended this provision through 2025, but it's expired for debts forgiven after that date. If you had debt relief in 2026 or later, that forgiven amount is generally taxable income, and you can't offset it with a mortgage interest deduction because the underlying debt no longer exists. One more practical consideration: if you sell your home, the mortgage interest you paid during the year of sale is still deductible on your personal return, but the gain on the sale is handled separately under the capital gains exclusion rules. The two calculations are independent. I see people conflate them sometimes, thinking that because they excluded the gain from taxable income, the interest doesn't count. It absolutely counts. The interest deduction and the home sale exclusion operate in completely separate parts of the tax code. The bottom line is that Calculate Tax Deduction On Mortgage Interest isn't particularly difficult if you understand which category your debt falls into and whether itemizing makes sense for your situation. The hard part is keeping track of multiple loans, understanding the grandfathering rules, and catching the edge cases where the deduction simply doesn't apply. Most people who bother with this will get it right by staying disciplined about the source and use of the borrowed funds. The IRS isn't trying to trick you here. They just expect you to know the rules.


