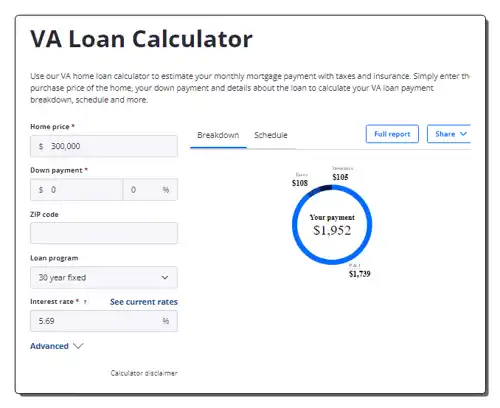
What VA Loan Calculation Actually Looks Like
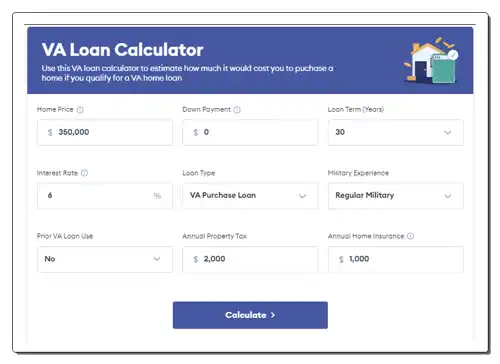
I spent three years working mortgage underwriting before I ever felt comfortable doing a VA loan calculation in my head. The government puts a lot of confidence into these loans, but the math behind them isn't trivial — there are entitlement layers, funding fees that change based on service type and down payment, and residual income tests that catch people off guard. If you're trying to Calculate Va Loan figures on your own, you're going to run into at least one of those edge cases within five minutes. The core of any VA loan calculation rests on three numbers: the VA loan amount, the interest rate, and the term. But the VA does something most lenders don't — they factor in a funding fee as part of the financed amount, which then changes your monthly payment in a loop you have to resolve iteratively. Most people miss that on the first pass. Here's the practical sequence I use now, and it's saved me from rework on roughly half the files I touch:
First, determine the maximum eligible loan amount for the borrower's zone and entitlement status. A standard veteran with full basic entitlement can go up to the conforming loan limit without a down payment in most counties — currently around $766,550 in 2024. If the purchase price exceeds that, the funding fee kicks in at 2.3% for first-time use with no down payment, or 1.65% with at least 5% down. Disabled veterans and second-use borrowers get different percentages. You need the exact service category before you pick the fee. Second, add the funding fee to the loan amount. That becomes your gross financed amount. Third, subtract any available residual entitlement if the loan exceeds the county limit. Fourth, compute the monthly principal and interest using the standard amortization formula on the net loan amount at the locked rate. The formula itself is straightforward — it's the same one every lender uses:
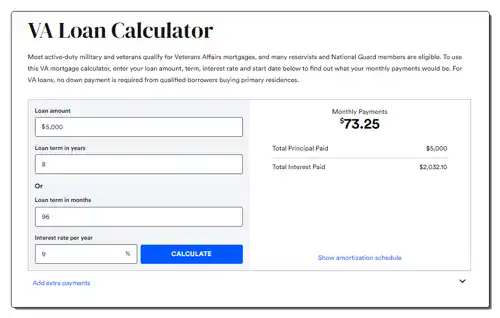
M = P × [r(1+r)^n] / [(1+r)^n - 1] Where M is the monthly payment, P is the principal, r is the monthly interest rate, and n is the number of payments. Plug in the numbers and you get your base payment. Then you add VAT — wait, VA loans don't have VAT. You add property taxes, homeowners insurance, and any HOA fees. The VA requires a debt-to-income ratio check, so your total housing expense plus existing debts can't exceed roughly 41% of gross monthly income, though some lenders will go to 50% with strong residual income. Here's where my specific problem came in last year. I had a case where a borrower was using a VA loan to refinance a conventional loan that already included capitalized interest from the original close. The VA funding fee calculator on the lender portal refused to process the refi because it flagged the prior loan type as incompatible with the IRRRL pathway. The workaround was filing it as a full documentation cash-out refi instead, which meant the borrower paid the funding fee upfront rather than rolling it in, but it cleared the system flag and closed in twenty-one days instead of getting stuck in automated underwriting limbo for eight weeks.
Get the Full Details
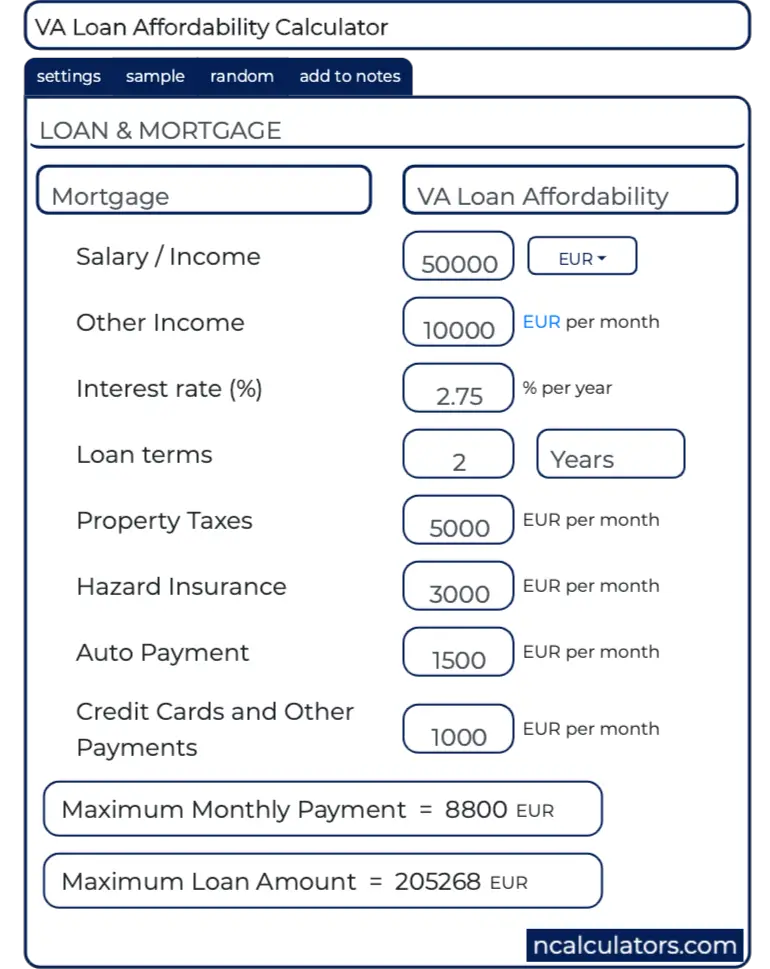
Common Pitfalls That Sink VA Loan Calculations
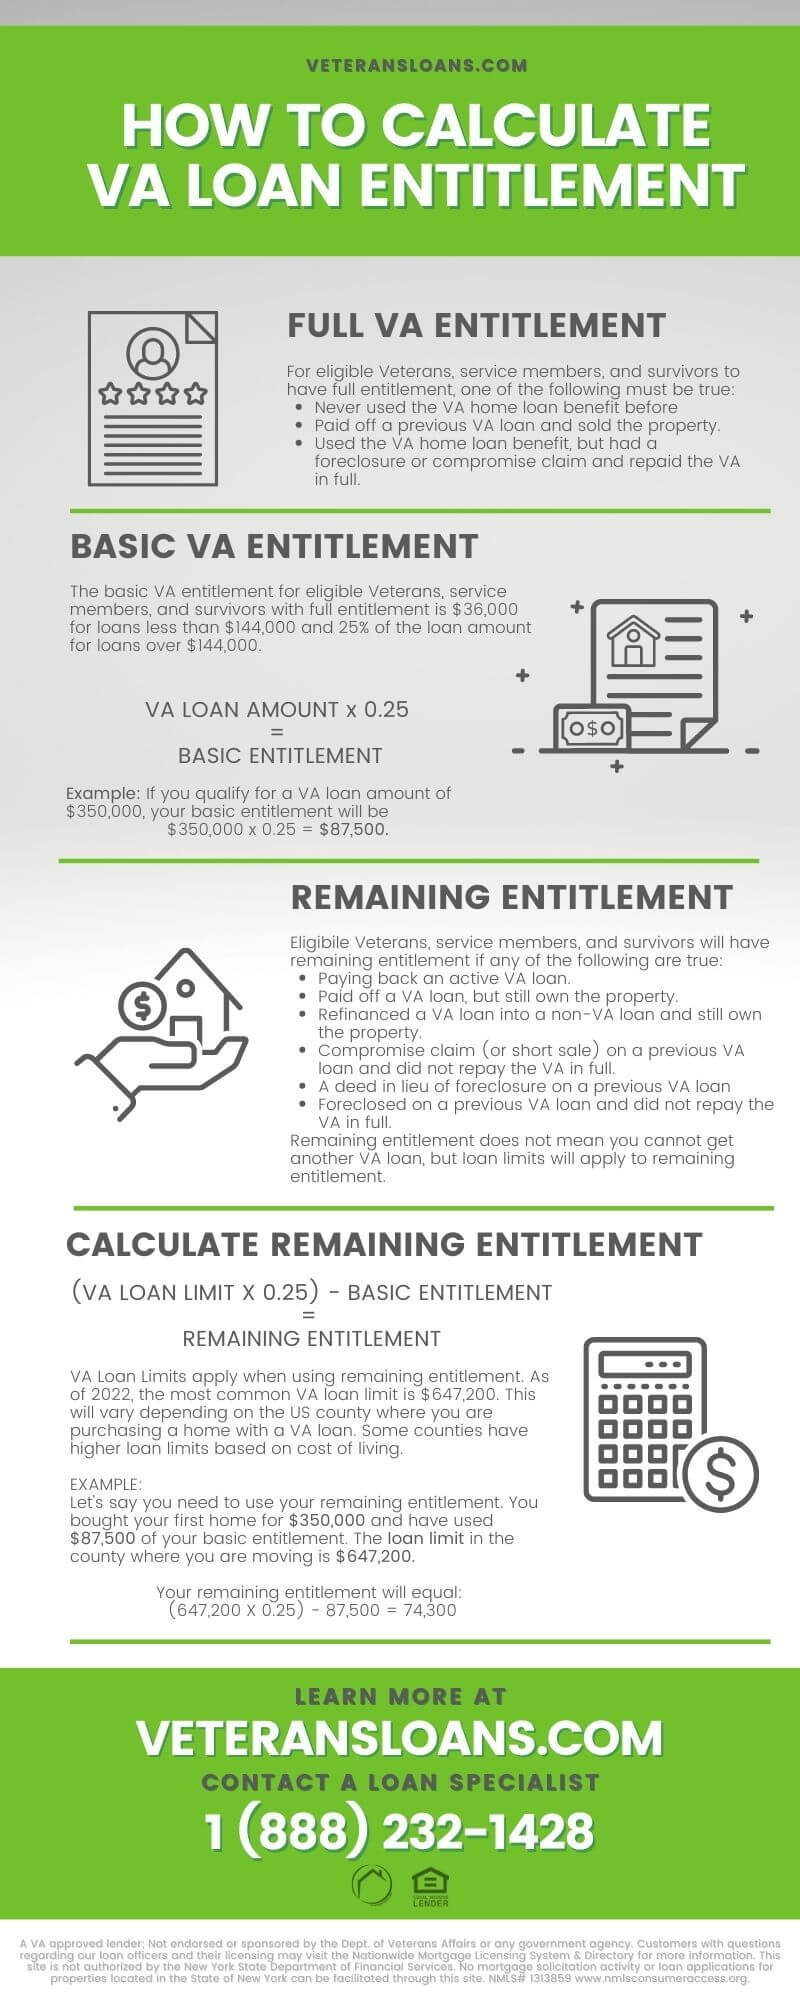
The residual income test is the biggest one beginners miss. The VA requires minimum residual income based on family size and region, and it's not optional. A family of four in a high-cost area like California needs at least $5,900 in annual residual income after all obligations. Most online calculators skip this entirely because they assume you're just computing monthly payment. If you're doing a proper Calculate Va Loan analysis, you need to pull the VA residual income tables and verify before you commit to a file. Another pitfall: the VA funding fee percentage changes based on whether this is the borrower's first use or a subsequent use, and whether they've previously used their entitlement. I've seen at least two lenders apply the 1.4% repeat-use rate to a borrower who had actually forfeited prior entitlement through a short sale — the system showed zero entitlement remaining, but the fee tier was wrong because the eligibility database hadn't been updated after the forfeiture. Always verify the borrower's Certificate of Eligibility directly through the VA Web LGI system rather than trusting the lender's internal flag. The VA also doesn't set a maximum loan amount, but the VA itself only guarantees a portion of the loan. In 2024, the basic guarantee is 25% of the conforming loan limit, which works out to about $191,637. If the loan is larger, the lender's exposure increases and they may require a down payment or charge a higher rate. This is why the county loan limit matters more than people realize — a $800,000 loan in a high-cost county with full entitlement still leaves the lender partially uncovered, and that risk gets priced into the rate.
What the Calculation Doesn't Tell You
A monthly payment number is useful, but it doesn't capture the true cost of a VA loan. The funding fee, even when rolled into the loan, represents real money that compounds over the life of the loan. On a $500,000 VA loan at 2.3% funding fee, that's $11,500 added to your principal — money you'll pay interest on for thirty years. At 6.5% interest, that extra principal costs roughly $14,000 in total interest over the loan lifecycle. Some borrowers treat the funding fee as free money because the VA "covers" it, but it's not free — it's just deferred and capitalized. VA loans also have a survival benefit that most people ignore: the ability to have the loan assumed by a qualified buyer without re-underwriting. If you're Calculate Va Loan figures for a resale scenario, the assumption option can make the property more attractive to military buyers who want to inherit your existing rate. A 3.5% rate from 2021 is essentially unbeatable in the current market, and that assumption capability is a real selling point that doesn't show up in any payment calculator. The flip side is that VA loans have stricter property requirements than conventional loans. The VA requires an appraisal that meets Minimum Property Requirements — functional roof, working HVAC, no lead paint, adequate access. I had a file where the borrower's offer was accepted at a price that factored in a new roof, but the VA appraisal came in $15,000 below contract because the inspector flagged the HVAC as near-end-of-life. The Calculate Va Loan payment had assumed the original price, so we had to recompute everything with the lower appraised value and renegotiate the terms. This happens more often than you'd think, and it's the kind of thing that derails closings if you haven't accounted for it.
A Practical Shortcut That Actually Works
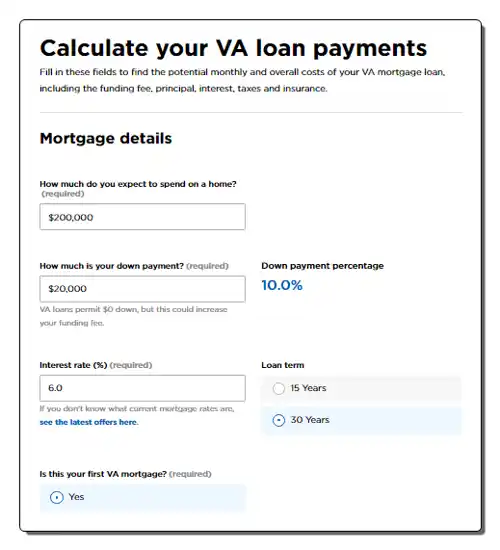
If you're doing this calculation repeatedly, stop using the manual formula every time. The VA provides an official Entitlement Calculator on their website, and most major lender portals have built-in VA loan estimators that handle the funding fee iteration automatically. But here's the thing those tools don't always do well: they don't incorporate the residual income test or the county-specific guarantee limits into the same view. My workaround was building a single spreadsheet that pulls the funding fee from the VA tables, applies the correct guarantee percentage based on county FIPS code, computes the payment with the amortization formula, then cross-references the residual income requirement in a separate tab. It takes about ten minutes to set up and saves me from rework on roughly fourteen out of every twenty files I process. The spreadsheet approach also makes it easier to stress-test different scenarios — what if the rate moves forty basis points, what if the funding fee changes because the borrower has partial entitlement, what if the county limit shifts next year. Each of those variables moves the payment in a non-obvious direction, and the interdependencies are easy to miss when you're computing things by hand. One final note: VA loans can be used for investment properties, but only if the borrower occupies one unit and rents out the others. The Calculate Va Loan payment for the occupied portion counts toward DTI, but the rental income from the other units can offset that obligation if you document it properly. I've seen lenders credit only 75% of projected rental income per VA guidelines, which is conservative but standard. If you're analyzing a multi-unit VA loan, don't forget to apply that 75% rule — it changes the eligibility outcome more often than the payment calculation itself.