Where Most People Mess Up When They Run Their Numbers
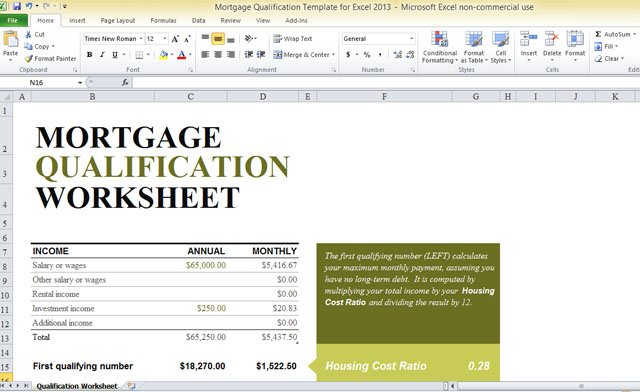
I've watched people bring me pay stubs that are three months old, commission statements that don't match their W-2s, and bonus projections they wrote on a napkin. Mortgage underwriting doesn't care about any of it. The process of Calculating Income For Mortgage Qualification is one of the most mechanical things in lending, which sounds like a compliment until you realize how unforgiving it is. You begin with gross monthly income before taxes, before deductions, before any of the noise. Lenders use the gross number because they're not evaluating your lifestyle. They're evaluating your ability to pay principal, interest, taxes, and insurance. Everything else is secondary. Multiply your annual salary by twelve if you're W-2. Divide it by twelve if you get paid bi-weekly or semi-monthly. The math itself isn't the problem. Getting the right number into the right box is where everything breaks down. I had a borrower once who was a shift supervisor making base salary plus overtime. She had worked sixty hours a week for the past eighteen months. The overtime showed up on every check. She assumed it was countable income. It was, but only because she had documented it for two full years. Had she switched jobs three months earlier and lost the overtime history, her qualification amount would have dropped by roughly two thousand dollars per month. That's the kind of thing nobody thinks about until the file is already in processing.
What Counts as Stable Income
Base salary from a W-2 job counts fully. Hourly wages count at the current rate if the employment history is at least two years. Bonuses and commission require two-year averages and must be something recurring, not a one-time event. Self-employment income uses Schedule C from your tax returns, and the underwriter is going to look at both years, taking the lower number if the trend is declining. Social Security, pensions, retirement distributions, and child support all have their own documentation requirements, but they're generally straightforward if the paper trail exists. The tricky part is variable income. A salesperson with a good year and a bad year in the same job still averages those numbers across the two-year window. A freelance graphic designer with wildly inconsistent monthly earnings might have that income smoothed by the underwriter, or it might get discounted depending on the lender's overlays. Overlays are lender-specific requirements that go beyond what Fannie Mae or Freddie Mac mandates. A conventionally underwritten loan might accept your documented income at face value, but the bank's overlay could require a higher credit score or a lower debt-to-income ratio just because they don't like your industry.
The Debt-to-Income Ratio Problem Everyone Ignores
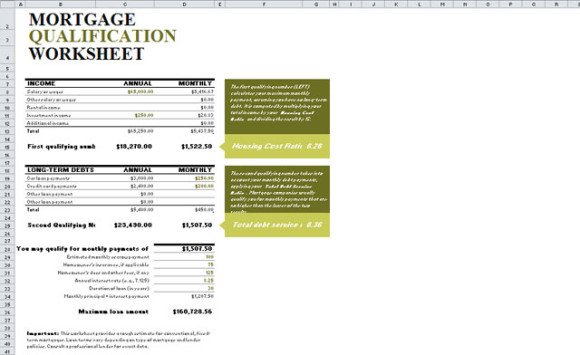
Calculating your income is only half the equation. The other half is how much debt you're already carrying, and most people dramatically underestimate this. The debt-to-income ratio, commonly called DTI, is the filter that actually determines whether you qualify. You divide your total monthly debt obligations by your gross monthly income. Front-end DTI looks at housing costs alone. Back-end DTI includes everything. Most lenders want the back-end number below forty-three percent, though some will go to fifty percent depending on credit score and reserve requirements. Here's what people miss. Auto leases count as monthly debt even if you're three payments away from owning the car. Minimum credit card balances count, not what you actually owe. Student loans with income-driven repayment plans get calculated using either the actual payment or one percent of the outstanding balance, whichever is higher. Undergraduate loans that are in deferment still show up. The underwriter is not going to remember that you paid off your car six months ago unless you provide proof, and even then, some systems auto-populate debt from credit reports and pull it back into the calculation months later during automated underwriting. I've seen files flagged twice for the same car loan because the data came from two different sources and neither cross-referenced properly.
Get the Full Details

Common Pitfalls in the Calculation
The first pitfall is double-counting income. If you and your spouse both work, each person's gross monthly income goes into the calculation, but only if the income is expected to continue for at least three more years. Temporary income, seasonal income that won't recur, and income from a second job that the borrower has announced they're leaving get excluded. The second pitfall is omitting existing debt that shows up on the credit report. People routinely forget about student loans from college, old auto loans, or a line of credit they opened and never used but never closed. The third pitfall is assuming that a larger income automatically means a larger mortgage. It doesn't. A six-figure salary with two car leases, a private school payment, and a five-figure credit card balance will often qualify for less than someone making half that with no debt. I ran into a case last year where a borrower made excellent income as a contract consultant, but his 1099 forms showed income that fluctuated between forty thousand and one hundred twenty thousand dollars across three years. The underwriter averaged the two most recent years and landed him at roughly seventy-five thousand annually, then applied a standard reduction because the income wasn't guaranteed. He was qualified for a house he'd already gotten emotionally attached to, but the paperwork cut his purchasing power by nearly one hundred fifty thousand dollars compared to what he thought he could afford. The workaround was to bring on a co-borrower with stable W-2 income and use the combined profile for qualification. It wasn't ideal, but it got the deal done.
Where the Process Breaks Down Completely
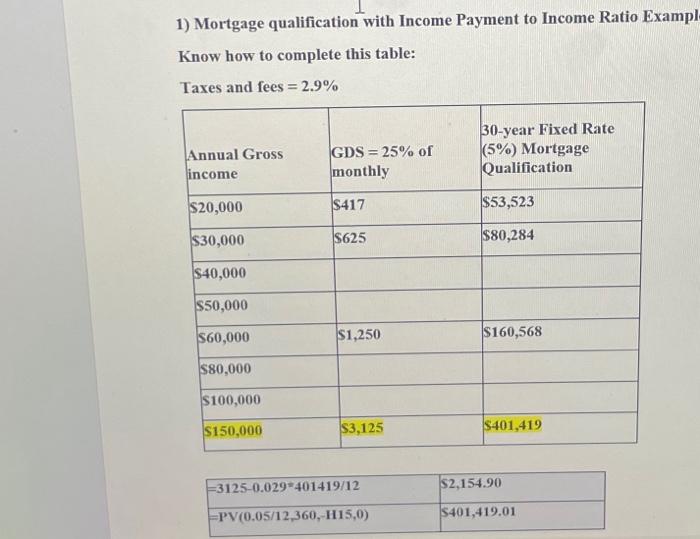
This method fails when you have irregular income with no two-year history. Gig economy workers, recently promoted employees, and people between jobs simply cannot use the standard calculation. There's no workaround that makes Fannie Mae accept what it won't accept. You can try non-QM loans, which use different underwriting standards and often accept bank statement qualification instead of traditional income documentation. Those loans carry higher rates and larger down payment requirements, usually seven to twenty-five percent depending on the program. Self-employed borrowers sometimes benefit from adding back depreciation and amortization expenses to their Schedule C income, which artificially inflates their qualifying income. The IRS didn't include those expenses to help you buy a house. The underwriter is just using accounting flexibility that the tax code already provides. The front-end DTI ratio deserves a specific note. Some people focus exclusively on their back-end ratio and miss that the housing payment itself is being measured separately. If your monthly housing payment including property taxes, homeowners insurance, and HOA fees exceeds twenty-eight percent of your gross monthly income, you may still fail qualification even if your total DTI looks acceptable. I've seen this disqualify otherwise strong applicants multiple times because they were looking at the wrong percentage.
Practical Steps to Run Your Own Numbers Before You Apply
Gather your most recent thirty days of pay stubs. Pull your W-2s from the past two years. Get your tax returns if you're self-employed. Pull a credit report and circle every account that shows a monthly payment. List every lease, loan, and recurring obligation. Calculate your gross monthly income by averaging your take-home plus pre-tax deductions from your pay stubs, or by dividing your annual salary by twelve. Calculate your total monthly debt by adding every minimum payment from your credit report plus your projected housing payment. Divide total monthly debt by gross monthly income. If the result is above forty-three, you need to either reduce debt, increase income, or adjust your expectations about the purchase price. Running these numbers yourself before you talk to a lender saves about two hours of back-and-forth because most of the time I spend with clients who already did this exercise is correcting their math rather than doing it for the first time. If you haven't done it, just send your documents to a loan officer and ask for a pre-qualification letter. The letter is not a guarantee, but it gives you a real number instead of an estimate based on what you hope you earn.