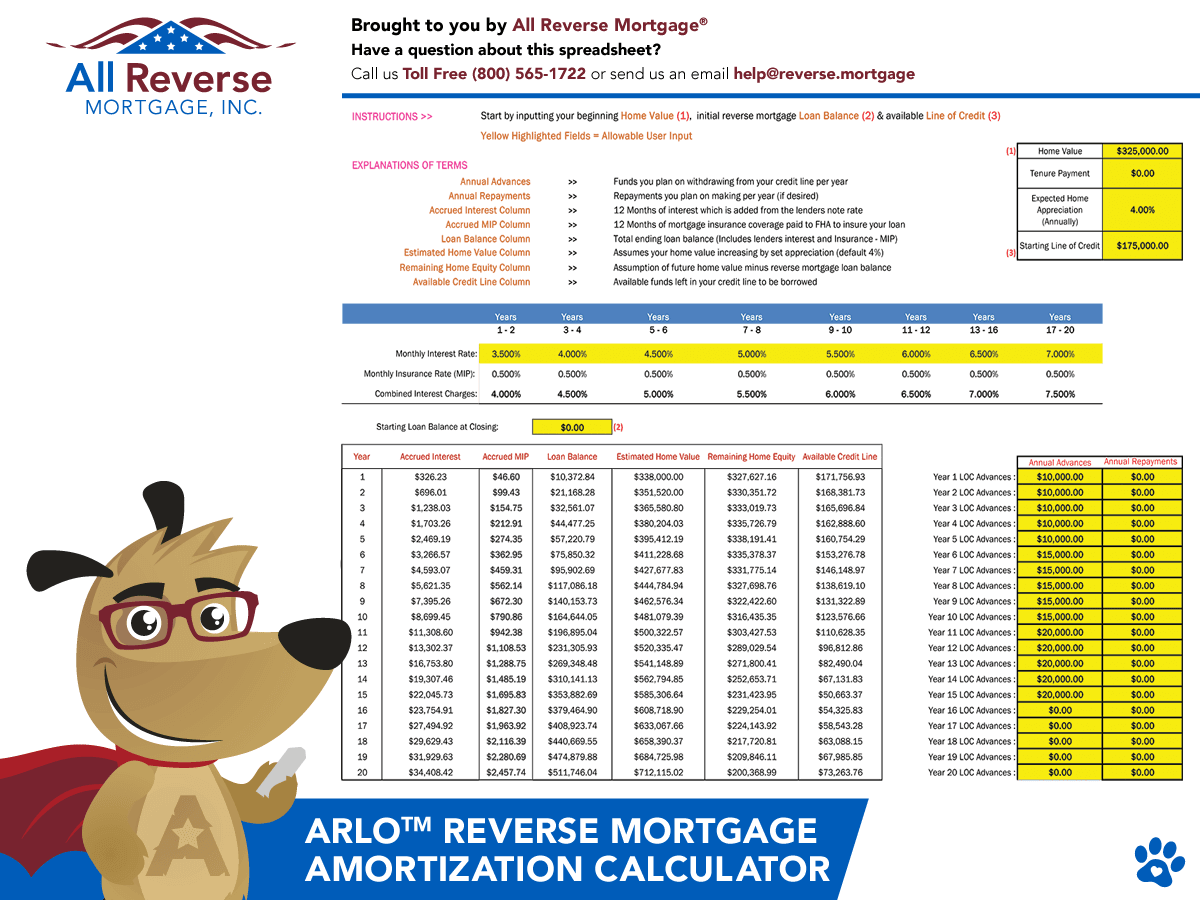
How Reverse Mortgage Calculations Actually Work
Reverse mortgages are one of those products where the math looks straightforward on paper and falls apart the moment you plug in real numbers. I spent about four years working in reverse mortgage underwriting before moving to the advisory side, and the most common mistake I see is people treating the principal limit as if it's a fixed amount. It isn't. The number changes depending on which interest rate product you lock in, how old you are, what the home is worth, and whether you're doing a FHA HECM or a proprietary jumbo product. The basic idea is that a borrower over 62 can convert home equity into cash without selling. The loan doesn't require monthly payments. Interest accrues and compounds. The balance grows over time until the borrower moves out, sells, or passes away. What most people don't realize is that there's actually a cap on how much you can pull out. That cap is called the principal limit, and it's calculated differently than a traditional mortgage.
Calculating Reverse Mortgage
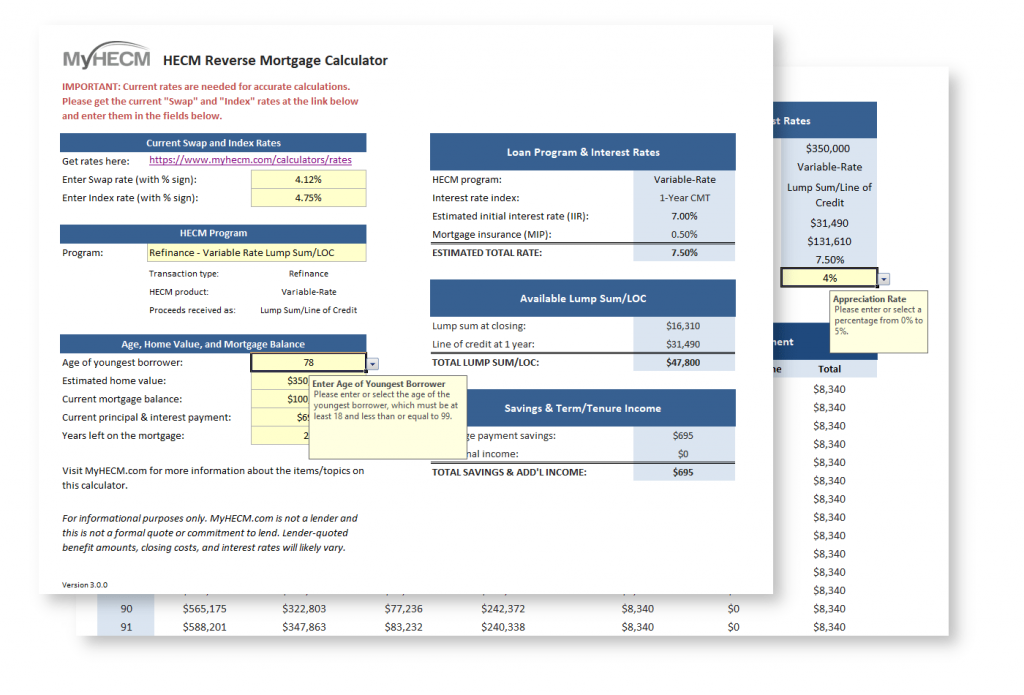
The formula starts with three inputs: the borrower's age, the property value or the lending limit, and the expected interest rate. For HECM loans in 2024 and beyond, the FHA sets a maximum claim amount. If your home is worth less than that limit, you use the actual value. If it's worth more, you use the conforming or commercial ceiling depending on the loan type. The age piece matters a lot. A 79-year-old borrower gets a significantly higher principal limit factor than a 62-year-old because the loan is expected to be outstanding for fewer years. This is the single biggest driver that consumers underestimate. Once you have those three numbers, you apply the principal limit factor from the HECM tables. Multiply the lesser of appraised value or the lending limit by that factor. That gives you the base principal limit. From there, you subtract any existing liens, closing costs, and the mortgage insurance premium. The result is the net principal limit, which is the actual cash available to the borrower at closing. The exact table factors shift every quarter when the London Interbank Offered Rate or the SOFR-based index moves, so the calculation you do today could be off by a few thousand dollars next month. I remember one case where a borrower had two siblings co-owning a property in Arizona. The home was worth roughly $420,000, but one sibling was 71 and the other was 63. We ran the numbers on both scenarios and the age gap alone created about a $28,000 difference in the principal limit. The younger sibling would have walked away with noticeably less money simply because of the actuarial tables. That's the kind of thing that doesn't show up in a quick online calculator.
What Most People Miss About the Math
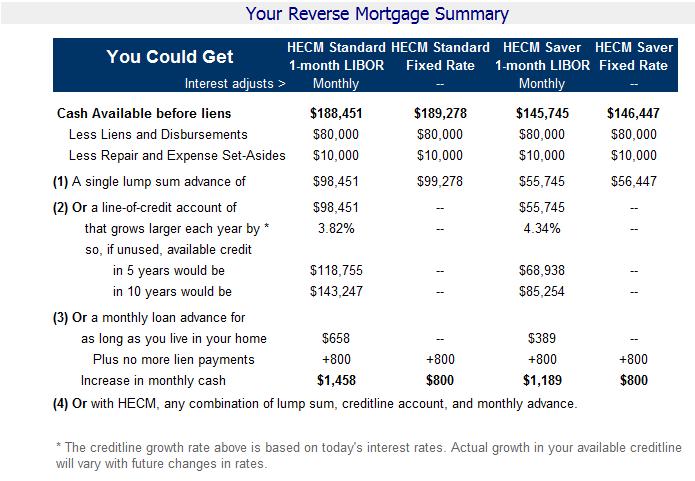
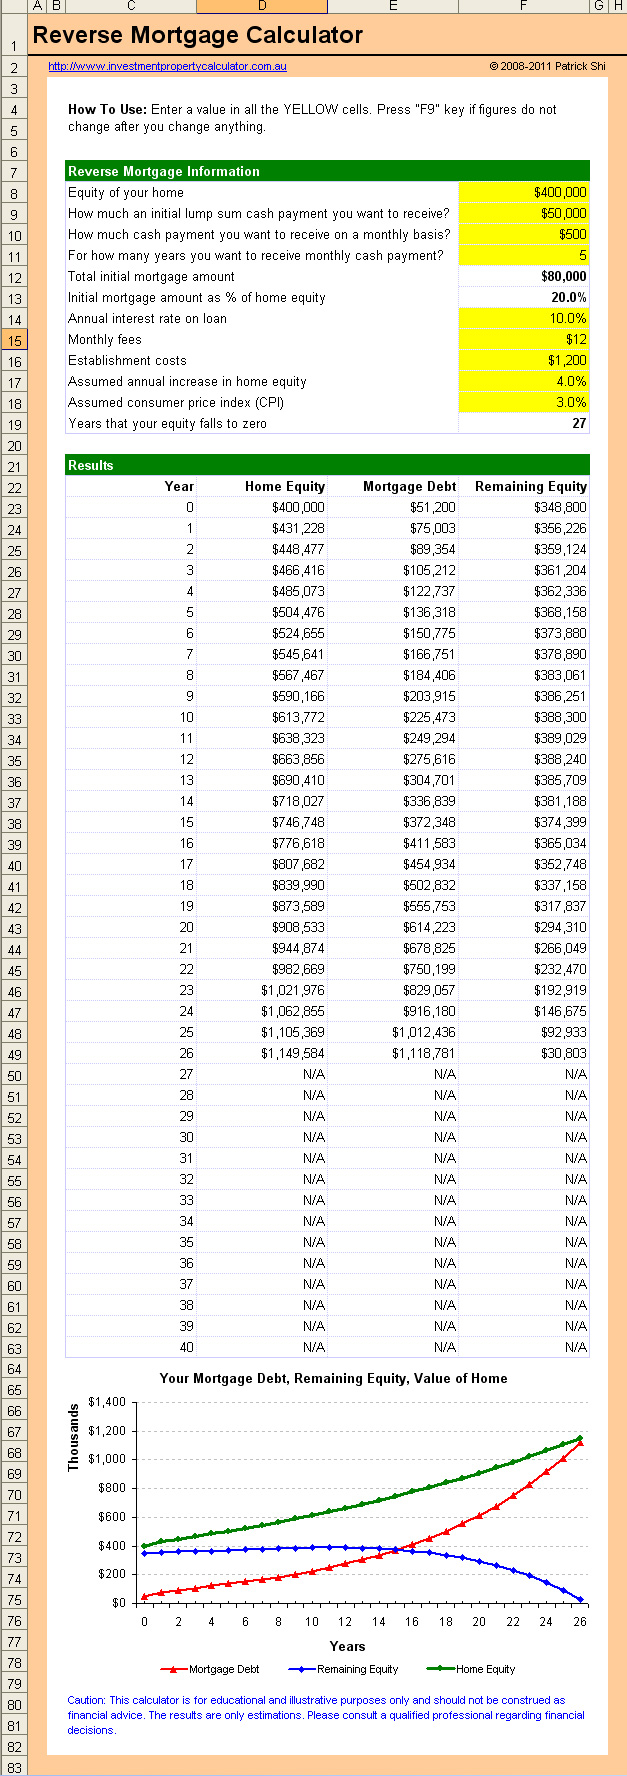
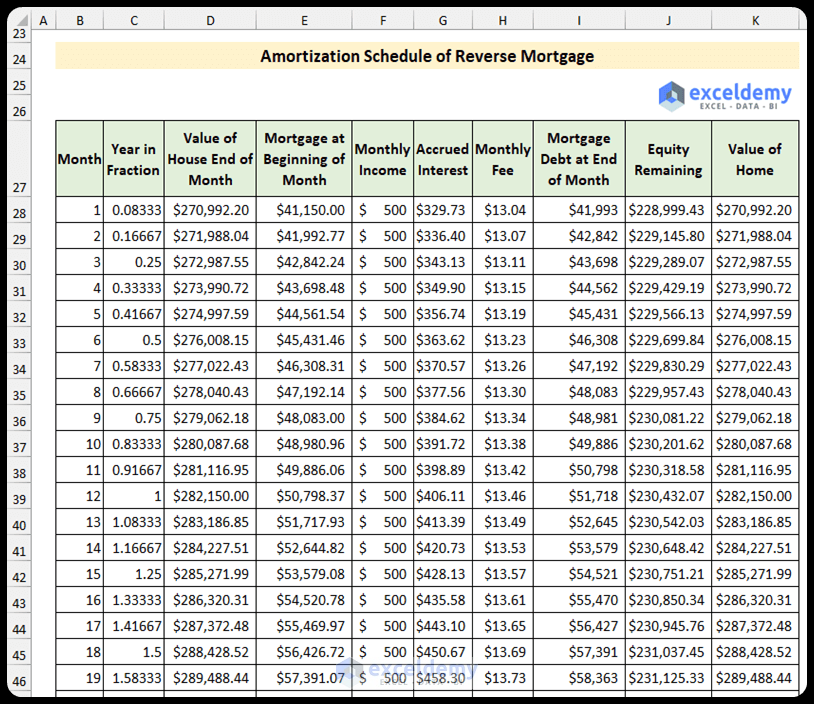
Online reverse mortgage calculators are useful for a rough estimate but they tend to smooth over several variables that materially change the outcome. The most important one is the mortgage insurance premium. HECM loans require an upfront MIP of 2 percent of the home value plus an annual MIP of 0.5 percent. That upfront charge gets rolled into the loan balance, which means you're paying insurance on money you didn't even receive. A $300,000 home generates about $6,000 in upfront MIP alone. That reduces your net proceeds and makes the effective yield on the loan higher than the stated interest rate. Another thing people overlook is the difference between a line of credit product and a lump sum disbursement. A lump sum at closing means you get all your principal limit upfront but you also pay the upfront MIP on the full amount immediately. A line of credit lets you draw over time, and the unused portion of your principal limit actually grows at the loan's interest rate plus the MIP. This is called the growth factor and it's one of the more powerful features of HECM products that almost nobody uses properly. I worked with a client last year who took a $150,000 lump sum reverse mortgage. Two years later she needed another $40,000 for a medical procedure and found out her available principal limit had dropped to roughly $20,000 because the accrued interest and fees had eaten through her cushion. If she had structured it as a line of credit with a modest initial draw, the unused portion would have continued growing and she would have had more flexibility when the unexpected expense came up. The math works in your favor if you understand how the line of credit grows, but it punishes you quickly if you front-load everything.
Get the Full Details
The Edge Case That Always Causes Problems
Non-borrowing spouses are the trickiest part of reverse mortgage calculations and they're where most people get burned. If you're married and your spouse is under 62, or if your spouse doesn't qualify for the loan for any reason, they are classified as a non-borrowing spouse. The loan still closes, but the non-borrowing spouse loses certain protections. Under current HUD guidelines, if the borrowing spouse passes away, the non-borrowing spouse can stay in the home but they cannot inherit the reverse mortgage or refinance it. The loan becomes due and payable when the last borrower dies or permanently moves out. The calculation changes too. In some cases, the principal limit is reduced because the loan term is shortened by the life expectancy of the younger spouse. I had a situation where a 74-year-old man wanted to take out a reverse mortgage on his home, but his 61-year-old wife couldn't be on the loan. The expected loan term dropped from about 18 years to roughly 12 years based on joint life expectancy tables. That cut his principal limit factor by nearly 15 percent compared to if he were single. We ended up restructuring the ownership so she could be added as a co-borrower through a refinancing step after the initial closing, but that added about six weeks and $3,200 in additional closing costs to the transaction.
When Reverse Mortgage Math Doesn't Make Sense
Reverse mortgages are not appropriate for everyone and they fail as a financial tool in specific situations. If you plan to move within three to five years, the upfront costs will almost certainly eat more than the equity you gain. Closing costs on a HECM typically run between $4,000 and $7,000 including the upfront MIP, appraisal, origination fees, and title work. On a $250,000 home, that's a significant percentage of your available proceeds. Properties in poor condition also create calculation headaches. FHA requires the home to meet minimum property standards before closing. If the roof needs replacing or there are structural issues, the repair escrow gets added to the loan costs and reduces your net principal limit. I once had a borrower whose $380,000 home required an $18,000 roof replacement before the FHA appraisal would pass. That came straight out of the available funds and left her with about $22,000 less than the original estimate. You need to get a pre-inspection done before you even start calculating. There's also a hard ceiling on how much you can access regardless of home value. For a HECM in 2024, the lending limit is $1,149,825 for most markets. If your home is worth $2 million, the calculation still uses $1,149,825 as the basis. Jumbo proprietary reverse mortgages go higher, sometimes up to $3 or $4 million, but those come with stricter eligibility requirements and generally higher interest rates. If you're a high-net-worth borrower looking at a very expensive property, a proprietary product might make sense, but you should run the numbers side by side because the higher rate can offset the benefit of a larger loan limit over a 10-year hold period.
How to Do the Calculation Yourself
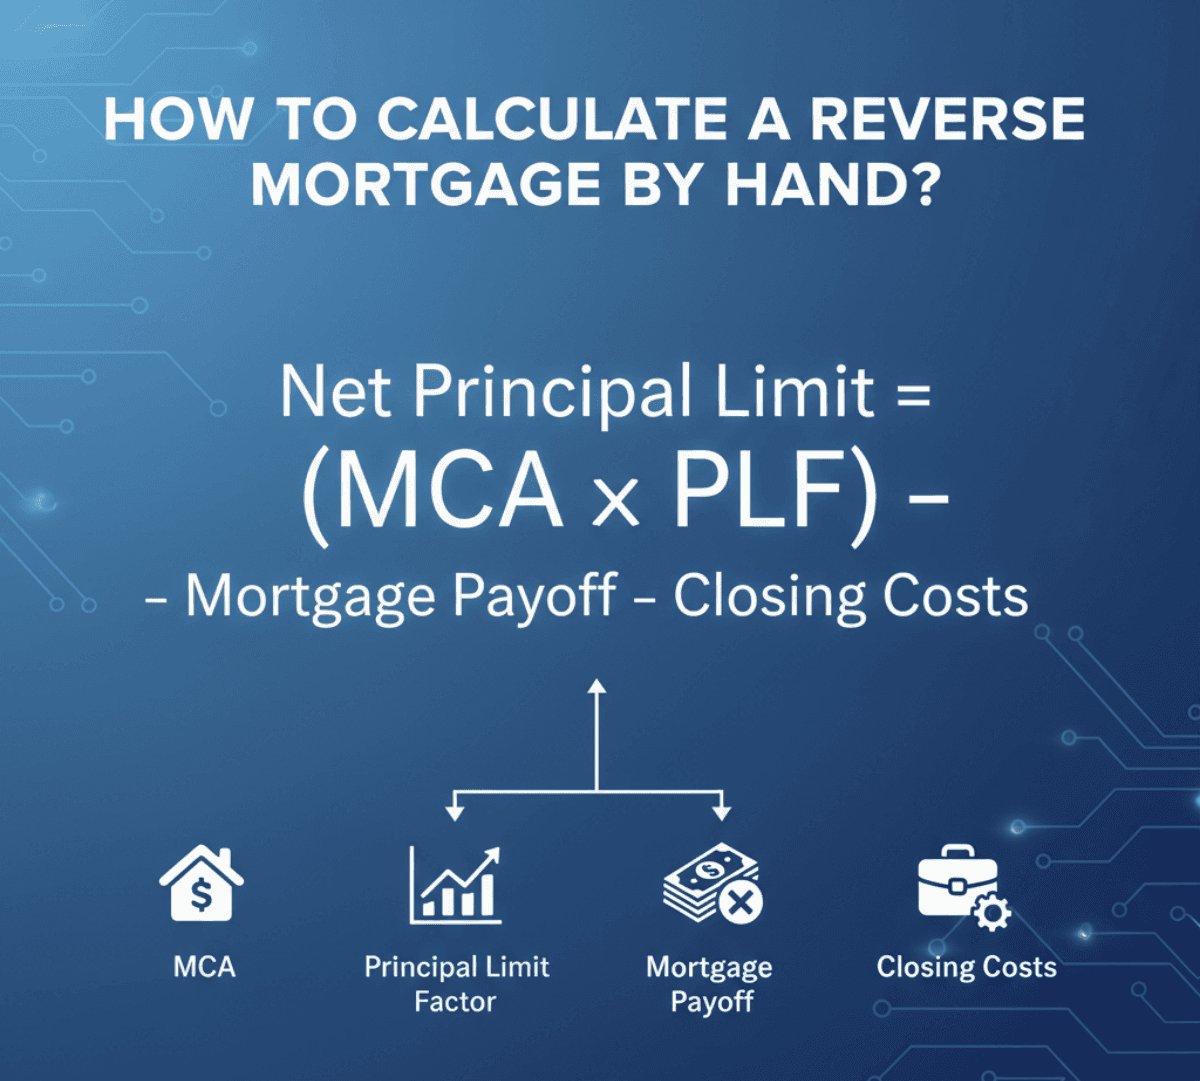
The most reliable way to get an accurate figure is through a HUD-approved counselor or a reverse mortgage specialist who pulls the actual HECM tables for the current quarter. Online calculators give you a ballpark, but they rarely account for local closing cost variations, property condition adjustments, or the specific lending limit that applies to your zip code. A professional will also flag any title issues, HOA restrictions, or cooperative rules that could block the loan entirely before you invest time in the application. If you want to do a preliminary estimate on your own, here's the practical approach. Take your home's current market value and cap it at the FHA lending limit for your area. Look up the current principal limit factor for your age bracket and the interest rate option you're considering. Multiply those two numbers. Subtract the payoff amount of any existing mortgage. Subtract an estimate of closing costs, typically $5,000 to $8,000 for a standard HECM. Subtract the upfront MIP of 2 percent. What remains is your approximate net principal limit. It will be within 5 to 10 percent of the actual number after all the finer details are resolved. The numbers don't lie, but they also don't tell the whole story. A reverse mortgage can provide genuine financial flexibility for someone who is house-rich and cash-poor, but it's expensive, it compounds against you, and it reduces the inheritance you leave behind. Get the calculation done properly before you commit to anything. A 30-minute consultation with someone who does these every week is worth more than a dozen online estimates.