How Reverse Mortgage Calculations Actually Work in Practice
A reverse mortgage calculator is useful for getting a rough idea of your eligibility, but it does not tell the whole story. I have seen hundreds of people try to use online tools and then wonder why the numbers at the lender's office do not match. The core issue is that reverse mortgage math depends on several variables that shift constantly. You need to know which ones matter and which ones are essentially noise. The primary factors are your age, the current interest rate, the appraised value of your home, and any existing mortgage balance. Your age matters most because older borrowers qualify for larger loan amounts. A 70-year-old and a 78-year-old with identical homes can receive significantly different amounts, sometimes tens of thousands apart. The interest rate compounds daily, which means even a half-percent difference adds up fast over the life of the loan. This is why the Calculator For Reverse Mortgage tools you find online need to be used with a current rate, not the rate from last month.
Using a Calculator For Reverse Mortgage Correctly
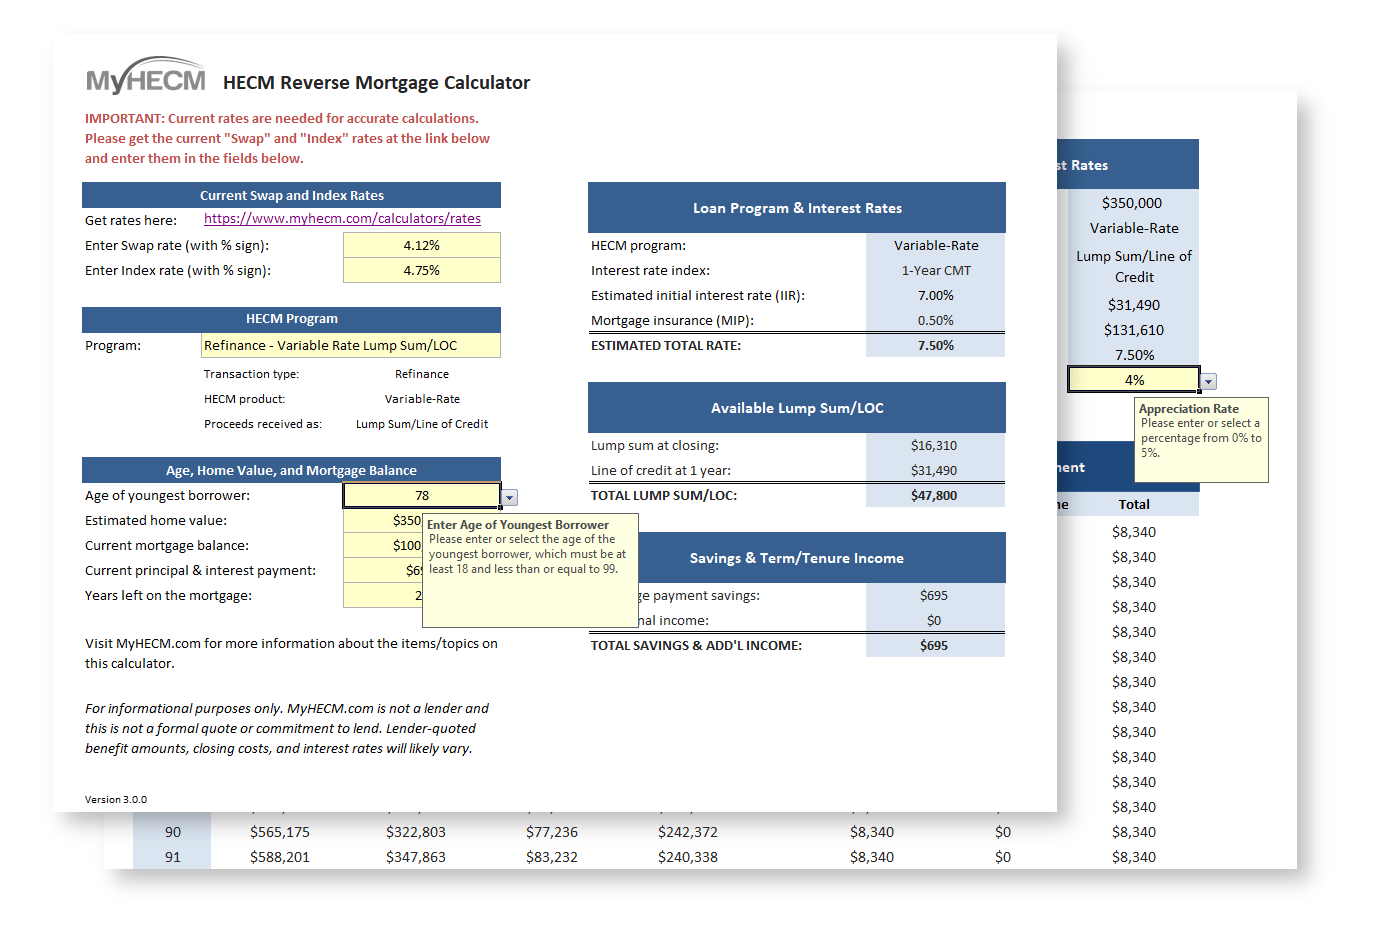
The FHA HECM calculator is the closest thing we have to an official tool, and it is free at hud.gov. I use it as a starting point, not an endpoint. Enter your age, your zip code, and your estimated home value. The calculator will spit out a maximum claim amount and then break down your principal limit based on the expected interest rate. Take those numbers and compare them against a quote from a licensed lender. If they are within five percent, you are roughly in the right neighborhood. If they are off by more, something is different between the two scenarios. Here is where most people make mistakes. They assume the calculator gives them a fixed dollar amount they will receive. It does not. The number shown is a ceiling, not a promise. Your actual proceeds depend on how you choose to take the money. A line of credit grows over time at the loan's interest rate plus the mortgage insurance premium, which means it can outpace other withdrawal methods. A lump sum gives you cash immediately but consumes most of your available principal right away. Many borrowers do not realize this trade-off until they see the final closing documents. I ran into a specific problem last year that illustrates this gap well. A client came to me with a printout from a free online reverse mortgage calculator showing she would receive about $180,000. Her home was worth $450,000, she was 72, and she had no existing mortgage. The calculator assumed a 6.5% interest rate, which was two full percentage points below the actual HECM rates at the time. When her lender ran the numbers with the current rate, her maximum eligible amount dropped to roughly $152,000. She was nearly $30,000 off. The workaround I used was to pull the actual HECM lending rates from the FHA site for that specific week and feed those into the calculator instead of using a generic estimate. That brought the projected number within four percent of the lender's quote, which is close enough for preliminary planning.
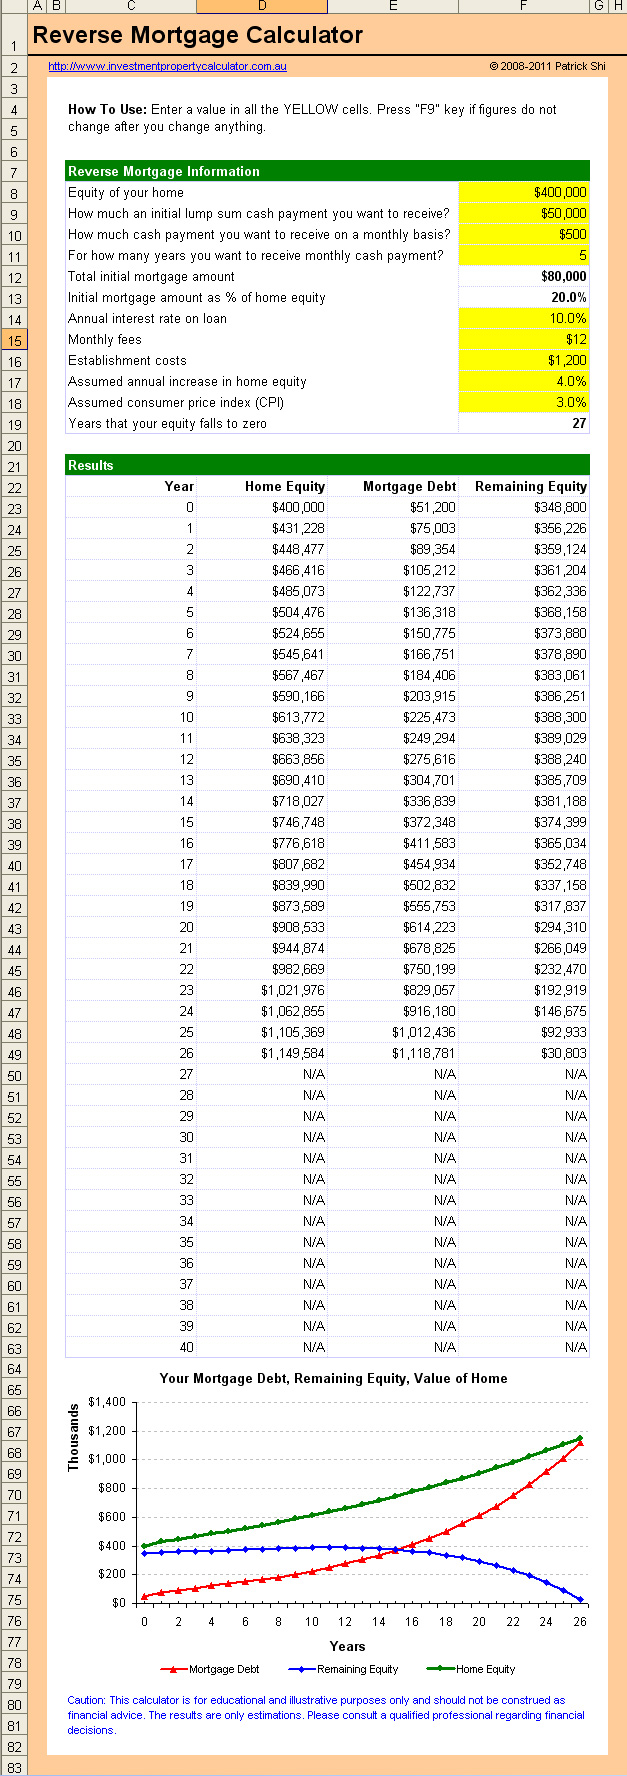
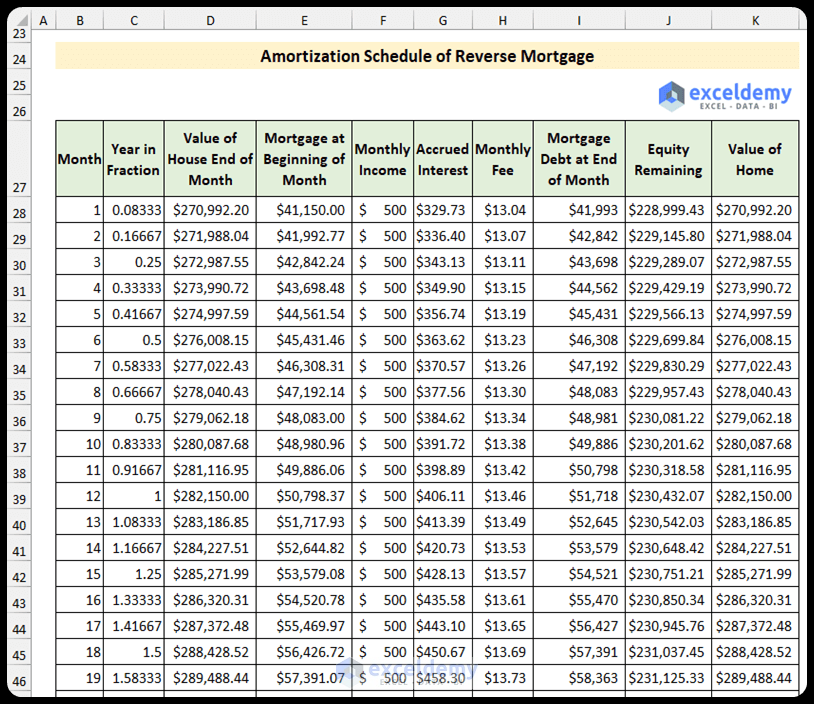
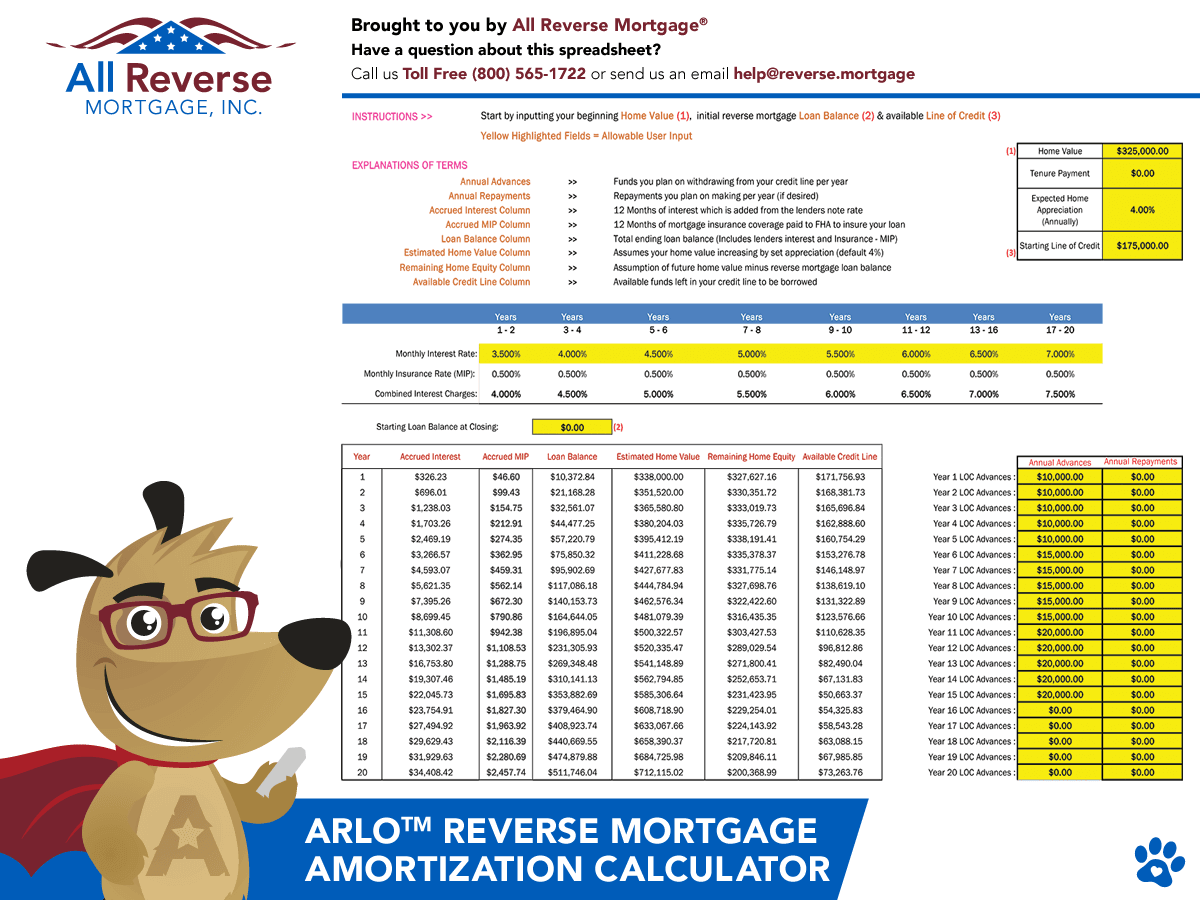
Another hidden factor is the upfront mortgage insurance premium, commonly called the UMPI. It is set at 2% of the home's capped value for most HECMs. Some calculators hide this or bury it in the fine print. This 2% is deducted from your principal limit before anything else, which means it directly reduces your available funds. On a $400,000 home, that is $8,000 gone immediately. Then there is the annual mortgage insurance premium, which is 0.5% of the outstanding loan balance each year. This continues to erode your principal limit over time, and most basic calculators do not show how much it will cost after five or ten years. I usually run a spreadsheet alongside the calculator to project the cumulative PMI impact so borrowers can see the real long-term cost. If you have an existing mortgage, the calculator can be misleading. Some tools simply subtract your current loan balance from the home value and treat the remainder as available equity. This ignores the fact that reverse mortgage closing costs are layered on top of everything. The actual math requires you to add the closing costs to your existing mortgage balance first, then subtract that total from the available principal limit. I have seen calculators get this wrong, and borrowers end up surprised at closing. The fix is to treat the existing mortgage as a first lien that must be paid off before any reverse mortgage proceeds are disbursed, and to factor in closing costs separately rather than folding them into the available equity number. Proprietary reverse mortgages, like HELOC-based products from private lenders, do not use the FHA framework. They have their own formulas, different insurance requirements, and often higher interest rates. A standard HECM calculator will not work for these products. If you are looking at a non-FHA option, you need to ask the lender for their own amortization schedule and draw calculations. Do not rely on an FHA tool for a proprietary product.
Get the Full Details
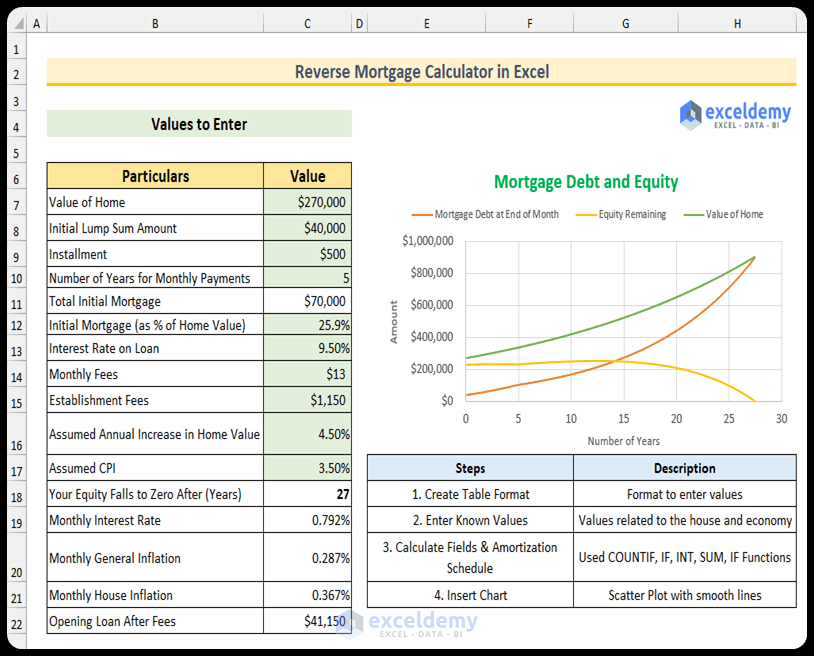
One thing to keep in mind is that closing costs vary by lender and by location. The calculator gives you a general estimate, but actual costs can range from $3,000 to $6,000 or more depending on your state, your property type, and the lender you choose. These costs are added to your loan balance, which reduces your available principal. Some calculators include them in the estimate, others do not. Always verify with your lender whether the calculator has accounted for your specific closing costs. The biggest limitation of any reverse mortgage calculator is that it cannot account for individual circumstances. If you have a low credit score, significant delinquencies, or a history of property tax or insurance non-payment, lenders may impose additional requirements that reduce your eligible amount or change your terms entirely. The calculator treats every borrower the same. Real underwriting does not. A borrower who walks in with a clean financial profile will get a better deal than someone with past collection issues, even if both have the same home value and age. This is not something any online tool can predict. If you want a number that is closer to reality, get a Good Faith Estimate from at least two lenders and compare those to the calculator output. The calculator is a planning aid, not a binding offer. It is fine for deciding whether to pursue a reverse mortgage at all, but once you are serious, the lender's documentation is what matters. The gap between the calculator and the real quote is usually small enough to be manageable, but it exists, and knowing where it comes from saves you from unnecessary stress later.