Why most LTV calculations are wrong before you even run them
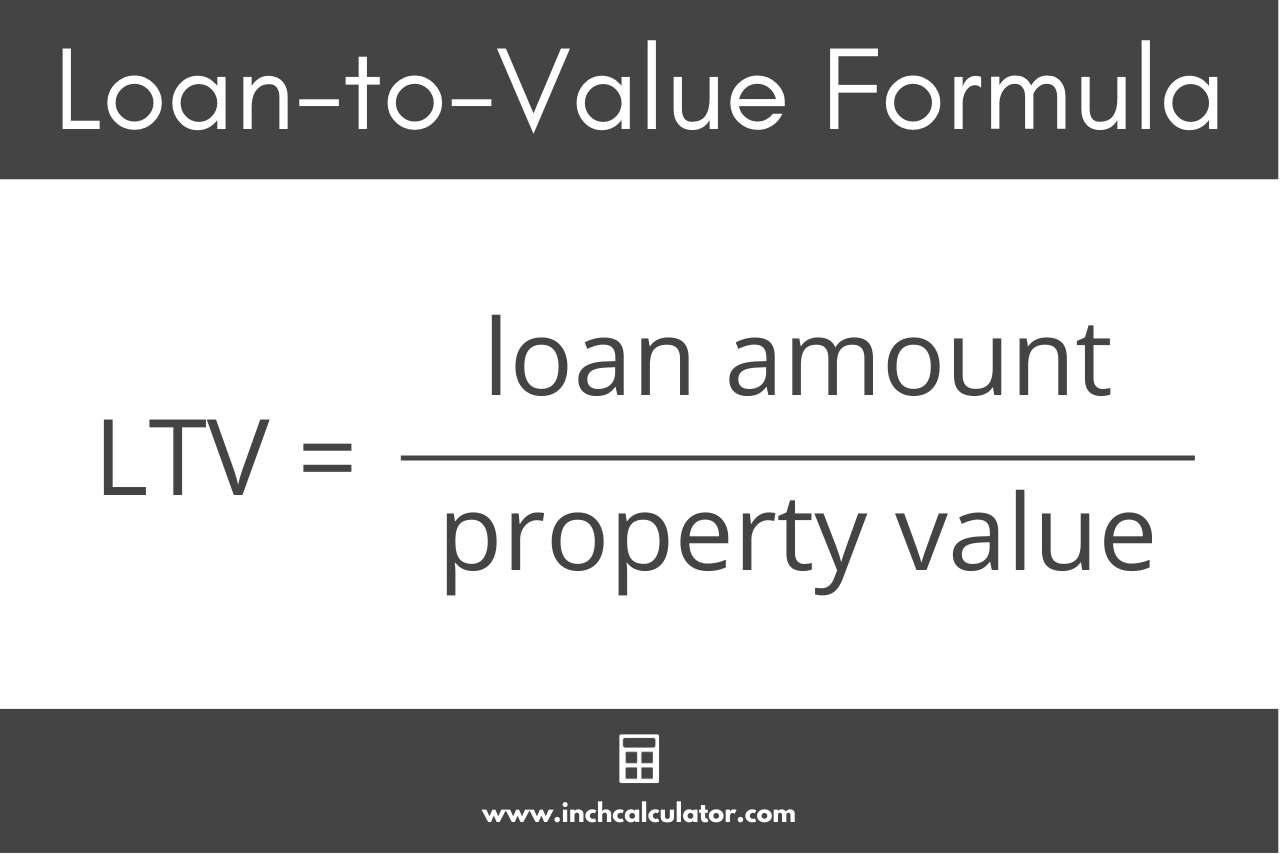
The Calculator Ltv tools floating around the internet assume your input data is clean. It rarely is. I spent three years in commercial lending before moving to prop tech, and the number one reason a deal falls apart at the LTV check isn't the math—it's dirty data going in. Appraised values from two years ago, inflated purchase prices in distressed sales, and properties with unpermitted additions that assessors never caught. Run your Calculator Ltv against that garbage and you get a number that looks precise but means nothing. Start with the actual current market value, not the tax assessor's figure and not what the seller listed it for. Get a fresh appraisal or aBroker Price Opinion if the property is non-standard. Then take the total loan amount including any second mortgages, home equity lines, or seller financing. Divide the total debt by the value. Multiply by 100. That's your LTV percentage. The formula itself is trivial. The execution is where people mess up. I had a borrower who was refinancing a duplex. The appraiser comparable sales were from a hot market in 2022. By the time we ran the Calculator Ltv in 2024, those comps had dropped 14 percent. The LTV jumped from 68 to 79 on the same property. We pulled a second appraisal using adjusted comparables and recalculated. The difference changed the entire loan structure and the interest rate tier.
Here is what most online calculators skip: they don't account for closing costs rolled into the loan, mortgage insurance premiums added to the balance, or point fees that inflate the principal. Every dollar added to the loan numerator pushes the LTV up. If you are borrowing $250,000 on a $320,000 property and rolling $8,000 in costs into the loan, your actual LTV is 80.6 percent, not 78.1 percent. That half percent can push you into a different risk bucket with a different rate.
Common pitfalls that sink deals
People treat LTV as a static number. It is not. It changes with market moves, with additional borrowing, and even with how the lender defines the collateral value. Some lenders use the lesser of purchase price or appraised value. Others use a hybrid approach. Know which one your lender uses before you trust any Calculator Ltv output blindly. Another thing nobody warns you about: LTV calculations for investment properties are handled differently than owner-occupant loans. Investor LTV caps are tighter because vacancy risk and repair cycles eat into cash flow faster. A Calculator Ltv showing 75 percent might get you approved for a primary residence but denied for a rental. The number looks the same. The underwriting reality does not. I learned this the hard way with a client who bought a triplex in a midwest market. The numbers looked fine on paper. The LTV calculator showed 71 percent. Underwriting flagged it because the lender's policy capped investor LTV at 70 percent for multi-unit properties in that zip code. We restructured with a smaller first lien and a second lien from a different source. The deal closed, but it cost extra and took three weeks longer because nobody mentioned that threshold beforehand.
Get the Full Details
When Calculator Ltv tools fail completely
Online calculators are fine for rough estimates. They are useless for anything involving non-traditional financing, mixed-use properties, or portfolios where you are cross-collateralizing. I've seen people try to run a Calculator Ltv on a property with a ground lease instead of a fee simple. The tool returned a number. The underwriter rejected it because leasehold valuations require a completely different methodology. Same with properties in HOA-controlled communities with rental restrictions—the LTV might look acceptable but the lender's guidelines invalidate the loan entirely based on occupancy rules, not the ratio. If you are working with a portfolio loan or a DSCR-based qualification instead of traditional income verification, LTV is only one piece of the puzzle. Some lenders prioritize DSCR over LTV thresholds. A 75 percent LTV with a weak DSCR gets denied while a 80 percent LTV with strong cash flow gets approved. The Calculator Ltv gives you part of the picture. Relying on it alone is how you waste time on loans that will never clear underwriting.
Getting accurate results from a Calculator Ltv
Use the tool, but validate every input. Pull the most recent closed comps in the submarket, not the neighborhood. Adjust for differences in square footage, condition, and lot size before you trust the estimated value. Run the Calculator Ltv with the full loan amount including every fee and cost you plan to finance. Then run it again with just the base loan to see the variance. That gap tells you exactly how much your costs are pushing your risk tier higher. Keep a spreadsheet tracking your LTV across all properties. Markets move. An LTV that was comfortable last quarter might be risky this quarter if values shift. I track my portfolio LTV monthly and I recalculate whenever there is a significant rate change or market movement in the area. It takes about twenty minutes and it has saved me from taking on loans I should have walked away from.