How Mortgage Calculations Actually Work (And Where They Lie To You)
The standard formula for calculating a monthly mortgage payment is straightforward enough, but most people who look at it for the first time miss the part that matters most. You need the principal, the annual interest rate divided by 12, and the total number of payments. Plug those into the amortization formula and you get a number. That number is usually not what you end up paying each month. I spent years watching clients get whiplash when their first payment came in $200 higher than the online calculator showed. The gap isn't a mistake. It is the result of how lenders structure the payment versus what the pure math says the interest should be.
Calculo De Hipoteca: The Real Formula
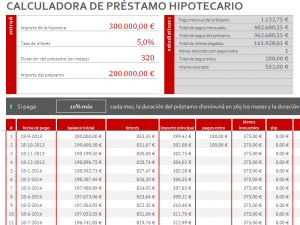
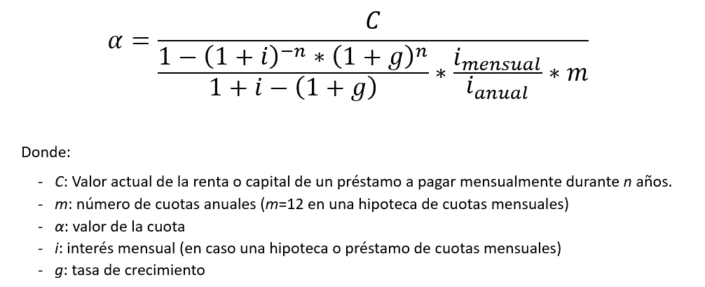
Start with what you are actually borrowing. If the home price is $350,000 and you put 20 percent down, your principal is $280,000. Take the annual rate, say 6.5 percent, and divide by 12 to get your monthly periodic rate: 0.005417. Multiply your term in years by 12 to get the total number of payments. A 30-year loan is 360 payments. The payment formula is: M = P × [r(1+r)^n] / [(1+r)^n 1]
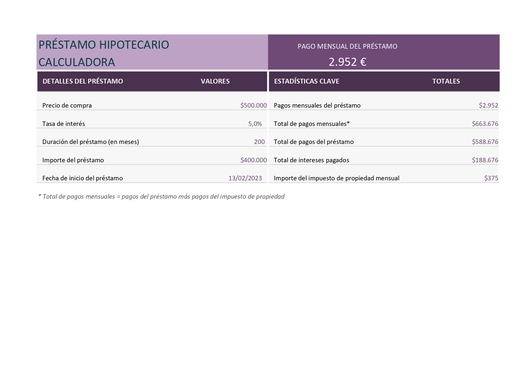
Where M is the monthly payment, P is the principal, r is the monthly rate, and n is the number of payments. Run that through a spreadsheet or a decent calculator and you get roughly $1,769 per month for those numbers. That is the principal and interest portion only. Now add escrow. Property taxes, homeowners insurance, and sometimes PMI all fold into the monthly payment the lender collects. In many markets the tax and insurance component adds another $400 to $900 a month depending on where the property sits. Forget to include that and your budget is wrong from day one. There is also the matter of upfront costs. Points, origination fees, appraisal, credit report, title search, recording fees. Those do not show up in the monthly calculation but they affect your actual cost of borrowing. A lender might quote you a lower rate in exchange for two discount points. On a $280,000 loan that is $5,600 paid at closing just to shave 0.25 percent off the rate. Whether that makes sense depends on how long you plan to hold the loan.
Get the Full Details
What Nobody Tells You About Rate Adjustments
Most first-time buyers treat the interest rate as a fixed fact. It is not. Lenders lock rates for a window, usually 30 to 60 days, and if your closing drifts past that window the rate can move. I had a client whose lock expired by three business days because the title company was slow on the survey. The rate moved up 0.125 percent. On a $300,000 loan over 30 years that is roughly an extra $45 a month. Not catastrophic but it is real and it is preventable if you push the file forward weekly instead of waiting for updates. Another thing that trips people up is how the first payment is calculated. If you close on the 15th of the month, you owe interest from the 15th to the end of that month before your first full payment is due. That means you pay closing costs plus prepaid interest plus the first full month's payment all at or near funding. Budget for that third chunk or you will be short when the first bill arrives.
Fixed Versus Adjustable: The Trade-off Nobody Admits Is Messy
An ARM starts lower. That is the selling point. A 5/1 adjustable-rate mortgage might offer 5.75 percent when a 30-year fixed is sitting at 6.875 percent. The difference looks like money in your pocket for the first five years. It is not as clean as it sounds. ARMs have caps. The annual cap limits how much the rate can jump in a single adjustment period. The lifetime cap limits how high it can go over the life of the loan. A typical 5/1 might have a 2 percent annual cap and a 6 percent lifetime cap. So after year five the rate could adjust up by 2 percent, then another 2 percent the following year, then another 2 percent the year after that. You need to model the worst case, not the initial teaser rate, or you are budgeting on fiction. I worked with a borrower who took an ARM because the payment looked $200 cheaper per month. She stayed six years and sold. The rate had adjusted twice by then, climbing to 8.125 percent. She made the right call timing-wise but only because she had already committed to selling before the adjustments hit hard. That is the kind of planning most people skip.
When the Calculator Breaks Down
Online calculators assume a clean scenario. You enter a price, a down payment, a rate, a term and you get a number. Real mortgages rarely stay clean. Here is a specific problem I ran into last year that no calculator could handle on its own. A client wanted to buy a condo with an HOA that imposed a special assessment during escrow. The assessment was $8,400 and the lender required it to be paid at closing. The loan-to-value ratio pushed him just over the threshold for private mortgage insurance, so PMI was added. But the special assessment also meant his cash-to-close jumped, which forced him to take a slightly larger loan than he wanted, which pushed the PMI premium higher. The circular math meant the monthly payment was $32 more than his original target. I recalculated everything from the revised loan amount, adjusted the PMI based on the new LTV, and then re-verified the cash-to-close. The cycle stabilized after three passes. The lesson is that when multiple variables interact, running the numbers once is not enough. You need to iterate until the figures stop shifting.

How to Actually Use This Without Losing Your Mind
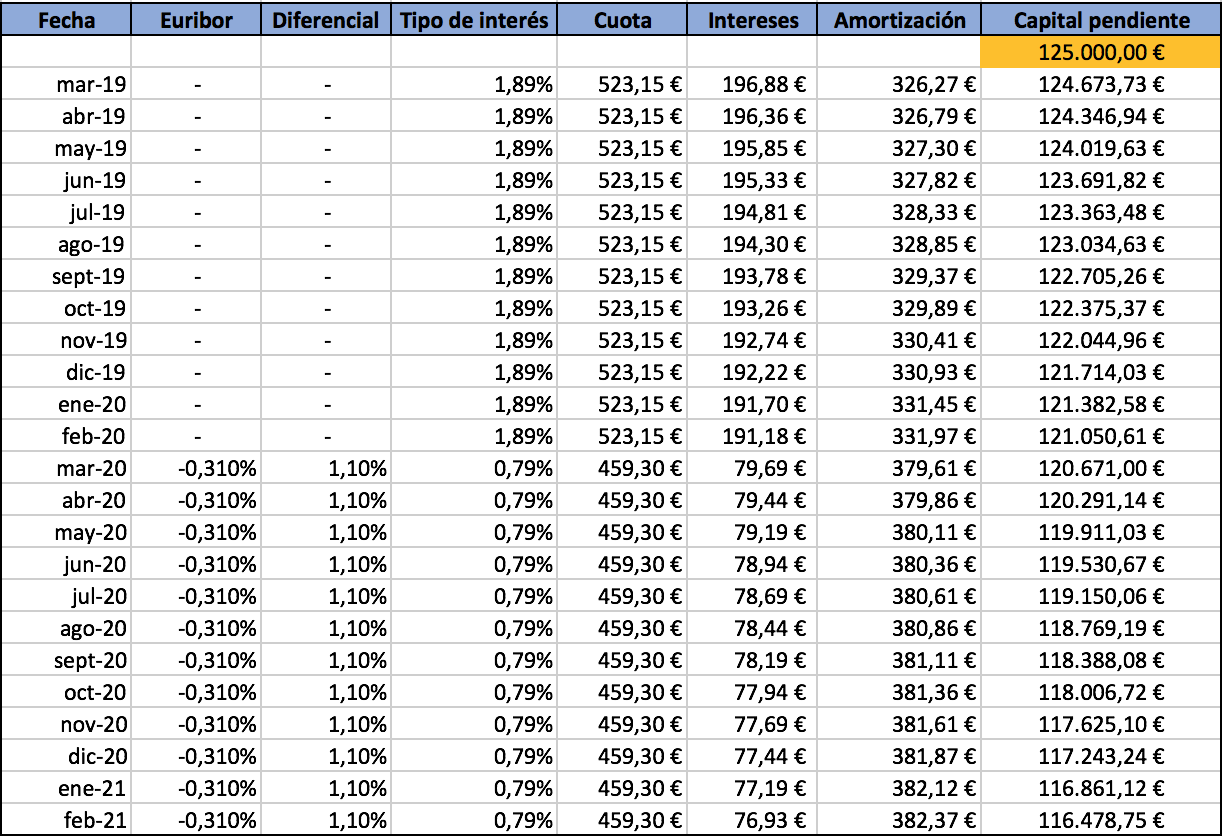
Build a simple amortization schedule in a spreadsheet. Do not rely on a single online calculator to tell you the total cost of the loan. Pull up the schedule, look at year one, year five, year ten. See how much equity you actually have at each point. Watch how the interest-heavy early years drain your payment before the principal starts moving meaningfully. Compare the total interest paid across scenarios, not just the monthly payment. A $50 monthly difference sounds small until you multiply it by 360 months. That is $18,000 in extra cost over the life of the loan, and it is often the result of a single point or a slightly higher rate tier. If you are considering an ARM, run the adjustment scenario yourself. Model the rate at the lifetime cap and see if the payment is survivable. If it is not, the ARM is not a good fit regardless of how attractive the starter rate looks.
Also check whether your lender is using the 30/360 or 365/365 day count convention. Most consumer mortgages use 30/360, but a few portfolio lenders use the actual-day method. The difference is small, maybe a dollar or two per payment, but it shows up in the payoff numbers and matters if you plan to refinance or sell within a few years.
The Hard Truths
No mortgage calculation is perfectly accurate without accounting for your local tax rate, your insurance premium, your HOA fees, and your lender's specific fee structure. The formula gives you a baseline. The real number comes from the loan estimate document, and even that can shift slightly between disclosure and closing. Online calculators are fine for ballpark figures. They are useless for underwriting. If you want something you can actually take to a lender, export your amortization schedule to CSV and cross-reference it against the Good Faith Estimate form. The numbers should align within a few dollars. If they do not, ask why before you sign anything. The Calculo De Hipoteca process itself is not hard. The hard part is making sure every variable is in the model before you commit to a number. Miss one and you are budgeting blind.