Separating variables is where most people get tripped up
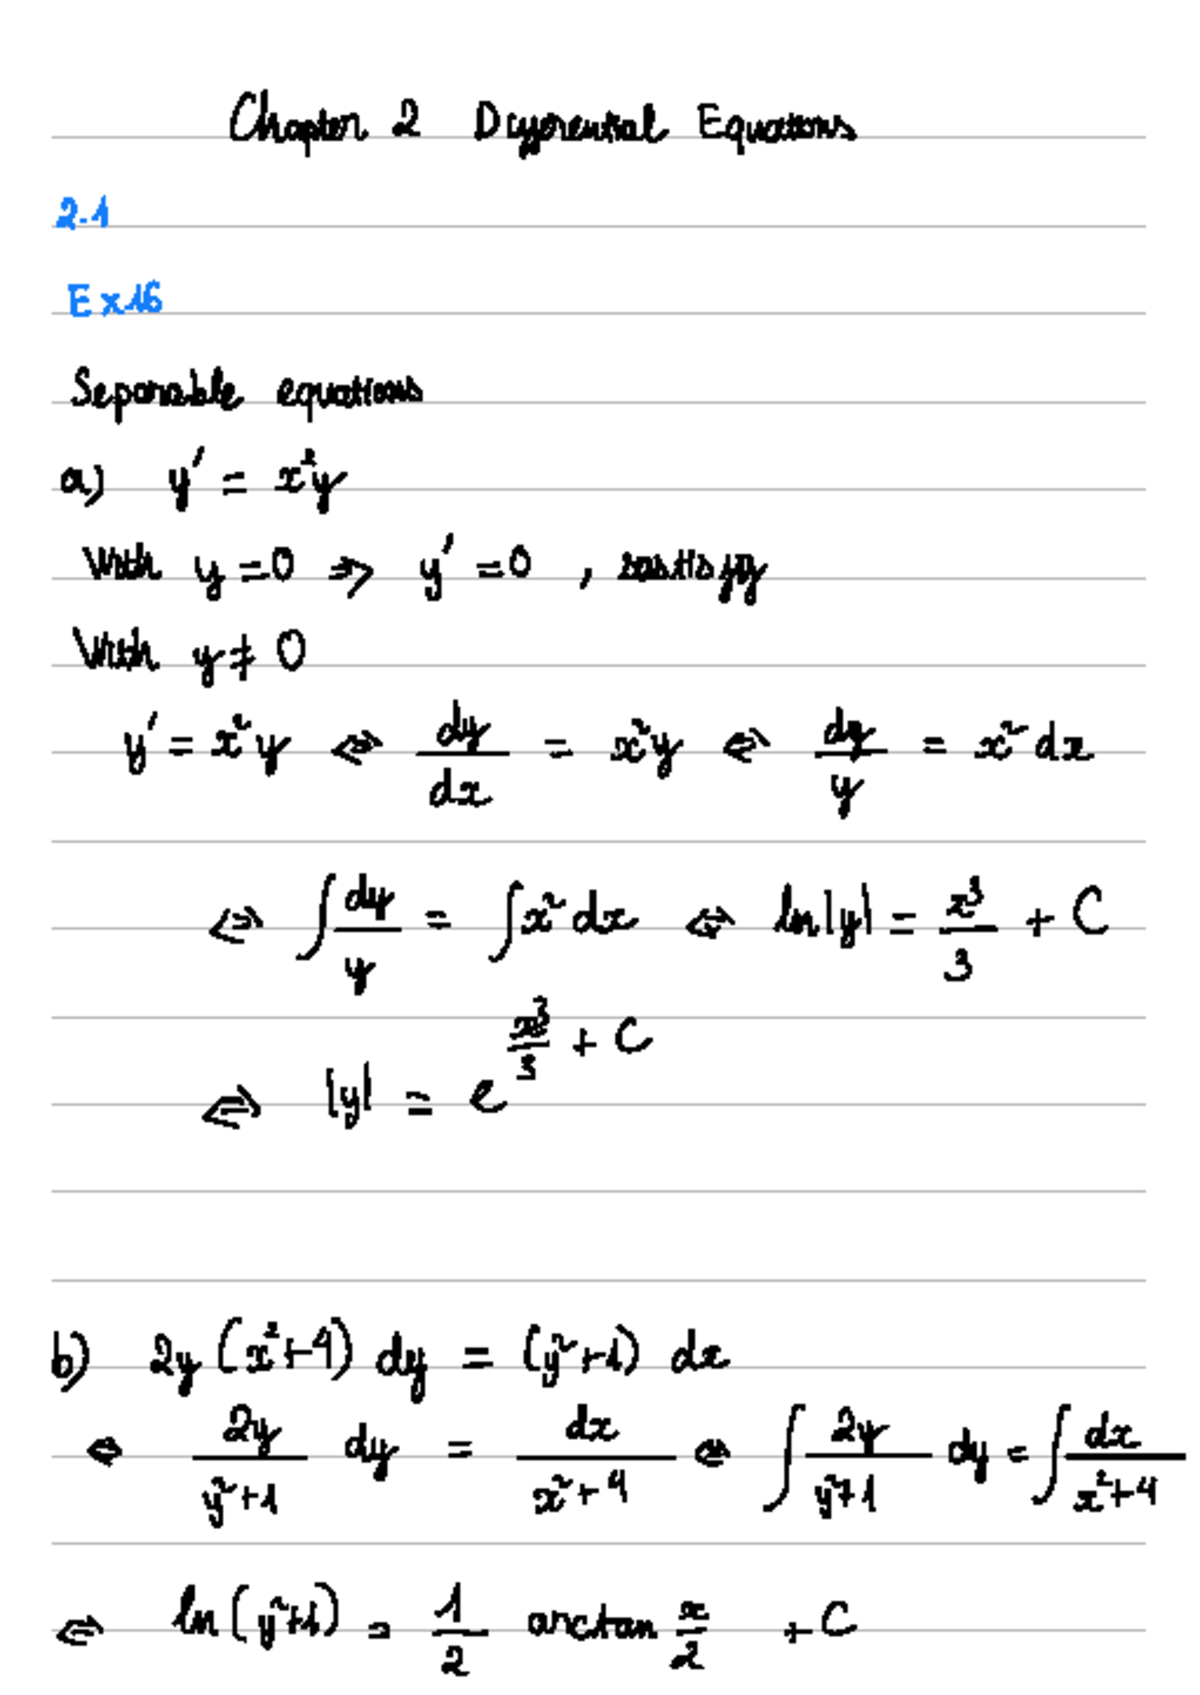
The standard approach to first-order ordinary differential equations in a second-semester calculus course involves isolating the variables on opposite sides of the equation, integrating both, and solving for y. This works cleanly when you can write f(x,y) as a product g(x)·h(y). Most textbook problems are set up this way on purpose. Real problems are rarely that cooperative. I spent three hours last month working through a problem where substitution seemed like the obvious path. The equation had the form dy/dx = (y/x) + sin(y/x). This is technically a homogeneous equation, and the standard substitution u = y/x should collapse it into a separable form. I made the substitution, simplified, and hit a wall. The resulting integral involved tan(u) + u in the denominator after rearrangement, and there was no elementary antiderivative for that expression. Not a clean one, anyway. I ended up using a numerical integration approach with Simpson's rule on a graphing calculator to trace out the solution curve, which gave me something usable in about twenty minutes instead of continuing to bang my head against symbolic integration for another three. This kind of situation comes up more often than professors want to admit. The textbook chapter usually ends with exercises that all resolve to neat logarithmic and trigonometric expressions. They don't show you what happens when the algebra doesn't cooperate.
Integrating factors for linear first-order equations
Once you have an equation in the standard form dy/dx + P(x)y = Q(x), the integrating factor method is your main tool. You compute (x) = e^P(x)dx, multiply the entire equation through by it, and the left side collapses into d/dx[(x)·y]. Then integrate both sides and divide by (x) to isolate y. The trick that students consistently miss is that the integrating factor itself doesn't need a constant of integration. Any antiderivative of P(x) works, and choosing the simplest one keeps the algebra from becoming unmanageable. Here's a practical example. Consider dy/dx + 2xy = x. The integrating factor is e^2x dx = e^(x²). Multiply through and you get d/dx[e^(x²)·y] = x·e^(x²). Integrate the right side with a simple u-substitution and the solution follows. This whole process takes roughly five to eight minutes on paper if you're comfortable with basic integration techniques. The method has real limitations though. It only applies to first-order linear equations in the standard form. If your equation has a y² term or any nonlinear function of y, the integrating factor approach breaks down entirely. You'll see problems on exams that look almost linear but contain an extra y² that makes them Bernoulli equations instead. Recognizing that distinction matters more than memorizing the integrating factor procedure itself.
Bernoulli equations and exact equations
A Bernoulli equation has the form dy/dx + P(x)y = Q(x)y where n 0 and n 1. The substitution v = y^(1-n) transforms it into a linear equation. Students often freeze at this point because the algebra looks intimidating. It isn't. You differentiate v with respect to x, substitute back, and the result is linear in v. From there you apply the integrating factor method you already know. Exact equations represent another category that shows up regularly. An equation M(x,y)dx + N(x,y)dy = 0 is exact if M/y = N/x. When this condition holds, there exists a potential function (x,y) such that /x = M and /y = N. You find by integrating M with respect to x, treating y as a constant, then differentiating the result with respect to y and matching it to N to find any remaining function of y. The solution is (x,y) = C. The catch with exact equations is that many problems presented in practice aren't actually exact. You have to check the partial derivative condition first before investing time in the integration procedure. I've seen students spend ten to fifteen minutes integrating and differentiating only to discover at the end that M/y N/x. Always verify the exactness condition in under thirty seconds before proceeding.
Get the Full Details

Second-order linear equations with constant coefficients
When you reach ay'' + by' + cy = 0, the characteristic equation ar² + br + c = 0 determines everything. Three cases exist based on the discriminant b² - 4ac. Positive discriminant gives two distinct real roots and a solution of the form y = Ce^(rx) + Ce^(rx). Zero discriminant gives a repeated root and y = Ce^(rx) + Cxe^(rx). Negative discriminant gives complex roots ± i and y = e^(x)[Ccos(x) + Csin(x)]. The case students struggle with most is the repeated root scenario. The extra x factor in front of the second exponential term doesn't come from intuition. It comes from reduction of order, where you assume a second solution of the form y = v(x)e^(rx) and solve for v. The math forces v(x) = x. Knowing why this works helps you remember the form instead of trying to derive it from scratch during an exam. Nonhomogeneous equations add a nonzero term on the right side. The method of undetermined coefficients handles this when Q(x) is a polynomial, exponential, sine, cosine, or a combination of these. You propose a trial solution with unknown coefficients, substitute it into the equation, and solve for those coefficients. This works reliably for textbook problems but becomes unreliable when Q(x) involves something like ln(x) or tan(x). Those cases require variation of parameters instead, which is more algebraically intensive but universally applicable.
I once worked on a problem where the forcing function was sec²(x). The undetermined coefficients method immediately fails because secant doesn't fit any of the standard trial forms. Variation of parameters was the only path forward, and the integrals involved x·sec²(x) and x²·sec(x)·tan(x). Both required integration by parts multiple times. The full solution took about forty-five minutes to work out cleanly. In an exam setting with time pressure, this is exactly the kind of problem that causes people to panic and make careless arithmetic errors.
Laplace transforms as a shortcut
For initial value problems, especially those with discontinuous forcing functions or when you need to solve repeatedly with different initial conditions, Laplace transforms save significant time. The transform converts derivatives into algebraic expressions. A second-order differential equation becomes a polynomial equation in s. You solve for Y(s), then apply the inverse transform to get y(t). The convolution theorem deserves mention here. When the inverse transform of your expression involves a product of two transforms that you can't easily separate, the convolution integral gives you the answer directly. This shows up in problems involving products of sine and exponential functions in the s-domain. The convolution formula f * g = f()g(t-)d produces the correct time-domain result without requiring partial fraction decomposition. Laplace transforms aren't a universal solution. They assume the function and its derivative satisfy certain growth conditions. Functions that grow faster than exponentially, like e^(t²), don't have Laplace transforms in the classical sense. You'll encounter this limitation rarely in a standard course but it's worth knowing so you don't attempt to force the method where it doesn't apply.
Common pitfalls and what actually matters on exams
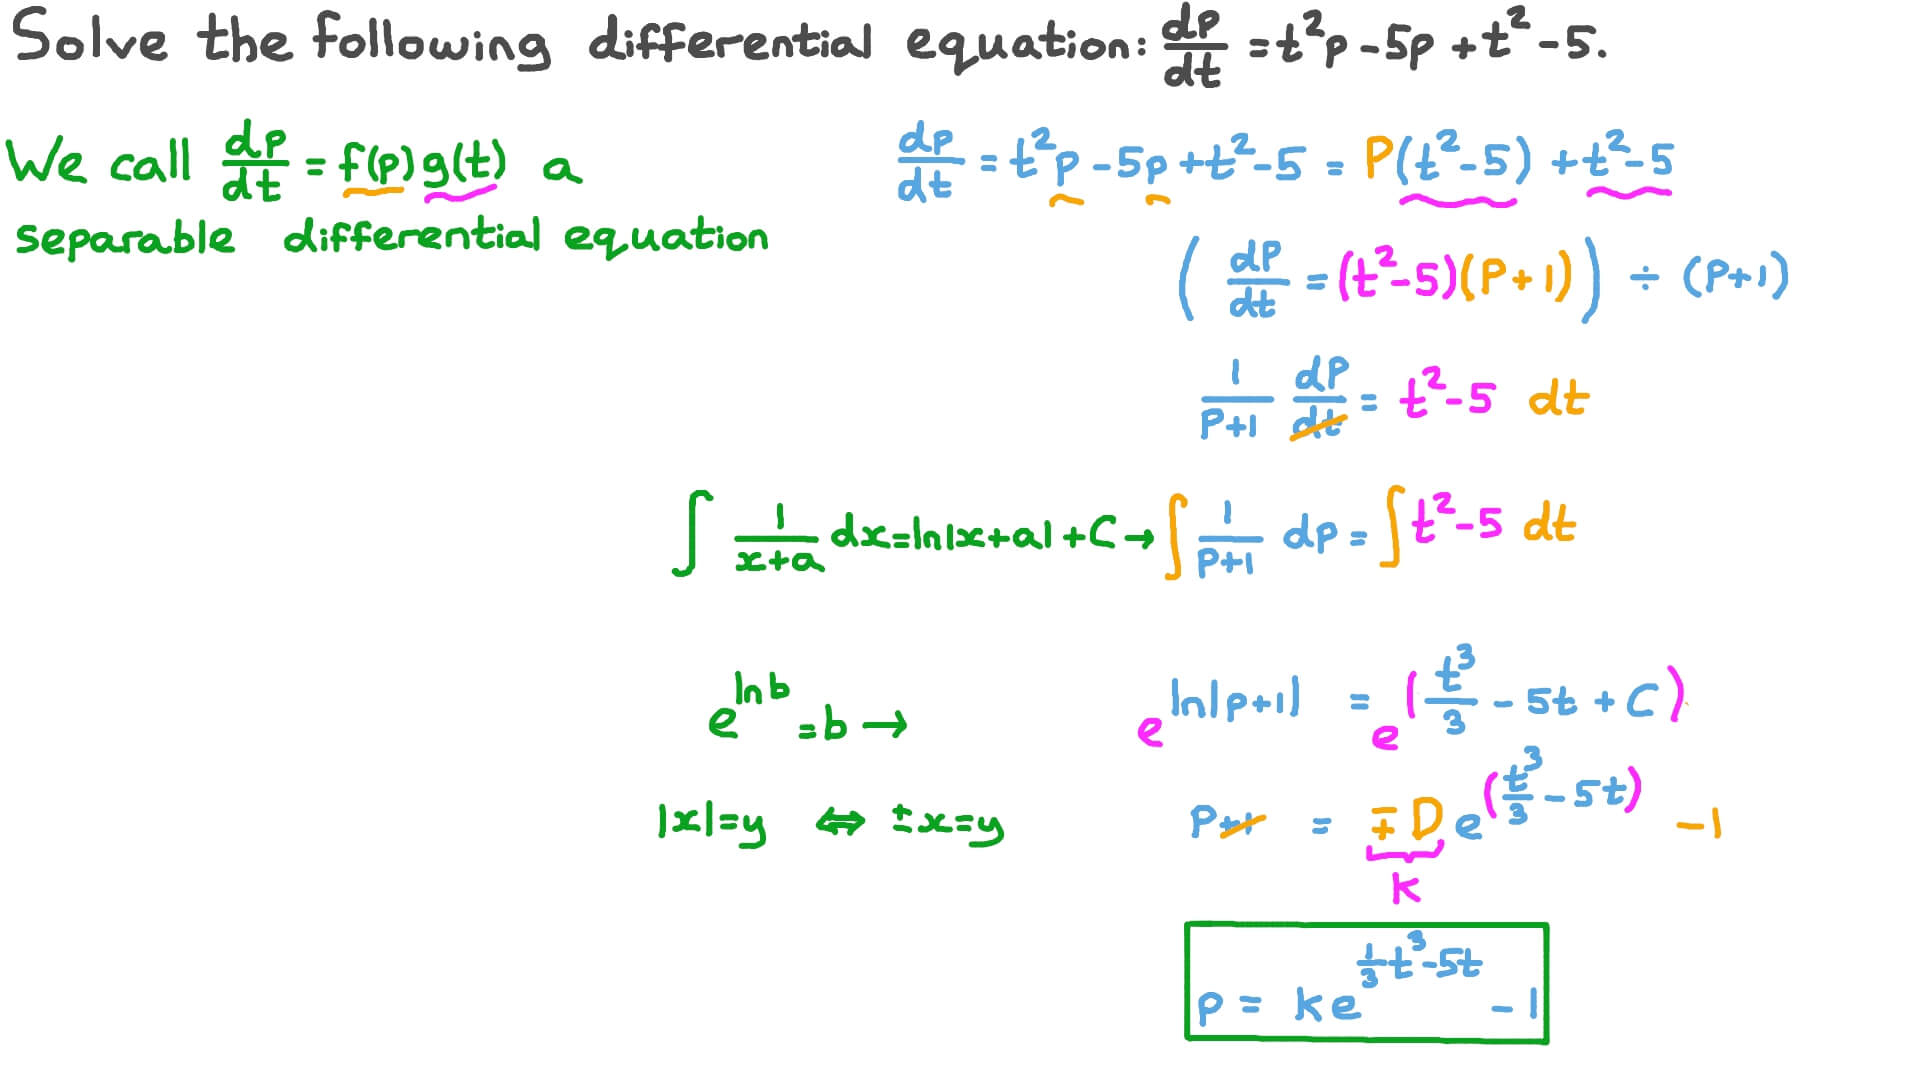
The single biggest mistake I see is dropping absolute value signs inside logarithms during separation of variables. When you integrate 1/y dy, the result is ln|y|, not ln(y). Omitting the absolute value restricts your solution domain unnecessarily and costs points on graded work. Another frequent error is forgetting to apply initial conditions to both constants in second-order problems. After finding the general solution with C and C, you need two conditions to solve for both. A single initial condition leaves one constant undetermined. Check your solutions by substituting back into the original equation. This takes thirty seconds to a minute and catches most algebraic mistakes. I do this on every problem I work through, even homework I'm not turning in. The habit prevents embarrassing errors during exams when there's no time for verification. Differential equations in Calculus 2 Differential Equations courses build directly on integration techniques and basic algebra. If your integration skills are weak, the differential equations will feel impossibly slow even when the conceptual steps are straightforward. Practicing integration by parts, partial fractions, and trigonometric substitutions separately first will make the actual equation-solving process significantly faster and less error-prone.