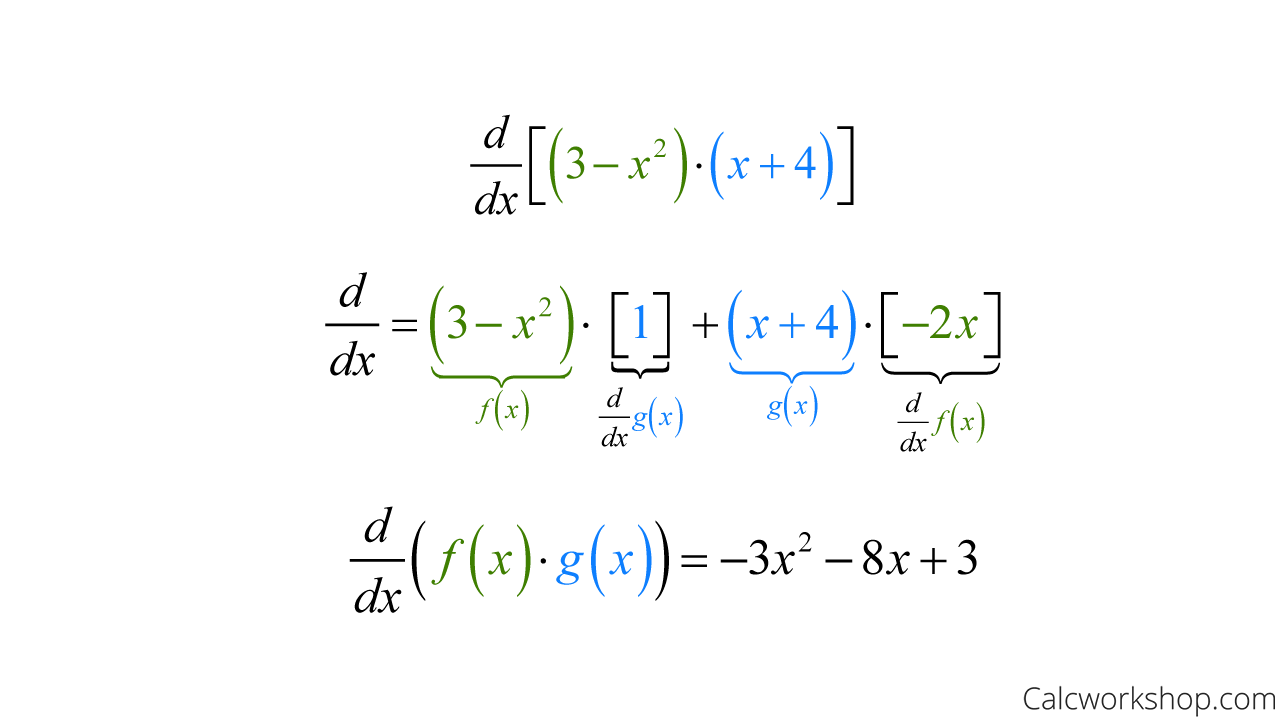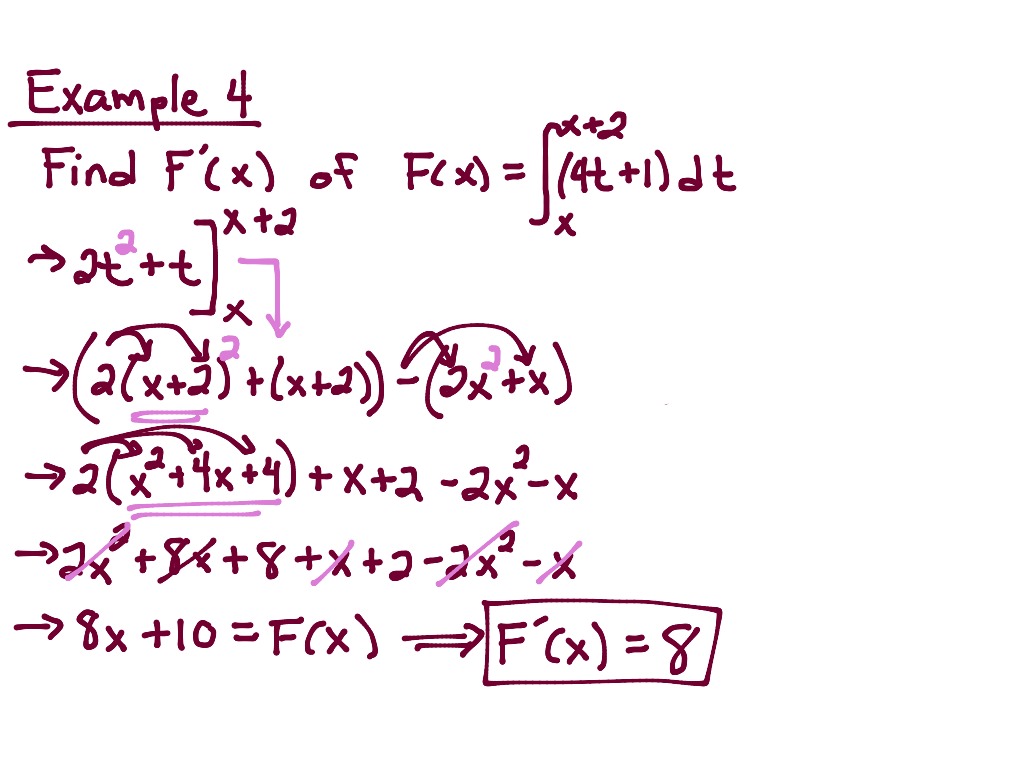
Understanding Calculus Through Practice
Most people hit a wall when they try to learn calculus from textbooks alone. You read the definition of a limit, then a theorem, then another definition, and your brain just blanks out. That is normal. The gap between understanding what a derivative is and actually using it to solve something is massive. What helps is working through concrete problems where the steps force you to make decisions rather than just follow a recipe. I have spent years watching students struggle with this, and the ones who actually get it are the ones who do problems until the techniques become automatic. There is no shortcut around that part. But there is a smarter way to approach it than grinding through hundreds of random exercises.Fundamental Calculus Examples for Building Intuition
Let's start with derivatives because they are where most people first get confused about what is actually happening. The definition of the derivative is f'(x) = lim[h0] [f(x+h) - f(x)] / h This limit expression is important, but it is also almost never used in raw form for actual calculations. What matters more is recognizing the pattern behind it. When you see something like d/dx [x³], you are asking what happens to x³ when x changes by a tiny amount. The power rule gives you 3x², but understanding why that works requires going back to the limit definition at least once, or the whole thing feels like magic. A problem that trips people up constantly is differentiating composite functions. Consider f(x) = sin(x²). The chain rule says you take the derivative of the outside function evaluated at the inside, then multiply by the derivative of the inside. So f'(x) = cos(x²) · 2x. Students routinely forget the second part and write cos(x²) by itself. I see this mistake in homework submissions at least once a week. It is not a subtle error either, but it happens because the chain rule has three pieces and the brain likes to skip the last one. For integration, the same pattern holds. Integration is really just reverse-engineering. When you see 2x dx, you are looking for a function whose derivative is 2x. The answer is x² + C, and the C is not optional notation, it is a necessary part of the answer because any constant disappears when you differentiate. Forgetting C is the integration equivalent of the chain rule mistake above. Integration by substitution is the workhorse technique. It is the reverse of the chain rule. If you have 2x·cos(x²) dx, you substitute u = x², which gives du = 2x dx, and the integral becomes cos(u) du = sin(u) + C = sin(x²) + C. The trick is recognizing which part of the integrand is the derivative of another part. That recognition comes from doing problems, not from reading explanations.One edge case that took me a while to internalize involves improper integrals where the function has a vertical asymptote within the interval. I was grading a problem set last semester and a student wrote ¹ (1/x²) dx = -1. The algebra looks right if you just plug in the bounds after finding the antiderivative, but the integral diverges because the function blows up at x = 0. The correct approach is to rewrite it as a limit: lim[a0] ¹ (1/x²) dx. When you evaluate that, you get lim[a0] [-1/x]¹ = -1 + lim[a0] (1/a), which goes to infinity. The takeaway is that you must always check for discontinuities inside the interval before applying the fundamental theorem of calculus directly.
Numerical methods come into play when analytical integration is impossible or impractical. Simpson's rule approximates f(x) dx using parabolic arcs instead of rectangles. With n = 4 subintervals, the formula is (h/3)[f(x) + 4f(x) + 2f(x) + 4f(x) + f(x)] where h = (b-a)/4. This usually gives results within 0.1% of the true value for smooth functions, and it runs in about 30 seconds by hand compared to the minutes required for trapezoidal approximation with the same accuracy. The limitation of numerical methods is worth being blunt about. They fail when the function oscillates rapidly or has sharp spikes that your subintervals miss entirely. If you apply Simpson's rule to ² sin(100x) dx with only 4 subintervals, you will get garbage. The rule of thumb is that your subinterval width should be smaller than the shortest period of oscillation in your function. For most engineering applications this is not a problem, but in signal processing contexts it catches people off guard. Series expansions are another area where practice separates people who understand from people who memorize. The Taylor series for e is 1 + x + x²/2! + x³/3! + x/4! + ... This series converges for all real x, which is unusual and useful. You can approximate e^0.5 by taking just the first five terms and getting 1 + 0.5 + 0.125 + 0.02083 + 0.00260 = 1.6484, which is close to the actual value of 1.64872. The error after n terms is roughly x¹/(n+1)!, so for x = 0.5 the error drops extremely fast. Taylor series also reveal something counter-intuitive about analytic functions. A function like e^(-1/x²) with the value 0 at x = 0 has all derivatives equal to zero at the origin, yet the function is not identically zero. Its Taylor series is just 0 everywhere, but the actual function has a flat bottom at the origin and rises elsewhere. This means the Taylor series does not always equal the function, even when all derivatives exist. Beginners are rarely prepared for this, and it is worth knowing because it shows the boundaries of what power series can do. For multivariable calculus, the gradient vector f = f/x, f/y points in the direction of steepest ascent. If f(x,y) = x² + 3xy + y², then f = 2x + 3y, 3x + 2y. At the point (1, 2), the gradient is 8, 7. The directional derivative in any direction u is f · u, which is maximized when u points in the same direction as the gradient. This geometric interpretation is more useful than the algebraic formula in most applications, especially in optimization and machine learning. Line integrals combine several concepts at once. If you have a vector field F = y, x and a curve C parametrized by r(t) = t, t² for 0 t 1, then _C F · dr = ¹ F(r(t)) · r'(t) dt = ¹ t², t · 1, 2t dt = ¹ (t² + 2t²) dt = ¹ 3t² dt = 1. The key step is substituting the parametrization into the vector field and dotting with the derivative of the parametrization. Skipping the parametrization substitution is the most common error. For double integrals, changing the order of integration can transform an impossible integral into a simple one. Consider ¹ ¹ sin(y²) dy dx. The inner integral has no elementary antiderivative, so you cannot evaluate it directly. But if you swap the order, the region is 0 x 1 and x y 1, which becomes 0 y 1 and 0 x y. The integral becomes ¹ sin(y²) dx dy = ¹ y·sin(y²) dy. Now u-substitution with u = y² gives (1/2)¹ sin(u) du = (1/2)(1 - cos(1)) 0.2298. This is a classic example where the order swap is not just convenient but necessary.