Working Through California Capital Loss Carryover
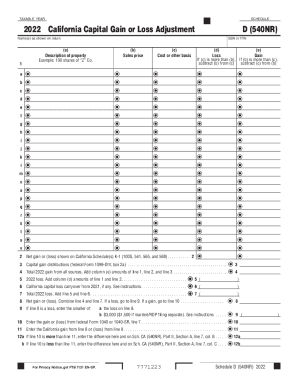
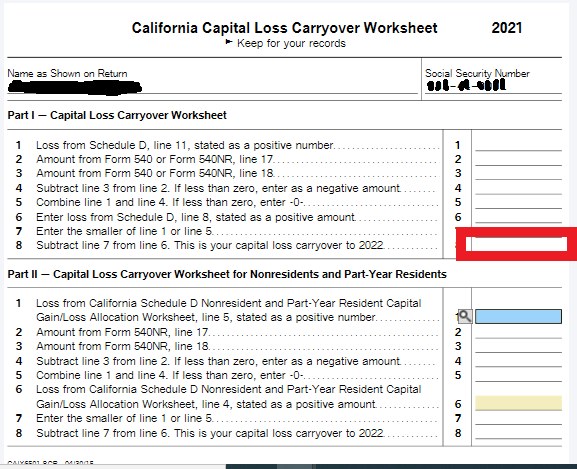
The California Capital Loss Carryover Worksheet is what you use when your capital losses on Schedule D exceed what the state allows you to deduct in a single tax year. California doesn't follow the federal rule that lets you carry forward unused capital losses indefinitely with no limit. Instead, there's a separate calculation that determines how much of your loss actually carries into next year, and it matters if you want to avoid leaving money on the table.The worksheet lives inside the California Schedule D instructions. You fill it out after completing your federal Schedule D and then translating those numbers onto your California return. Most people miss that the California amount can diverge from the federal amount depending on your situation. Here's how it actually works when you sit down with it. You start with your net capital gain or loss from the federal Schedule D, line 7. If that line is a loss, you enter it on the worksheet. Then you apply California-specific adjustments. The most common one involves wash sales. California disallows wash sales that the federal return already disallowed, but it also has its own rules about when a substantially identical security was purchased or sold. I ran into this a while back with a client who had traded a lot of tech options in early 2021. The broker reported all the wash sales on Form 8944, so the federal adjusted basis went up. But the California worksheet requires you to go back and check whether the California rules treat the timing differently for securities held outside of a regulated futures contract. The broker's summary didn't call out which transactions were affected, so I had to pull the trade confirmations manually and match each wash sale to the specific share lots. It took about three hours that shouldn't have been necessary. The workaround was to request a corrected Form 1099-B from the broker showing the California-specific adjustment codes, and when they couldn't provide it, I just manually recalculated the disallowed wash sale amounts by lot.
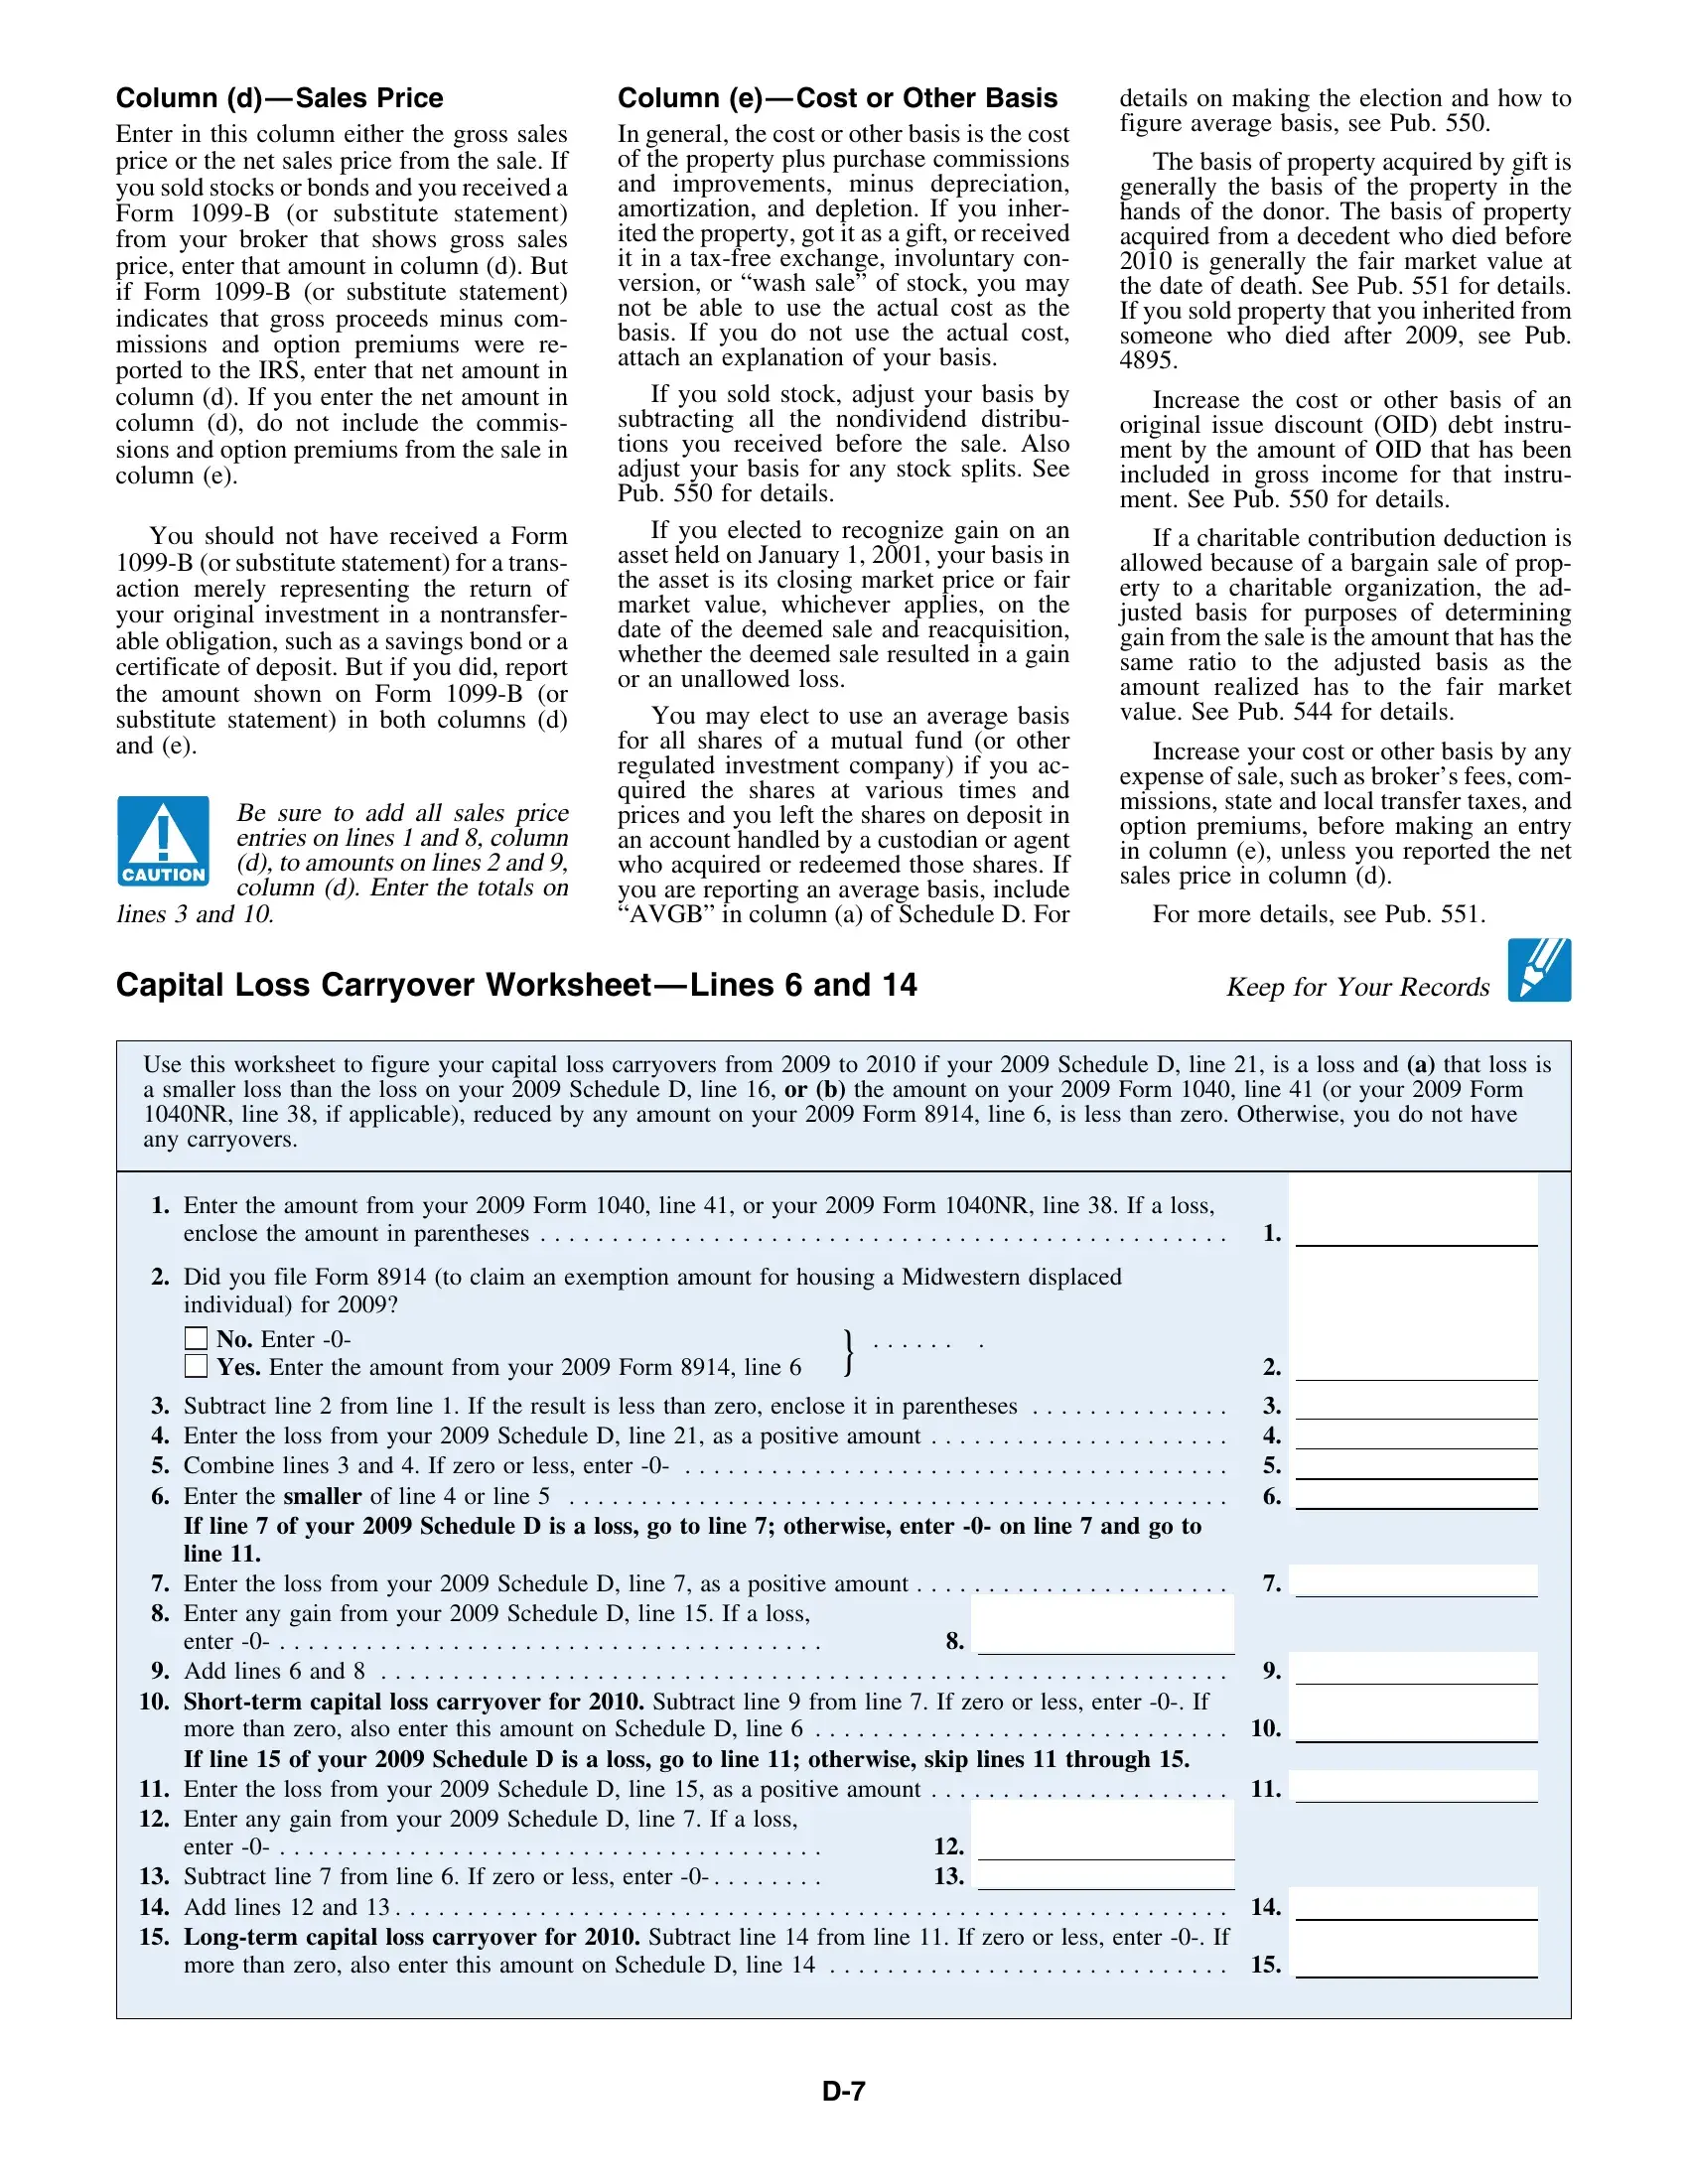
Another thing that catches people is the $3,000 limitation. On your federal return you can deduct up to $3,000 of net capital loss against ordinary income. California does the same, but the worksheet is where you figure out exactly how much of your loss is absorbed in the current year versus how much rolls forward. If your total capital loss is $15,000 and you have no capital gains to offset, you deduct $3,000 this year and carry forward $12,000. That part is straightforward. Where it gets messy is when you have a mix of short-term and long-term losses, because California requires you to track the character of the carryover. The $12,000 isn't just a generic loss pool. It's split between short-term and long-term portions, and each portion carries forward independently until used. There's a nuance most people skip. When you carry forward a capital loss to a future California tax year, it retains its original character as either short-term or long-term. That matters because short-term losses offset short-term gains first, and long-term losses offset long-term gains first. If you don't maintain that distinction on your records, you might end up using long-term losses to offset short-term gains in a year when you actually have short-term losses waiting to be used, which is a suboptimal ordering. I see this happen regularly with people who only look at the total carryforward number instead of the breakdown on the worksheet. The worksheet itself is a multi-step form. You enter the federal net capital loss, then add back any California adjustments like the wash sale disallowance, then subtract the $3,000 deduction limit, and whatever's left is your carryover. Lines 1 through 6 handle the computation, and line 7 is the final carryforward amount that you transfer to the next year's worksheet. If the result is zero or less, you carry nothing forward.
One practical detail: keep a separate spreadsheet or file for each year's carryover. The California Franchise Tax Board doesn't send you a confirmation that your carryover was accepted, so if you ever get an audit notice or need to reconstruct a prior return, you need to be able to show exactly how you got the number. A simple table with the year, total loss, federal amount, California adjustments, current-year deduction, and remaining carryover is usually enough. I recommend breaking it down by short-term and long-term since that split affects future calculations. If you're dealing with a complicated situation like gains from installment sales, in-substance sales, or losses from passive activities that interact with capital losses, the worksheet still applies but the inputs change. California Revenue and Taxation Code section 18621 governs capital gain and loss treatment for state purposes, and it diverges from the federal code in a handful of areas that feed into the worksheet calculation. You don't need to cite the code section on the form, but knowing it exists helps when you hit a scenario the worksheet doesn't seem to address directly. The biggest mistake I see is assuming the federal carryforward number is automatically the California carryforward number. They are rarely the same. Even a clean return with no wash sales will often produce a different California number because of adjustments to the basis of assets sold. The worksheet is designed to catch that divergence, but only if you actually fill it out instead of just carrying the federal line over by habit.
Get the Full Details