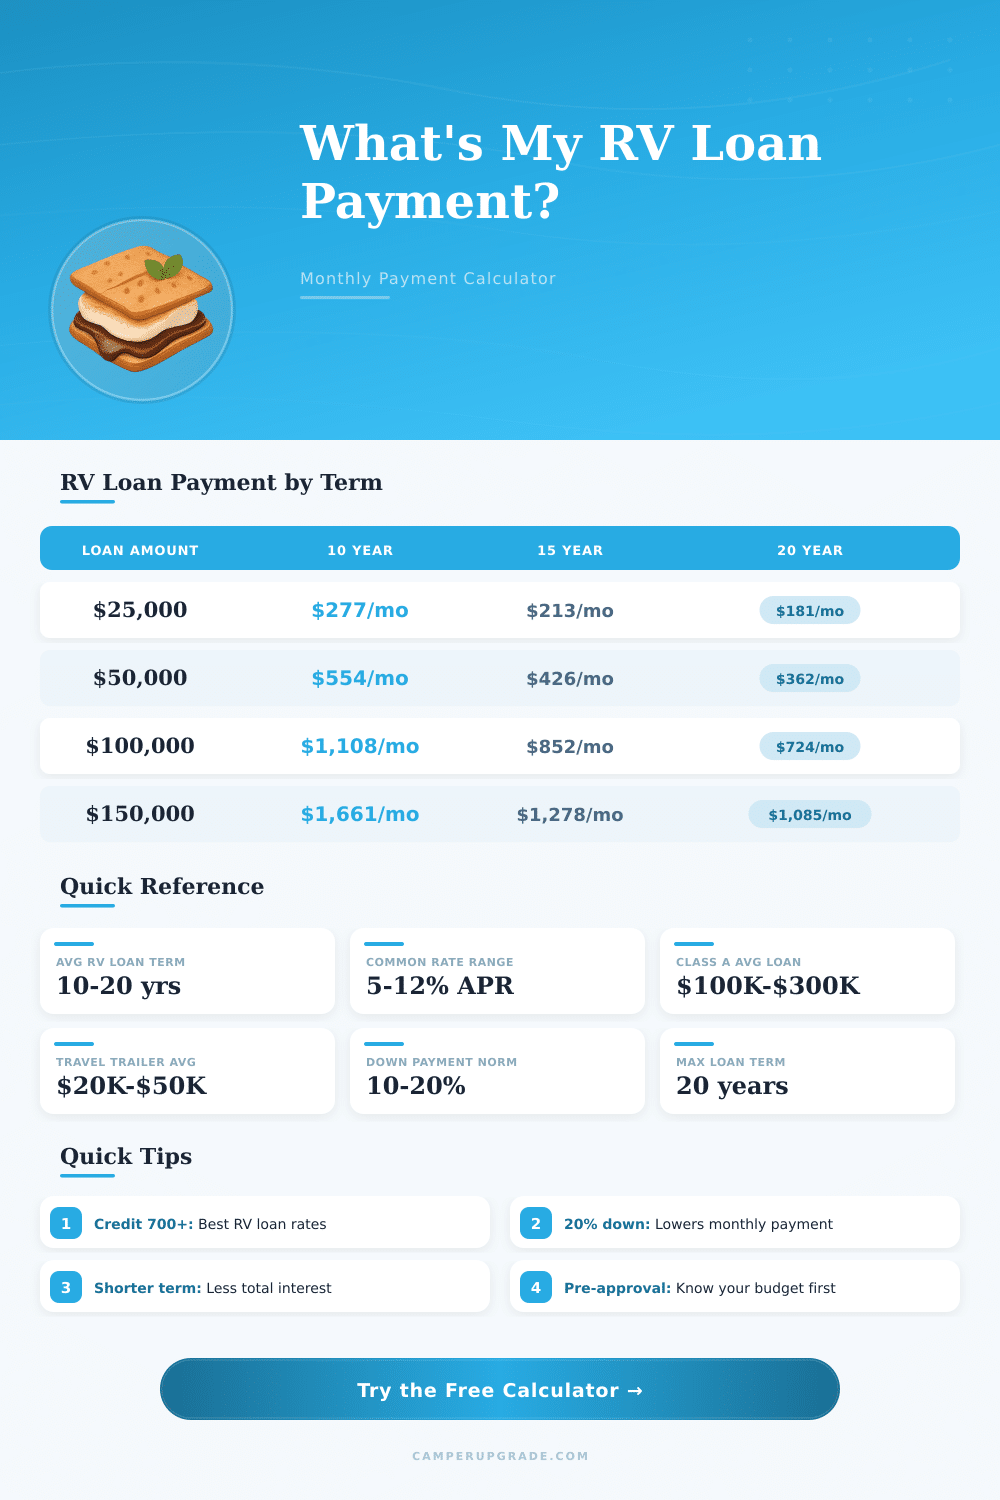
How Camper Loan Payment Calculators Actually Work in Practice
Most people treat these tools like they're just another online widget you plug numbers into and walk away from. That approach works fine for a basic estimate, but it falls apart the moment your financing gets complicated. I spent years working with recreational vehicle lenders before moving into advisory work, and I've seen more buyers get burned by a simplistic calculator result than by anything else in the loan process.
A Camper Loan Payment Calculator takes your principal, interest rate, and loan term and runs them through the standard amortization formula. The output is a monthly payment number. That's the simple version. The complicated version involves things like prepayment penalties, balloon payments, dealer markups on rates, and the way certain lenders structure seasonal camper loans differently from standard auto loans.
I learned this the hard way with a client who pulled up a free calculator online, saw a $420 monthly payment, and committed to a loan based on that number. The actual payment came out to $512. The calculator had assumed a 7.2 percent rate, but the dealer was offering him 11.4 percent. There was also a $1,200 documentation fee rolled into the principal that the tool didn't account for. He spent three weeks trying to renegotiate because he'd already signed the appraisal paperwork.
Using a Camper Loan Payment Calculator Without Getting Surprised
The trick is understanding what inputs you're actually allowed to control and which ones are going to shift once you talk to a lender. Here's how I walk people through it.
Start with the purchase price of the camper. Then subtract your down payment. That's your base principal. Next, figure out your credit tier. Not your score — your tier. Lenders group applicants into buckets like prime, near-prime, and subprime, and the difference between those buckets on a recreational vehicle loan can be three to five percentage points. A good Camper Loan Payment Calculator will let you adjust the rate manually so you can see the range instead of betting on one number.
Loan term is the next variable. Most people default to sixty or seventy-two months because the payment looks smaller. Longer terms cost more in total interest even though the monthly number drops. On a twenty-five thousand dollar loan at eight percent, a sixty-month term costs about $506 per month and $4,382 in total interest. The same loan at eighty-four months drops the payment to $389 but costs $7,698 in interest. That's a thirty-three hundred dollar difference for the convenience of a lower monthly number.
Here's something most calculators won't tell you: many camper loans are structured as secured personal loans rather than auto loans. That changes how prepayment works. With an auto loan, you can usually pay down the balance without penalty. Some RV lenders use pre-computed interest formulas where paying early doesn't save you as much as you'd expect. I've seen contracts where a borrower paid off half the principal in year two and still owed roughly seventy percent of the original interest charge. Always check whether the loan uses the rule of 78s or simple interest amortization before you sign anything.
Another edge case that trips people up is the gap between the calculator's monthly payment and what actually gets withdrawn. If your lender processes payments on the first but your first due date lands on the fifteenth, you might end up with a partial month where interest accrues differently. A few lenders also advertise a lower rate that only applies if you have automatic payments set up. The rate jumps if you pay by check or mail. That difference matters more than you'd think on a long-term loan.
The realistic range for a camper loan payment on a mid-range fifth wheel or travel trailer comes out to somewhere between $350 and $700 a month depending on how much you put down and what rate you qualify for. Anything outside that band usually means either a very large loan, a damaged credit profile, or a lender charging fees that inflate the effective rate well beyond the advertised number.
I keep a spreadsheet alongside whatever calculator I'm using. I plug in the calculator's result, then I add a column for the total of all fees rolled into the loan — document fees, destination charges, extended warranty add-ons that get financed. That adjusted principal is what actually determines your payment. The free online tools rarely let you input dealer fees separately. You have to do that math yourself or find a calculator that supports added principal fields.
One more thing worth noting: camper loans often have higher rates than car loans because the depreciation curve is steeper and the collateral is harder to repossess. A recreational vehicle sits in a yard somewhere and can't be jumped and driven away like a sedan. Lenders price that risk in. Expect rates roughly one to two points above what you'd see on a new car loan with the same credit profile. If a dealer tells you the rate is the same as automotive financing, verify it independently before you proceed.
Gallery Camper Loan Payment Calculator
This RV Loan Calculator Will Help You Figure Out Your Monthly Payment ...
This RV Loan Calculator Will Help You Figure Out Your Monthly Payment ...
Camper Payment Calculator Tool (Easy to Use) - Used Rv Campers Travel ...
This RV Loan Calculator Will Help You Figure Out Your Monthly Payment ...
RV Loan Calculator - Estimate Monthly RV Loan Payments