Figuring Out What You Actually Owe on a Camper
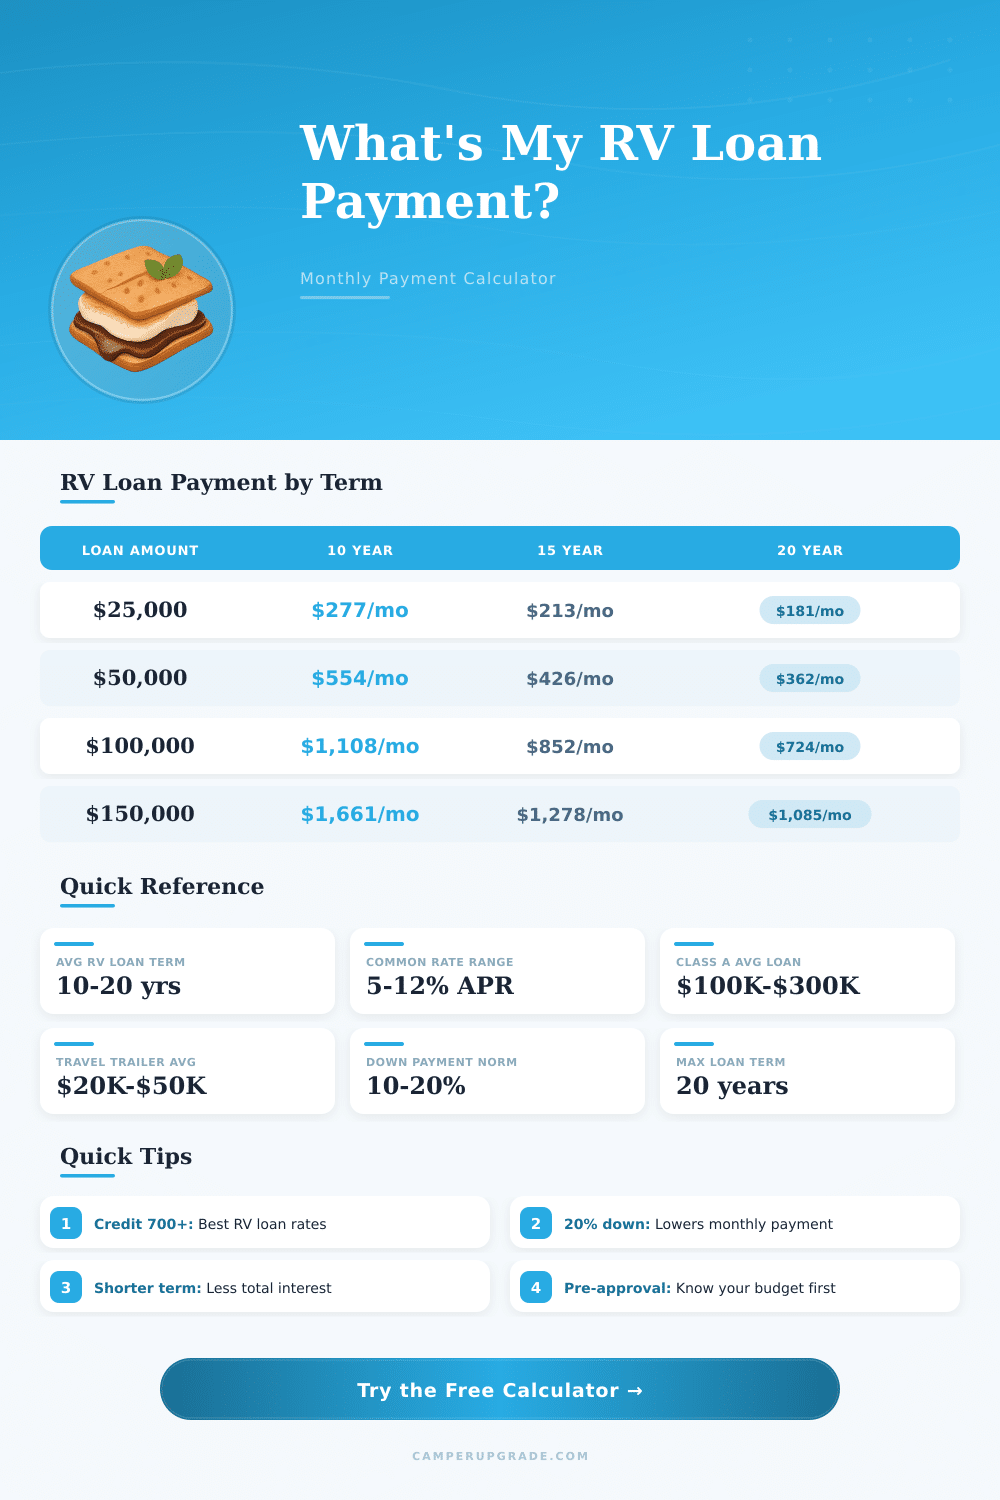
You buy a camper, you see the sticker price, and then someone hands you a payment sheet that looks like it was designed by a spreadsheet junkie. A Camper Payment Calculator is just a tool—usually web-based, sometimes a phone app—that takes your down payment, interest rate, loan term, and the total price and spits out a monthly number. That's the whole thing in one sentence. The problem is that most people don't realize how much the input variables actually matter until they've already signed the paperwork. I spent about six months working with dealership financing for a travel trailer purchase a few years back, and I went through roughly a dozen different calculators before finding one that didn't lie to me. Here's the part nobody tells you: most consumer-facing calculators assume a simple amortization schedule, which means they evenly split principal and interest across every month. That's fine for a mortgage. It's not always fine for an RV loan, especially if your dealer is rolling in taxes, registration fees, and documentation charges into the financed amount without clearly separating them. My specific headache was with a 2019 Class C that the dealer quoted at $42,500. The calculator on their website showed a monthly payment of $687 at 5.9% for 72 months. It sounded reasonable until I added up the actual numbers. The price wasn't $42,500. It was $42,500 plus $1,800 in destination charges, $650 in documentation fees, $420 in title and registration (varies by state), and they'd tacked on a $1,200 extended warranty into the loan without asking me first. So the actual amount being financed was closer to $46,570, not $42,500. The real payment was more like $752, not $687. I caught it because I ran the numbers through an independent Camper Payment Calculator after the fact and the discrepancy was glaring.
The workaround I used was simple but annoying. I got the dealer to give me a written breakdown of every line item before I agreed to anything. Then I plugged the gross capitalized cost—the actual total amount being financed—into a calculator that let me adjust for pre-computed interest. Some online tools don't do that. The ones from Credit Karma and NerdWallet do, and they also flag if the payment seems off compared to current rates. I cross-referenced three different calculators. That's overkill for most people, but when you're looking at six-figure RVs, overkill is just careful. Here's the counter-intuitive part that trips people up repeatedly: a lower monthly payment doesn't mean a better deal. In fact, it often means the exact opposite. Dealers will happily extend your loan term to 84 or even 96 months to drop your payment by a couple hundred bucks. That sounds great on the surface. The total interest paid over 96 months at 6.5% on a $45,000 loan comes out to roughly $9,800. On a 60-month term at the same rate, total interest is about $4,600. You're paying double in interest just to keep the monthly number comfortable. I've seen this happen at three different dealerships in two states. Another nuance that beginners miss involves balloon payments. Some RV lenders offer structures where your monthly payment is calculated as if you'll pay off most of the principal at the end, but the balloon itself isn't always highlighted in bold. If you're not careful, you could be locked into payments that look affordable and then suddenly owe $12,000 in a single lump sum. A proper Camper Payment Calculator will show you the balloon amount if the loan has one, but many free online versions don't. You need to ask your lender directly whether the loan is fully amortizing or balloon-structured. Don't assume.
The tool itself isn't complicated to use, but the inputs matter far more than the output. Here's what you actually need before you open a calculator: the out-the-door price including all fees, your actual credit score tier (prime, near-prime, subprime), the loan term you're considering, and whether any fees are being rolled into the loan or paid upfront. The last one changes your effective interest rate significantly. Rolling $2,000 in fees into a 72-month loan at 7% costs you about $380 in additional interest compared to paying those fees at signing. That's the kind of detail that separates a good deal from a mediocre one.
Get the Full Details
When a Camper Payment Calculator Fails You
These tools are only as good as the assumptions baked into them. They don't account for variable-rate loans that adjust after an initial period, which some RV lenders use as a promotional tool. They don't factor in GAP insurance costs unless you manually add them. They ignore the fact that your state may have different sales tax treatment for RVs versus personal property, which can change the capitalized cost. And they certainly don't catch dealer-added products like tire and wheel protection, paint sealants, or key fob fees that sometimes appear as line items on invoices without explanation. If you're buying from a private seller and paying cash, you don't need any of this. But if you're financing through a credit union, a dealer's captive lender, or a specialty RV loan provider, running your numbers through a calculator is essential. Credit unions typically offer rates that are 1 to 2 percentage points lower than dealer arrangements. On a $50,000 loan over 60 months, that difference alone saves you roughly $1,600 in total interest. A Camper Payment Calculator will show you that number immediately if you plug in both rates side by side. I'd recommend using an independent calculator rather than the one on the dealer's website. Dealer calculators are designed to make the payment look smaller, not to give you accurate total-cost information. Free options like the one on Bankrate or the auto loan calculator at NerdWallet will work. Just make sure you're entering the gross capitalized cost, not just the MSRP. The distinction matters more than most people think.
There's also a timing consideration. RV prices tend to dip slightly in late fall and winter as dealers clear inventory for new model years. If you're shopping between October and February, you might find better negotiation leverage. The payment calculator won't tell you that, but your wallet will notice the difference when the selling price drops by a few thousand dollars on the same trailer.