What 501(c)(3) Status Actually Means for Political Activity
The short answer is no, but the reality is messier than that. A 501(c)(3) organization can engage in limited political activity, but crossing certain lines jeopardizes the entire tax-exempt status. I deal with this constantly and it is not a gray area in the way most people assume. The IRS code under section 501(c)(3) prohibits any substantial part of an organization's activities from being political campaign intervention. This means you cannot endorse or oppose candidates for public office, directly or indirectly. You also cannot make contributions to political campaigns. These are hard stops. But there is room for issue advocacy and nonpartisan voter engagement, which is where people get confused. I worked with a cultural nonprofit a few years back that wanted to host candidate forums. The straightforward approach would have been to invite all candidates in a race and present them equally, which is perfectly legal. Instead, they invited two out of four candidates because the other two were unknown. That imbalance alone raised flags during our review. The workaround was straightforward: we restructured it as a single-topic policy discussion open to all candidates, sent identical written questions to everyone including the two who declined to attend, and published all responses on the organization's website regardless of whether the candidate showed up. That kept everything at arm's length from any appearance of endorsement.
Where the Real Boundaries Sit
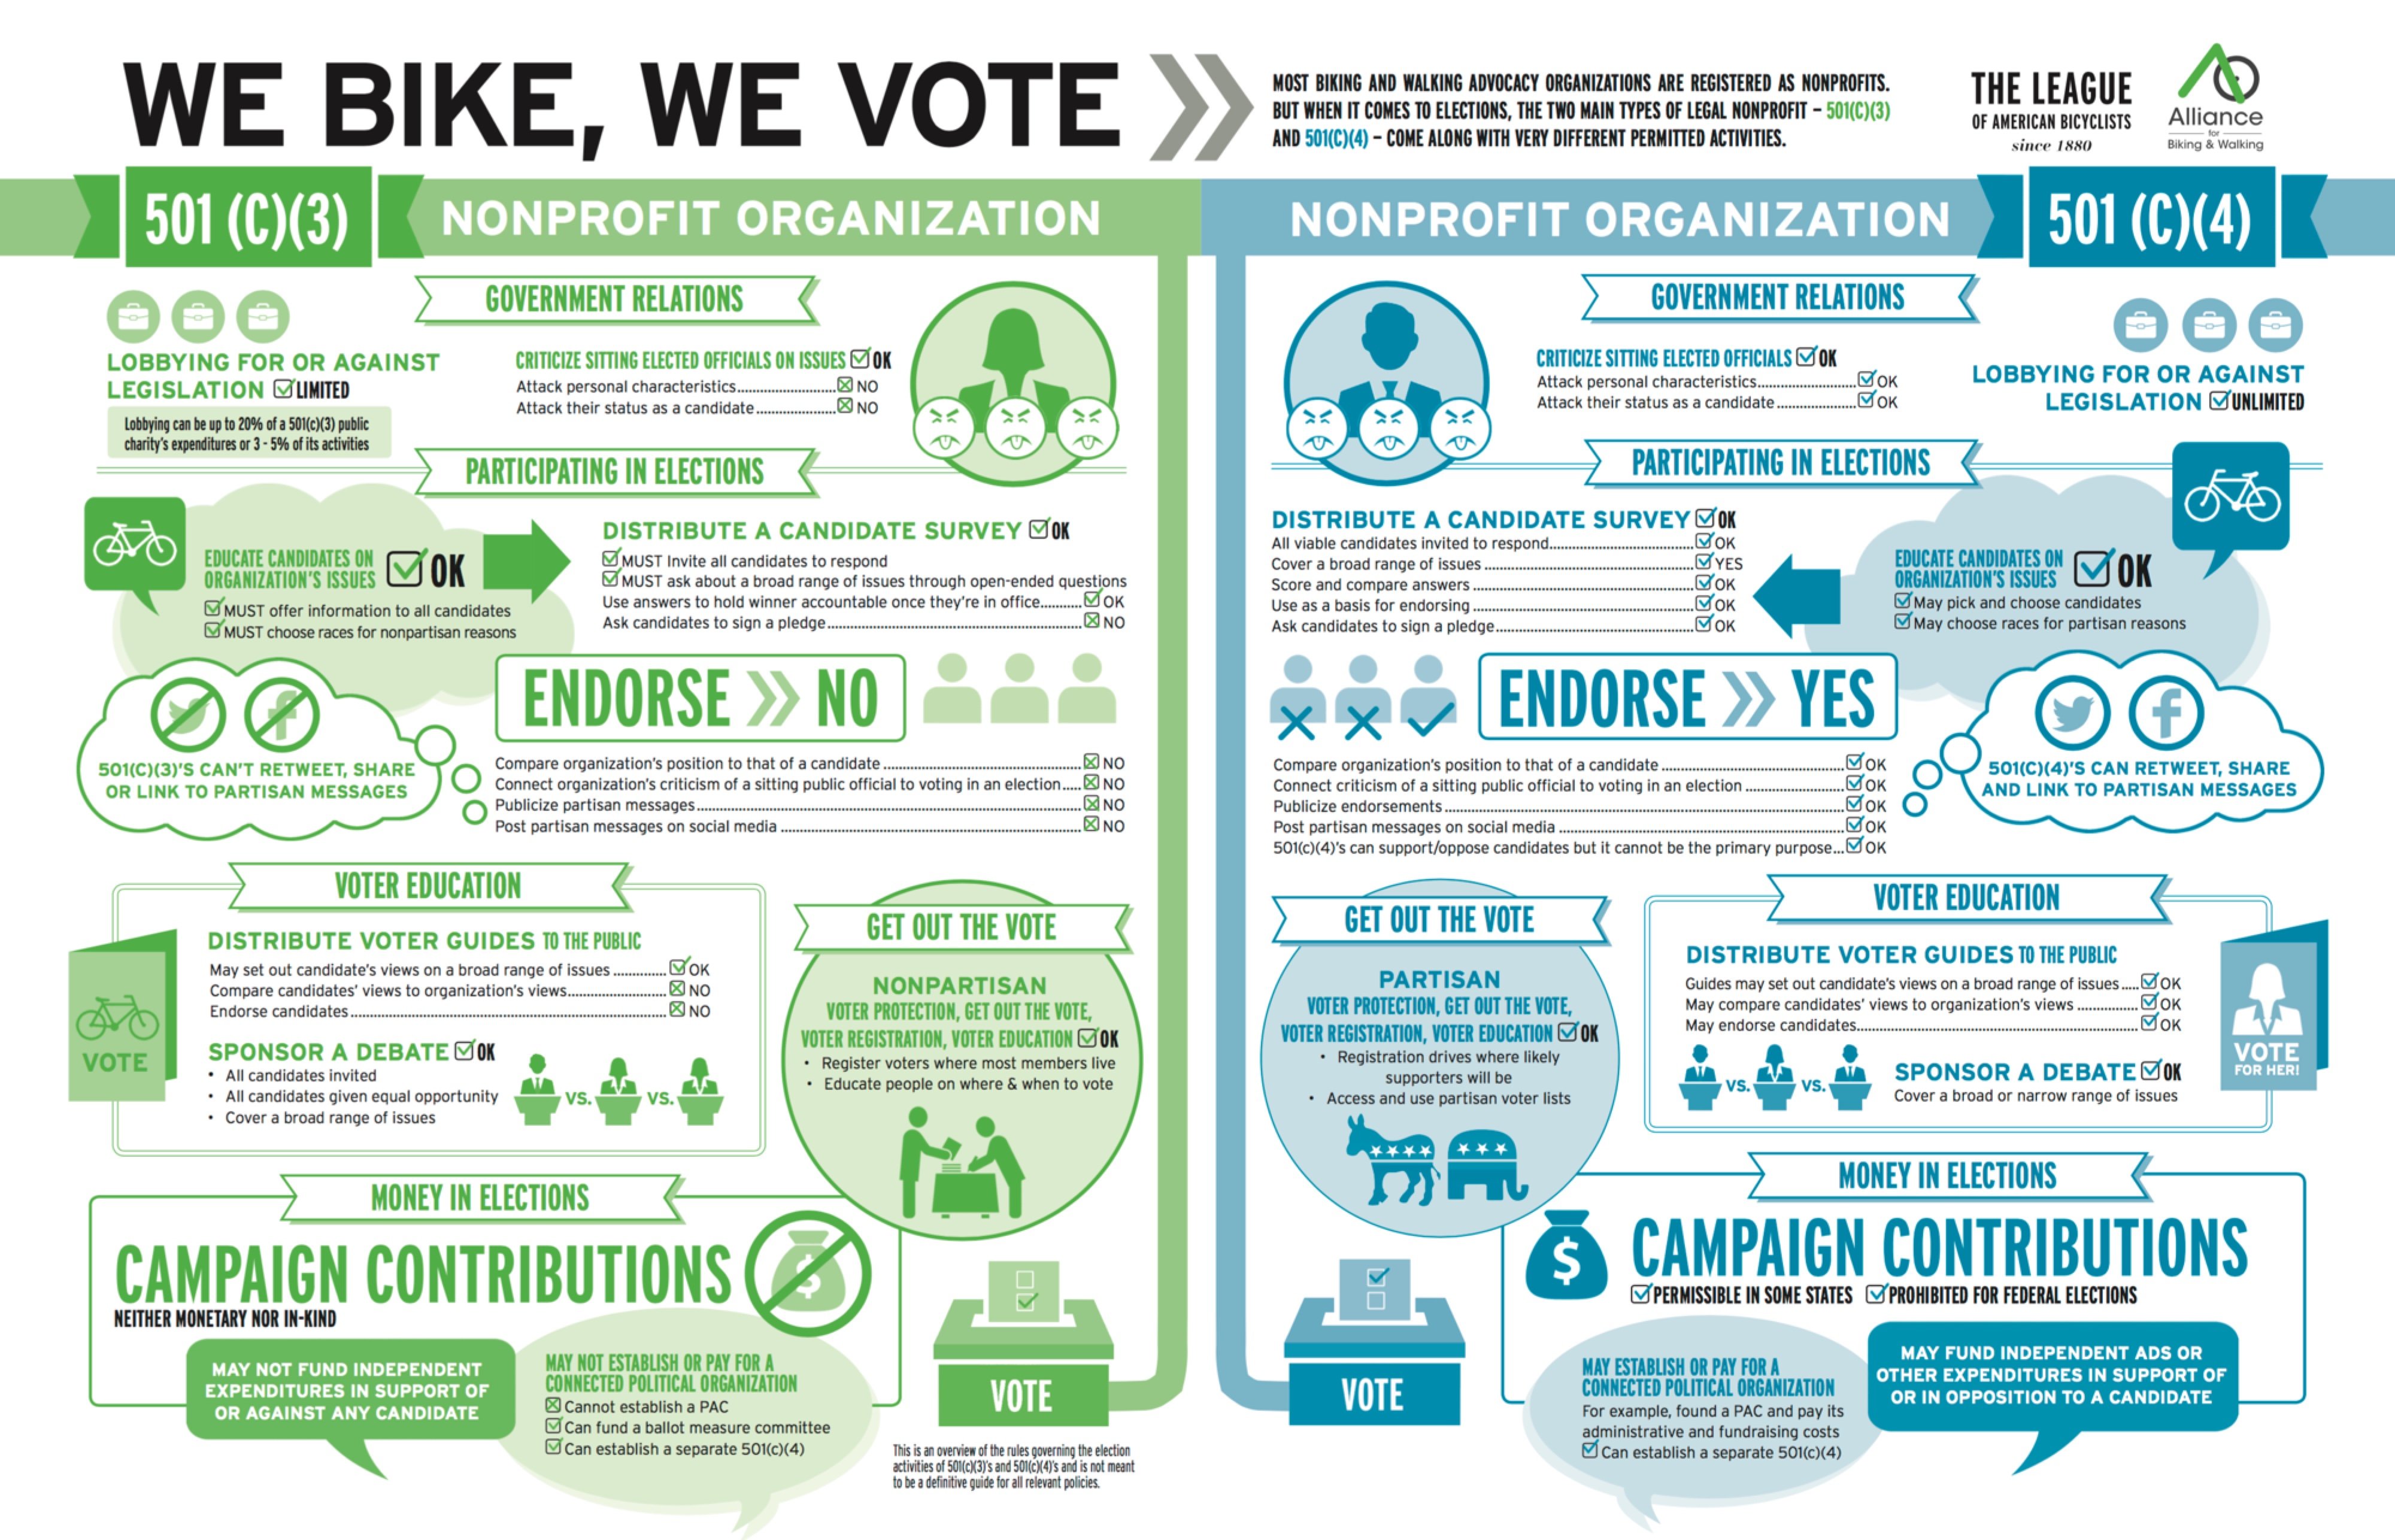
There are three categories of political activity and each has different rules attached. Political campaign intervention is the big one. This includes any action that supports or opposes a candidate, whether through public statements, endorsements, or even coordinating with a campaign. The prohibition applies regardless of whether the organization claims it is nonpartisan. A 501(c)(3) cannot contribute money to a candidate, cannot coordinate advertising that clearly favors one candidate over another, and cannot allow campaign events on its premises under conditions that suggest approval. Legislative lobbying is the second category and it is governed by different rules. 501(c)(3) organizations can lobby on legislation, but the amount must be insubstantial relative to overall activities, or the organization must file Form 5768 to elect the expenditure test under section 501(h). Under the expenditure test, there are specific dollar limits based on organizational budget. For a typical mid-sized nonprofit with an annual budget around $500,000, the lobbying ceiling works out to roughly $150,000 per year with no more than $500,000 in a single year. These numbers are not trivial constraints if your mission involves advocacy.
Nonpartisan voter engagement is the third category and it is where most nonprofits operate safely. Getting out the vote drives, publishing unbiased candidate guides, hosting forums with balanced candidate participation, and registering voters are all fine. The key word is balanced. If your voter registration drive disproportionately targets demographics that lean one way, the IRS could view that as disguised partisan activity even if the intent was neutral.
Get the Full Details
The 501(h) Election Is Worth Understanding
Most 501(c)(3) organizations never file Form 5768. They operate under the insubstantiality test, which is vague and subjective. The IRS does not publish bright-line percentages for what counts as substantial lobbying, which means organizations either guess or stay far below any reasonable threshold. Filing the 501(h) election replaces that guesswork with specific dollar limits and reporting requirements. You file annual Form 990-L to report lobbying expenditures. The tradeoff is administrative overhead, but the clarity is significant. I had a client who was spending roughly $40,000 annually on policy advocacy without filing the 501(h) election. When we ran the numbers against the insubstantiality standard, their lobbying was easily 15 percent of total expenses. That is well into dangerous territory under the subjective test. After switching to the 501(h) election, the same level of advocacy became completely under the explicit expenditure limits. The filing took about an hour and the ongoing reporting is built into the regular 990 cycle.
Common Pitfalls That Surprise People
Grants to candidates are forbidden. This sounds obvious but it comes up. A 501(c)(3) cannot give money to a candidate's campaign under any name. Fellowship programs, stipends, and project grants are fine as long as they are awarded through a genuinely neutral, nonpartisan selection process with no connection to electoral activity. The moment the selection criteria reference campaign performance or electoral success, the grant becomes prohibited. Website and social media require the same scrutiny. Organizations often think the political activity rules only apply to live events and public statements. They do not. A blog post on the organization's website that discusses a candidate's record while ignoring competing candidates can be construed as campaign intervention. The IRS looks at the totality of the communication, not just whether the word endorse appears. Coalition work creates exposure. When a 501(c)(3) joins a coalition that engages in political activity, the IRS may attribute the coalition's activities to the member organization if the 501(c)(3) is involved in planning or decision-making. The safe approach is to participate only in the coalition's nonpolitical activities or to keep the participation purely observational without voting or strategic input on political matters.
Independent expenditure rules do not protect 501(c)(3)s. Some organizations believe that if they make independent expenditures rather than coordinated ones, they are safe. That logic applies to 501(c)(4) organizations, not 501(c)(3)s. A 501(c)(3) cannot make independent expenditures supporting or opposing candidates at all. The prohibition is absolute regardless of coordination.
What Happens If You Cross the Line
The IRS can impose excise taxes under section 4955 for political intervention by a 501(c)(3). These start at 25 percent of the expenditure for the organization and 5 percent for managers who approved it. If the violation is repeated or egregious, the organization can lose its 501(c)(3) status entirely. Loss of tax-exempt status means donations are no longer tax-deductible, which is usually catastrophic for fundraising regardless of the political activity scale. The 990 questionnaire now asks specific questions about political campaign activities, so the IRS is actively screening for this during the annual filing review. Organizations that ignore the question entirely or provide vague answers often find themselves in audits that could have been avoided with proper documentation from the start.
Practical Steps for Compliance
Write a formal policy document that covers candidate-related activity, lobbying limits, and event guidelines. Have it reviewed by counsel before adoption. Train staff and board members annually. Keep detailed records of all events, communications, and expenditures related to any political activity. File the 501(h) election if lobbying is a material part of your work. And when in doubt, assume the more restrictive interpretation because the IRS does not negotiate these matters retroactively. The framework is workable. Most 501(c)(3) organizations engage with public policy every day without violating the rules. The problems arise when organizations treat the restrictions as suggestions rather than boundaries. Understanding where those boundaries actually sit before you reach them saves considerably more effort than trying to recover from an IRS finding after the fact.