Cell Phone Deductions Actually Work, But Only If You Track the Right Numbers
The short answer is yes, you can write off your cell phone for business, but the mechanism is more restrictive than most people expect. The IRS treats cell phones under the "de minimis fringe benefit" rule and as a business expense deduction depending on how you use it. Most self-employed people and small business owners take the simplified approach, which means either deducting the business-use percentage of their phone bill or electing to expense the device itself under Section 179. Both paths are legitimate. Neither one is as simple as just buying a phone and slapping a receipt in your shoebox. This is the question that comes up constantly in my inbox, usually from people who just bought a new iPhone and want to know if they can deduct the whole thing. The answer depends entirely on your business structure and whether the phone is in your name or your employer's name. If you're a W-2 employee, the rules changed dramatically after the Tax Cuts and Jobs Act of 2017. Miscellaneous itemized deductions tied to un-reimbursed employee expenses are suspended through at least 2025. That means if your employer doesn't reimburse you, you're out of luck for now. If you're a sole proprietor, LLC, S corp, or C corp owner, you're in a much stronger position. I had a client last year who ran a marketing consultancy out of her home and bought three phones — one for herself, one for her assistant, and one she kept in her car for client pickups. She wanted to expense all three under Section 179 and take the full deduction. The problem was she couldn't substantiate the business use percentage on the assistant's phone because there was no written policy or usage log. The IRS would have disallowed that one on audit. What we ended up doing was documenting a clear business purpose for each device, establishing a written expense policy, and filing Form 4562 for the 179 election. The assistant's phone got a 60% business-use deduction based on her call logs and app usage reports, while the car phone was 100% deductible since it was dedicated to client calls only.
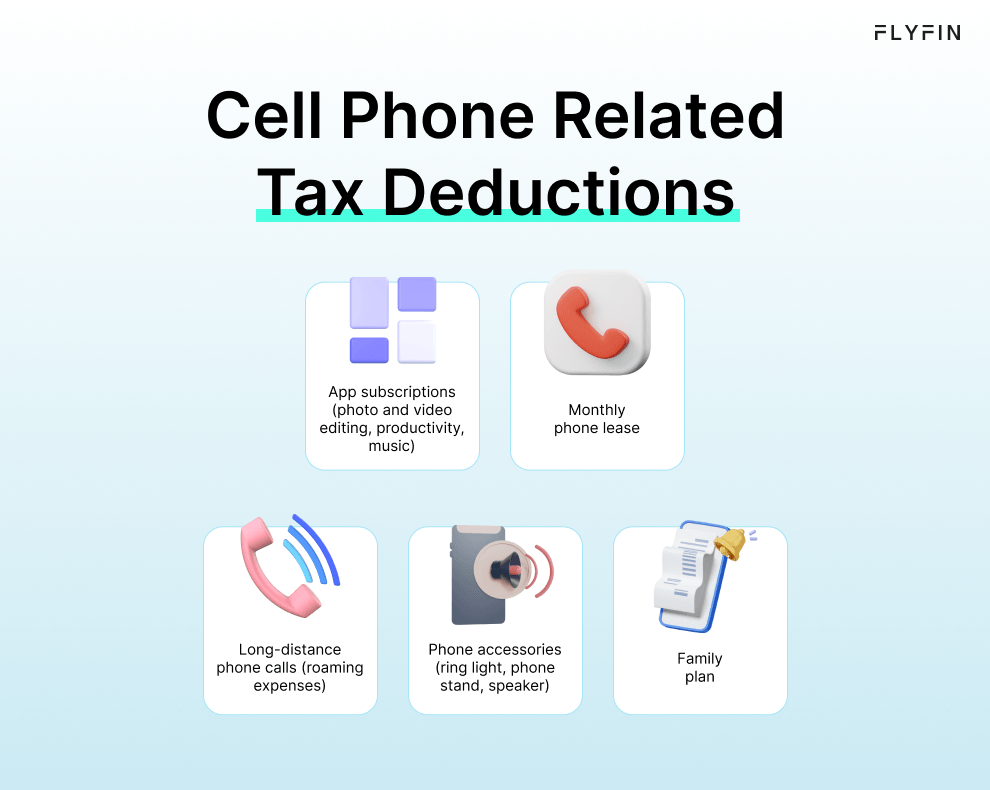
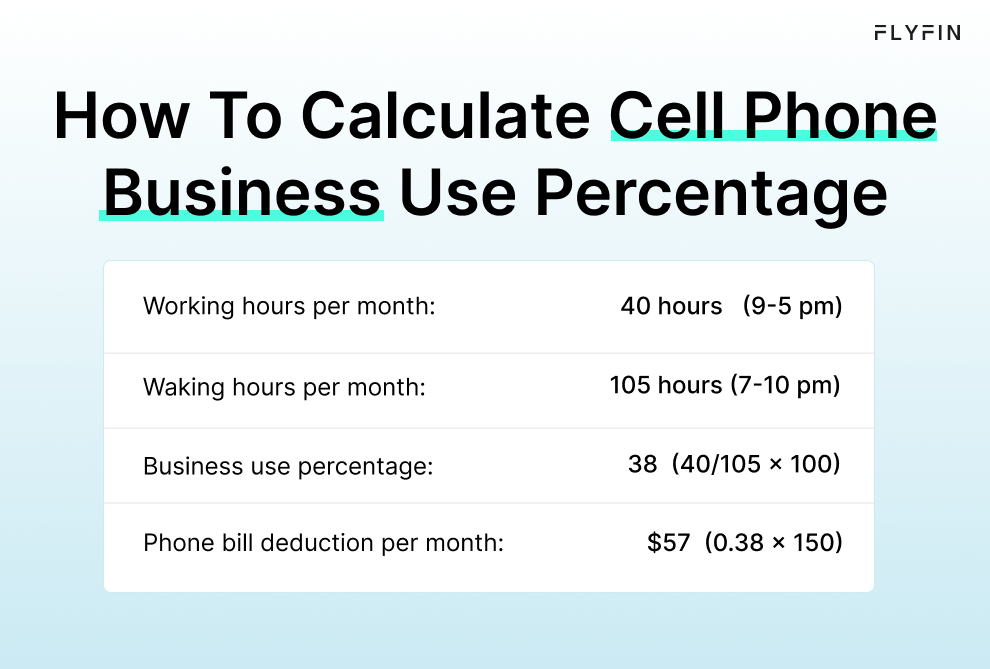
Here's how the actual deduction works in practice. There are two main methods and you pick one based on your situation. The first is the simplified method, also called the standard mileage equivalent for phones, where you deduct a percentage of your actual monthly bill. If your phone is used 70% for business, you deduct 70% of each bill. This is straightforward but you need to be able to show that percentage. The second is the Section 179 election, which lets you expense the full cost of the phone in the year you place it in service, up to the annual limit — that's $1,220,000 for 2026, phased out dollar for dollar after $3,050,000 in total equipment purchases. A phone almost never hits that ceiling unless you're outfitting an entire sales team. The catch that nobody tells you is depreciation recapture. If you take Section 179 on a phone and then sell it or stop using it for business before the end of its useful life, you have to recapture the deduction as ordinary income. Phones have a 5-year MACRS life for depreciation purposes, so even though you wrote it off immediately, the IRS still considers it a depreciable asset. If you switch to personal use halfway through the year, you've got a partial recapture event on your hands. I've seen people lose entire deductions because they forgot to track when a phone stopped being used for business. Another thing that trips people up is the difference between expensing the device and deducting the service plan. These are two separate deductions. You can expense the phone hardware under 179 and separately deduct the business portion of your monthly bill. Or you can skip 179 entirely and just deduct the business percentage of everything — phone plus plan. The choice matters if you're near the Phase-Out threshold for Section 179 or if you want to spread the deduction across multiple years to optimize your taxable income. A lot of accountants recommend the latter for higher-income business owners because taking a massive 179 deduction in a high-income year might not be optimal if you expect to make even more next year.
Documentation is where most people fail. The IRS doesn't require you to keep itemized call logs for a phone deduction the way they do for vehicle mileage, but you do need to be able to substantiate your business-use percentage if audited. I recommend saving your monthly bills and making a simple spreadsheet showing total monthly cost and business percentage. Take a screenshot of your phone's screen time or call detail report once a year to lock in your percentage. If you change your usage pattern significantly — say you go from 50% business to 80% — update the percentage and document why. A single sentence explaining the change is enough. There's also a special case worth mentioning. If your phone costs $2,500 or less, you might be able to use the de minimis safe harbor election under Treasury Regulation 1.263(a)-1(f). This lets you deduct the cost as an expense rather than capitalizing and depreciating it, which simplifies things significantly. You don't need to file Form 4562 for the phone itself. The tradeoff is that the safe harbor requires an written accounting policy on file before the end of the tax year, and the policy has to apply consistently across all similar assets. For a sole proprietor with one or two phones, this is usually the cleanest path. If your business has multiple employees with company phones, the picture gets more complex. You need individual business-use percentages for each device, a written expense reimbursement policy, and proper record-keeping for each employee. The safest approach is a formal phone allowance policy where you either reimburse employees for their actual business use or provide them with a set stipend. Reimbursements under an accountable plan are not taxable income to the employee and are fully deductible by the business. Stipends that exceed actual business use become taxable wages. This is one area where a bad setup can create unexpected payroll tax liabilities.
Get the Full Details
The bottom line is that writing off a cell phone is legitimate and straightforward if you follow the rules. Pick your method, document your usage percentage, keep your bills, and make sure the phone is actually used for business. Don't claim 100% if it's partly personal. Don't expense a phone you bought for your kid. Don't skip the documentation because "the IRS won't ask." They will ask, and when they do, you need to be ready with a paper trail that tells a consistent story.