Why Your Rental Payments Aren't Showing Up (And How to Fix It)
Most landlords don't report rent to the major credit bureaus by default. I've watched people move into apartments for three years straight, pay on time every month, and have absolutely nothing on their credit file to prove it. The reason is straightforward: credit reporting isn't automatic for rent. It has to be set up intentionally, and most lease agreements don't include it. The short answer is yes, but not through any path your landlord takes on their own. You or your property management company need to actively enroll a payment reporting service. There are a handful of companies that specialize in this—RentTrack, Rental Kharma, Esusu, and GoodRenters are the ones I see most often. They partner with landlords or property managers to submit monthly rent data to Experian, and in some cases TransUnion and/or Equifax, depending on the service. I ran into a specific problem last year working with a client who had used Esusu for about eighteen months before her credit was damaged by a medical issue. She wanted to dispute a late payment that showed up on her Experian report, but Esusu's dispute resolution process required her to contact the service directly through their portal first. She tried calling her landlord to verify the payment history, and the landlord said the report data wasn't actually pulled from their records—it was pulled from Esusu's ledger. The landlord couldn't help because Esusu controlled the data. My workaround was to have my client export her full payment history from the Esusu dashboard as a PDF, file a formal dispute with Experian attaching that PDF, and cite the FCRA right to accuracy. The dispute was resolved in about 45 days, and the inaccurate late mark was removed. Not the smoothest process, but it worked.
Here's what nobody tells you: even if your rent gets reported, it may only show up on one bureau. Experian's rent program is the most widely adopted because Experian actively built a product around it. TransUnion and Equifax will also pull in rent data if a service submits it there, but the coverage is spotty. A lot of people add their rent to Experian and never realize they're missing it on the other two. If you're building credit from scratch or rebuilding after damage, you want rent reporting across all three bureaus, so verify which ones your chosen service covers before you commit. There's also a nuance with how the data gets pulled. Some services use open banking—they link directly to your checking account and pull transaction data. Others rely on manual landlord submission. The manual submission route introduces a delay that can stretch three to six weeks before your first payment shows up. With open banking, the data flow is usually faster, but it requires you to grant account access to the service. I've seen people skip the verification step and assume their rent would start reporting immediately. It doesn't. You need to confirm with the service that the first month's payment was successfully submitted after the reporting cycle closes. One important caveat: negative rent history isn't automatically reported by most of these services. The standard model only submits positive payment data. That means being late on rent won't hurt your credit through these channels, but it also means if you do fall behind and your landlord decides to take legal action or send your debt to collections, that collection account will show up regardless. I've seen rental debt sent to collections after a single missed payment at a smaller apartment complex that didn't use a reporting service at all. The debt collector reported it to all three bureaus, and that negative entry stayed for seven years. The rent reporting services don't protect you from collections activity—they only add positive data.
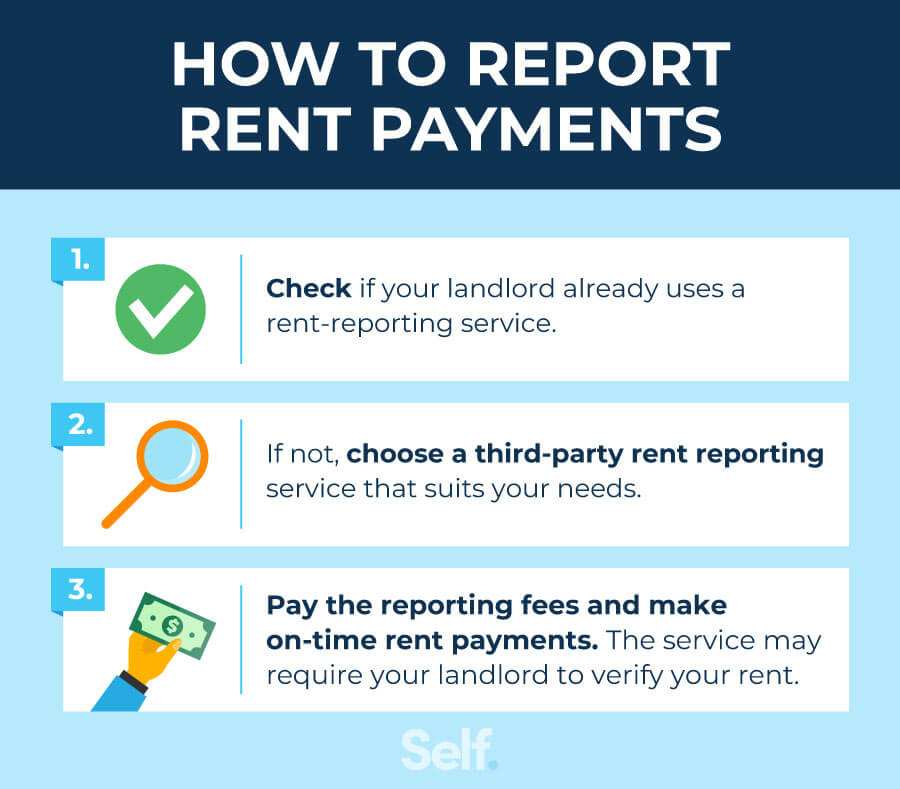
For people looking to start, the process is relatively simple. You pick a service, create an account, verify your identity, link your rental information, and confirm that your landlord participates or agrees to the arrangement. Some services charge a monthly fee—usually between four and eight dollars. Others are free for renters and charge the landlord or property management company instead. If you're on your own lease without a property management company, make sure the service you choose works with individual landlords, not just large corporate complexes. I once recommended a platform to someone who moved quickly without checking, and it turned out the service only worked with buildings that had fifty or more units. He wasted two weeks setting it up before discovering the mismatch. The bottom line is that adding rent to your credit report is a legitimate tool for credit building, but it's not a universal fix. It takes time to start showing results—usually four to six months before the data appears on your reports. It won't help if you're already deep in delinquency. And it won't prevent landlords from sending you to collections if you stop paying. But for someone with thin credit or a damaged file who has been consistent with their rent, it can add a meaningful positive tradeline that lenders see.
Get the Full Details