What This Model Actually Does for You
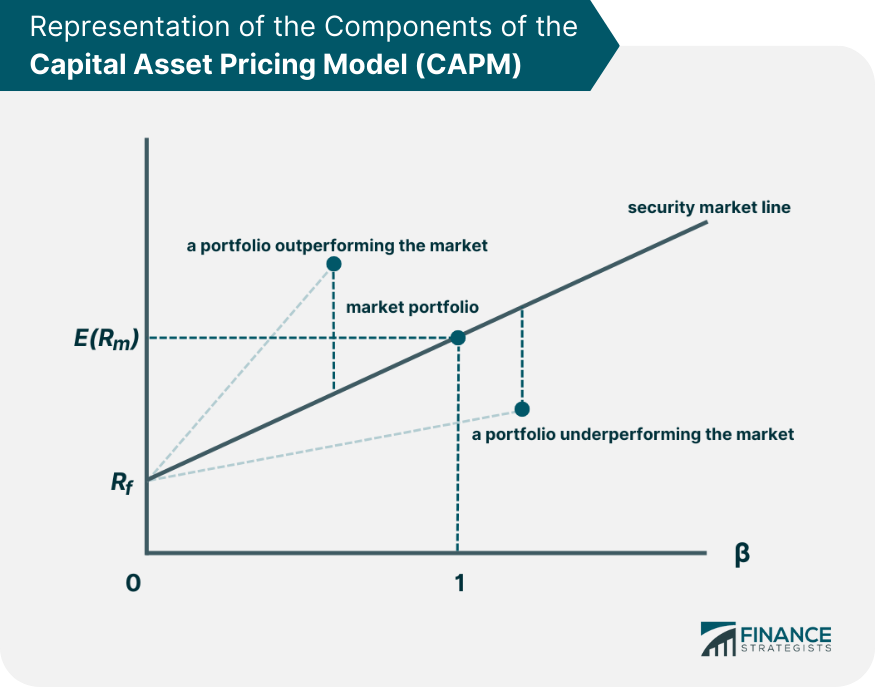
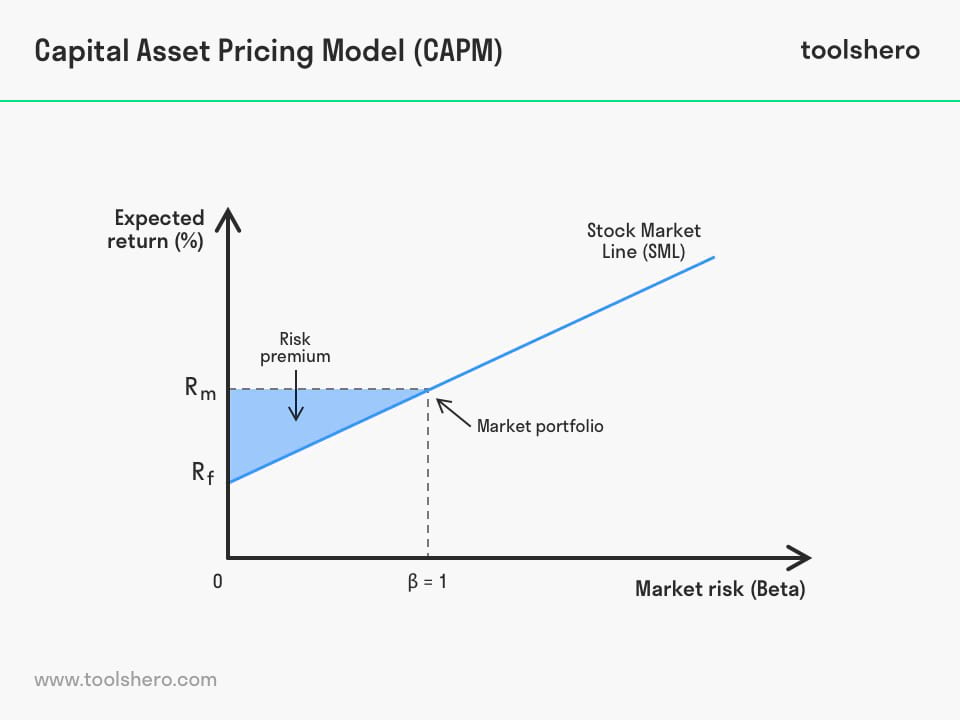
The Capital Asset Pricing Model Explained is really just a way to figure out what return you should expect from an investment given its risk level. That's it. The equation itself is deceptively simple: expected return equals the risk-free rate plus beta times the market risk premium. Everything else in finance builds around this basic relationship between systematic risk and compensation. But I have spent more years than I care to count watching people misuse this model or pretend it predicts things it cannot predict. Let me walk you through how it actually works in practice, where it breaks down, and what you should do about it.
Capital Asset Pricing Model Explained in the Real World
When I first started using CAPM in portfolio construction, I treated the numbers as gospel. Beta from Yahoo Finance, risk-free rate from the ten-year Treasury yield, market premium set at five percent because that is what most textbooks use. The outputs felt authoritative. They were not. Here is what I learned the hard way. Beta is not a stable property of a stock. It changes over time, and the standard calculation using daily returns over the past two years gives you a number that is already halfway wrong by the time you compute it. I once had a pharmaceutical company with a beta of 0.85 looking completely flat compared to the market, but their actual movements during clinical trial events made them behave like a three-beta stock during specific windows. CAPM could not see that coming because it only measures past covariance.
The Math Behind the Numbers
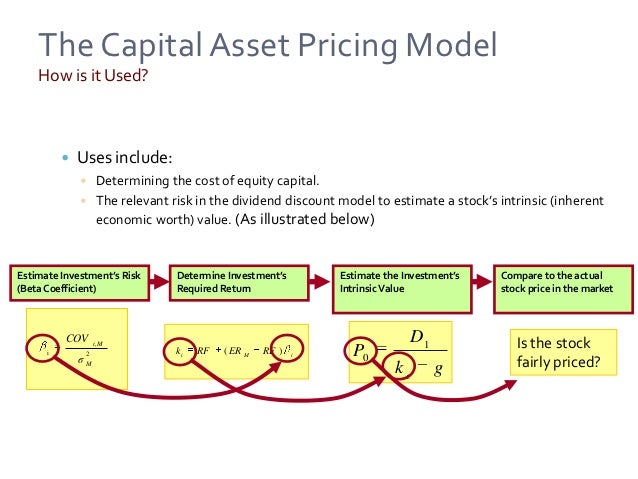
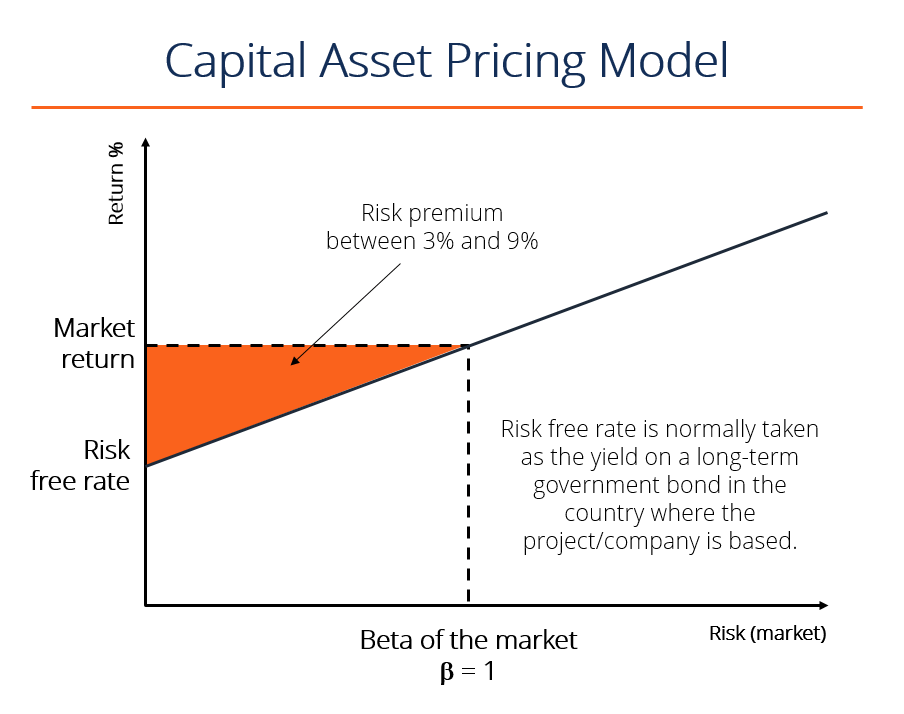
The core equation is E(Ri) = Rf + i × [E(Rm) - Rf]. You plug in the risk-free rate, usually something around four to five percent depending on which Treasury maturity you trust, then estimate the market return expectation, subtract to get the premium, multiply by beta, and add the result back to the risk-free rate. The output tells you the required return for that asset given its systematic risk exposure. Beta itself comes from a regression of the asset's returns against the market's returns. The slope coefficient is your beta. If the stock moves in lockstep with the market, beta is one. If it moves twice as much, beta is two. If it barely moves when the market moves, beta could be zero or negative. Negative betas are rare and usually associated with gold stocks or put options disguised as equities. The market risk premium is the hardest parameter to pin down. Historically it has averaged somewhere between four and seven percent depending on which time period you examine. Some researchers argue for using forward-looking equity risk premiums based on dividend discount models. Most practitioners just pick five percent and move on. I picked five percent for a long time until I realized that matters more than people admit when you are valuing companies with high betas.
Get the Full Details
Where CAPM Fails and What to Do Instead
The biggest problem with CAPM is that it assumes markets are efficient and that all investors hold diversified portfolios. Neither assumption survives contact with actual markets. Individual investors do not hold the market portfolio. Many institutional portfolios are concentrated. And market efficiency is a spectrum, not a binary state. When I was building valuations for a private equity firm, we used CAPM as a starting point but immediately layered in size premiums, illiquidity discounts, and sector-specific adjustments. A small-cap biotech company with a beta of 1.2 might realistically require an eight or nine percent premium over the risk-free rate, not the six percent CAPM would spit out. We adjusted the model rather than abandoning it entirely. Another issue I encountered involves emerging market investments. The standard risk-free rate does not apply when you are dealing with currencies that devalue unpredictably and political risks that have nothing to do with market beta. I started using country risk premiums added on top of the base CAPM calculation, pulling numbers from firms like Aswath Damodaran who publish updated estimates quarterly. This made the outputs actually useful for deal screening.
Practical Implementation Steps
If you want to calculate CAPM yourself, start by gathering daily or weekly returns for your asset over a meaningful time period, ideally three to five years. Longer periods capture more market cycles but may include structural changes that make older data irrelevant. For most U.S. equities, daily returns against the S&P 500 work fine. Use a spreadsheet or Python if you have access to it. Next, determine your risk-free rate. The ten-year Treasury yield is standard but not perfect because it does not match the holding period of many investments. Some analysts use the three-month T-bill rate for shorter horizons. Pick something consistent and document why. For the market return expectation, you can use historical averages, forward-looking estimates, or a combination. The FAA report from 2025 highlighted that many analysts still rely on the flawed historical approach and suggested alternative methodologies using survey-based expectations. Consider that when you are making decisions that will matter in five years rather than relitigating what happened in the last fifty.
Calculate beta by regressing asset returns against market returns. Make sure you are using excess returns, not raw returns, for both the asset and the market. This is a common mistake I see constantly. Subtract the risk-free rate from each return series before running the regression.

The Multi-Factor Alternative
When CAPM proves insufficient, the Fama-French three-factor model adds size and value factors to the mix. The Carhart four-factor model adds momentum. These capture variation in returns that beta alone misses. I found the three-factor model particularly useful when evaluating small-cap value stocks that consistently outperform what CAPM predicts. For most practical purposes, CAPM remains the baseline. It is simple, transparent, and understood by everyone from CFA candidates to board members. The question is never whether to use it but how to adjust it for the realities your specific investments face. Track your assumptions carefully, test sensitivity to different premium levels, and do not present the output as anything more than an estimate grounded in a set of debatable inputs. The model will not replace fundamental analysis or qualitative judgment. But when used correctly with proper adjustments for illiquidity, size, and market structure, it provides a reasonable framework for thinking about risk and return that has survived decades of academic criticism and practical abuse.