The Reality of Picking Which Projects Get Funded
When I was at my last firm, we had a spreadsheet that ran every capital budgeting decision. It was 40 columns wide, took three days to refresh, and nobody actually read the output. That is the thing about these processes—they tend to become rituals rather than decision tools. The actual work sits underneath all of that formatting. Capital budgeting decisions usually involve analysis of cash flow projections, discount rates, risk adjustments, and opportunity costs across multiple competing projects. That is the textbook version. The real version involves arguing with someone in operations about whether the revenue forecast for year four is realistic, which it never is.
Capital Budgeting Decisions Usually Involve Analysis Of
The core methods you will encounter are net present value, internal rate of return, payback period, discounted payback, profitability index, and accounting rate of return. Each one answers a slightly different question and each one can mislead you if you treat it as gospel. I NPV is the one that matters most. It tells you the absolute dollar value added by a project. If it is positive, the project should theoretically increase shareholder wealth. If negative, it destroys value. Simple in theory. Not simple when you are trying to justify a $12 million piece of equipment to a CFO who just lost money on a similar project three years ago. The IRR gives you a percentage return. It is easy to talk about—"this project returns 18 percent"—but it has real problems. It assumes reinvestment at the IRR itself, which is almost never realistic. It also breaks down when cash flows flip signs more than once. I once saw an IRR calculation come out to three different valid numbers for a single project because of a mid-project salvage value combined with an environmental cleanup cost in year seven. Three IRRs. Which one do you present?
The payback period is what most non-finance people prefer. It answers "how fast do I get my money back?" It ignores the time value of money entirely, which is a flaw, but it is also a useful sanity check. A project that pays back in eight years when your average asset life is six is probably not worth doing, regardless of what the NPV says. I always run payback alongside NPV so I can flag those mismatches early.
Get the Full Details
Discount Rates and Why They Are Where Things Fall Apart
The discount rate is the single biggest lever in the entire model. Change it by two percentage points and a project that looks great today looks terrible tomorrow. Most companies use their weighted average cost of capital as a starting point, then adjust up or down based on perceived risk. That adjustment is where politics lives. I learned this the hard way on a manufacturing expansion project. We used a 10 percent discount rate. The NPV was solid at around $3.2 million. Then during the review, someone suggested we bump the rate to 12 percent because "the sector has been volatile." At 12 percent, the NPV dropped to negative $400,000. The project died. Not because the economics changed, but because someone moved a slider. That happened at least twice a year in my experience. The workaround I settled on was simple: run the model at three discount rates—your base case, a stress case, and a best case—and present the range. It made it harder for anyone to kill a project with a single arbitrary adjustment. It also made the discussion about what assumptions actually mattered instead of turning into a fight over a number.
Cash Flow Estimation Is Where Real Errors Hide
Revenue projections are almost always optimistic. Cost estimates are almost always low. This is not because people are dishonest. It is because forecasting demand three years out is genuinely difficult and because operational teams have incentive to understate costs to get projects approved. Both behaviors are rational from their perspective. Neither helps your analysis. I started requiring a post-audit component on every project we funded. Six months after launch, we compared actual cash flows to the forecast. The pattern was consistent: revenue came in at about 78 percent of projection, operating costs came in at about 115 percent. We adjusted the forecasting process accordingly. After that, our hit rate on capital projects improved noticeably because we stopped being naive about our own assumptions. Opportunity costs are another area people routinely miss. If you use an existing building for a new project, the foregone rent is a real cost. Land already owned has a cost if it could be sold or leased. These are not cash outflows today, but they are cash flows you are giving up. I have seen entire proposals skip this step and it skewed the results badly.
Sensitivity and Scenario Testing
A single NPV number is never enough. You need to understand what breaks the model. I usually run a sensitivity table on the three most uncertain inputs—revenue growth, unit costs, and the discount rate. A tornado diagram helps visualize which variable moves the needle the most. In practice, it is almost always revenue assumptions that create the biggest swing, followed by cost overruns. Scenario testing goes further. You build a worst case, a base case, and a best case with internally consistent assumptions for each. The worst case should not be catastrophic nonsense. It should be plausible. If your worst-case scenario requires oil prices to triple and a pandemic simultaneously, nobody will take it seriously. Ground your scenarios in things that have actually happened in your industry.
When Capital Budgeting Methods Fail You
NPV can give you the wrong answer when comparing projects of very different sizes. A $500,000 project with an NPV of $120,000 looks better than a $5 million project with an NPV of $80,000. But the larger project is creating more total value even though the percentage return is lower. Use the profitability index in those cases to compare efficiency of capital deployment. IRR fails completely with non-conventional cash flow patterns. If a project has an initial outflow, then inflows, then another large outflow later—say for regulatory compliance or decommissioning—you can get multiple IRRs or no IRR at all. In those cases, stick with NPV. The math is cleaner even if the presentation is less intuitive for stakeholders. The accounting rate of return is the weakest common method. It uses accounting income instead of cash flows, ignores the time value of money, and is sensitive to depreciation methods. Some companies still use it because it is familiar to managers who came up through accounting. It should not be a deciding factor, but it is sometimes the one that gets the most airtime in meetings.
A Practical Process That Actually Works
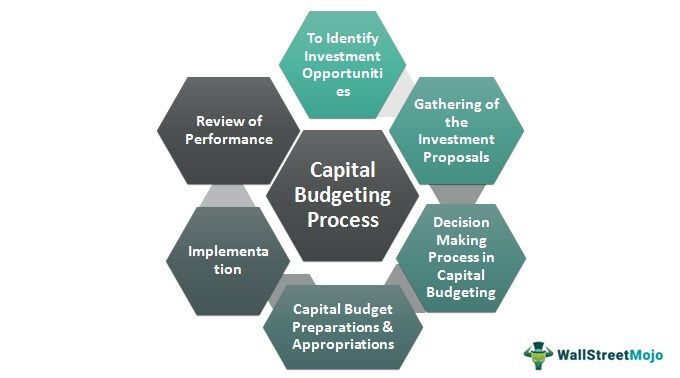
Here is how I structured it at my last organization. Project sponsors submitted a one-page brief with their cash flow assumptions before any detailed modeling happened. This forced them to confront their own optimism bias early. Then our finance team built the model, ran NPV, IRR, payback, and sensitivity analysis, and flagged any projects where the base case relied on assumptions that did not match historical performance. Those projects went to a review committee with a request for revised forecasts. About a third of proposals got revised or withdrawn at that stage. The rest went to final approval with the full analysis attached. The whole process took about two weeks from submission to decision, which is reasonable for projects that could commitment five or ten million dollars. The alternative was the old system where proposals sat in email inboxes for months and got approved or rejected without any systematic comparison between competing projects. One thing that surprised me: the best capital budgeting outcome I saw was not the project with the highest NPV. It was the one with the most flexibility. An option to expand, delay, or abandon is valuable even if the static NPV is slightly lower. Real options analysis is the advanced version of this thinking. Most companies do it informally at best. The ones that do it properly tend to make better long-term investment choices because they are not locking themselves into rigid plans.