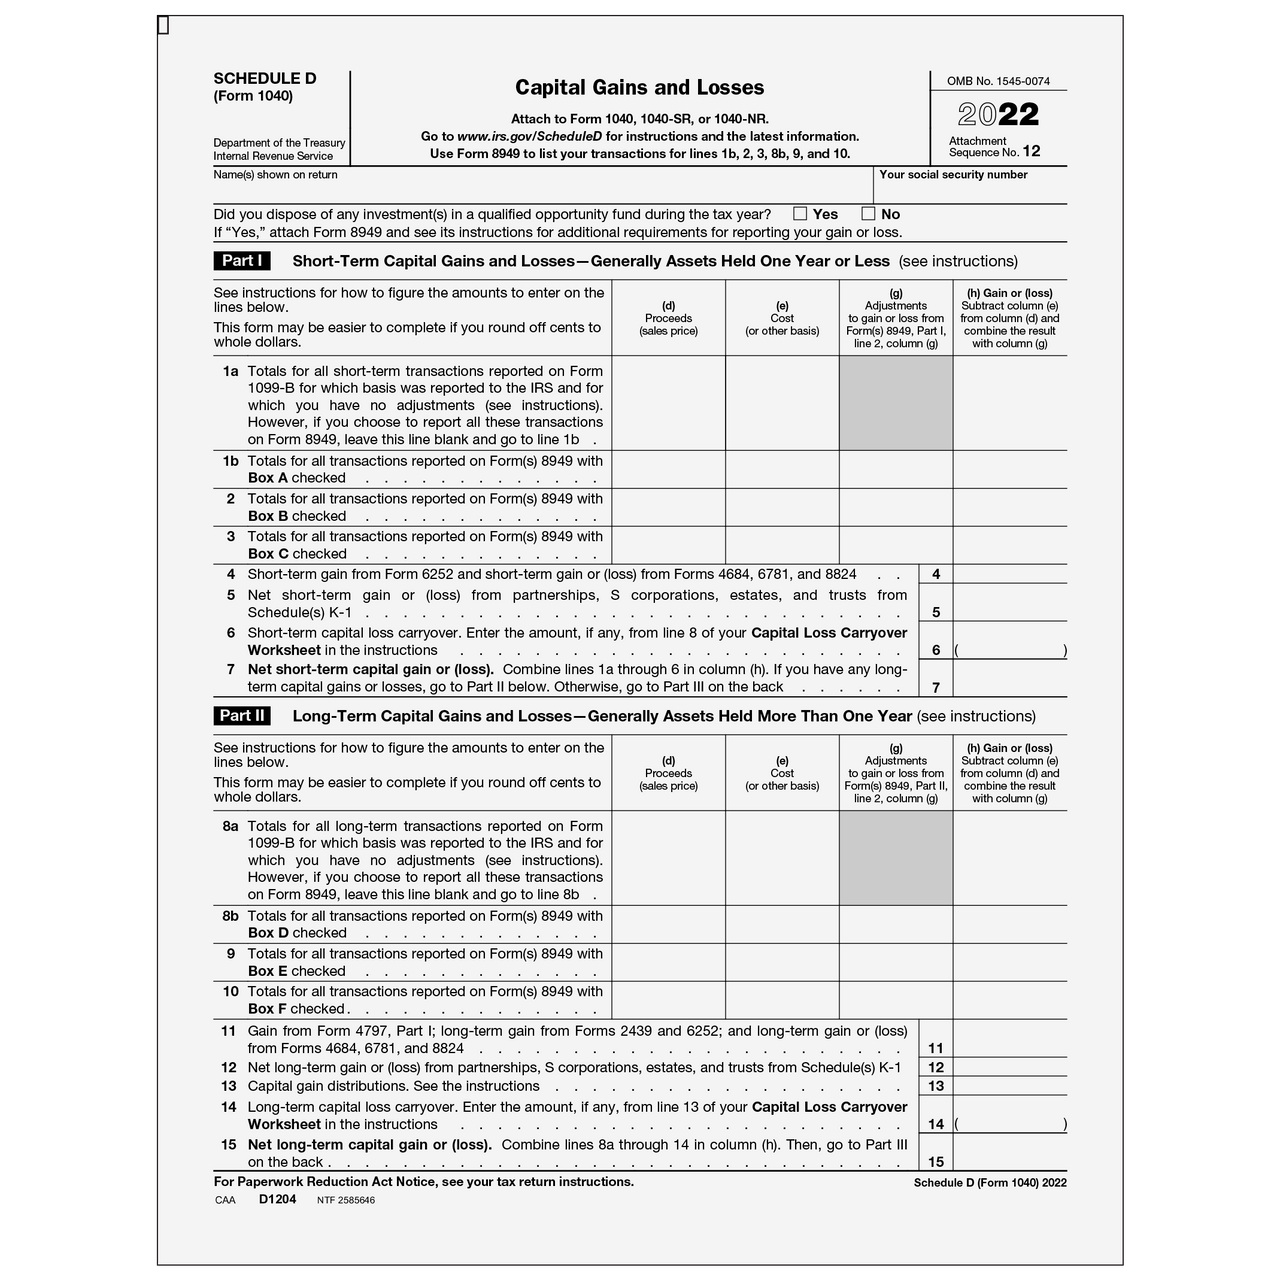
Working Through the Tax Code on Capital Gains
Most people try to track their gains and losses in a spreadsheet and then panic when the IRS Form 8949 doesn't match what they typed. I went through this three years ago with a client who had roughly 140 transactions across four different brokerages — stocks, ETFs, and a handful of municipal bonds that turned out not to be as tax-free as she'd assumed. She'd been marking everything as long-term because that's what her quarterly statements said. The problem was cost basis reporting methods. Her brokerage used FIFO for some lots and average cost for others, and she had no documentation to prove which method applied to which purchase. That mess took about six hours to untangle. The Capital Gains And Losses Worksheet is supposed to prevent exactly this kind of situation, but it only works if you actually fill it out transaction by transaction instead of relying on summary numbers from your annual statement.Using the Capital Gains And Losses Worksheet Correctly
The worksheet you'll find inside IRS instructions is separate from the actual form. It's a planning tool meant to help you organize data before you commit anything to paper. Start by pulling every trade confirmation, brokerage statement, and 1099-B from every account you held during the tax year. Don't skip accounts just because they showed a loss or no gain at all. Missing a single wash sale triggers a chain reaction that makes the rest of the worksheet inaccurate. Section one is where most people get careless. List each transaction individually with the date acquired, date sold, proceeds, and cost basis. The date acquired matters more than you'd think because it determines short-term versus long-term classification, and the IRS treats those categories differently on Schedule D. A share bought on January 3rd and sold on June 30th is short-term even though it only feels like a few months. The worksheet asks for two separate columns for short-term and long-term, so getting this wrong means your final numbers are wrong regardless of how clean your rest of the work looks. For cost basis, use the actual amount you paid including commissions and fees. Brokerage platforms sometimes report adjusted cost basis on your 1099-B, but that adjustment can include reclassed amounts or washed-out transactions you haven't caught yet. Cross-reference against your original purchase confirmations. It takes longer upfront but saves you from amending your return later.
The worksheet then asks you to net your short-term gains and losses together, and separately net your long-term figures. After that, you apply the offset rules: short-term losses first offset short-term gains, then any remaining loss offsets long-term gains up to the limit. Short-term losses carry forward. Long-term losses carry forward. If you have a net loss across both categories, you can deduct up to three thousand dollars against ordinary income on your Form 1040. Anything beyond that carries forward to the next tax year. I ran into a specific edge-case last year that the standard worksheet instructions don't really address clearly. A taxpayer sold stock that had been inherited, and the step-up in basis applied, but the estate had taken several small distributions before the shares were distributed to her. Those distributions reduced the basis without changing the holding period, and the 1099-B only showed the gross proceeds and a flat basis figure that was already incorrect. The workaround was to pull the estate's final accounting documents, subtract the distributions from the stepped-up basis, and recalculate the gain before entering anything on the worksheet. Without that, the reported gain was overstated by nearly twelve thousand dollars, which pushed her into a higher marginal bracket for that year alone. Another thing nobody mentions about the worksheet is the wash sale rule interaction. If you sold a security at a loss and bought a substantially identical security thirty days before or after the sale, the loss is disallowed and must be added to the cost basis of the new shares. The worksheet has a box for wash sales, but it does not automatically recalculate your basis for the replacement position. I've seen people fill in the disallowed loss and then also use the original lower basis on their next purchase, effectively double-counting the benefit. That error shows up on audit and requires an amended return, which is a bureaucratic process that eats about forty-five minutes of your time minimum.
The main limitation of the Capital Gains And Losses Worksheet is that it assumes you already have accurate source data. It is not a verification tool. It won't catch wrong cost basis, missing transactions, or misclassified holding periods. The worksheet is purely a calculation aid. If you need the data itself to be verified, you have to do that outside the worksheet, usually by downloading transaction histories directly from each brokerage's website rather than relying on year-end summaries. Year-end summaries aggregate data and often drop details you need for accurate filing. For most people with fewer than twenty transactions, the worksheet takes about twenty minutes if your brokerages provided correct 1099-B forms. For complicated situations involving inherited assets, wash sales, or multiple cost basis methods across accounts, budget closer to two hours. There is no shortcut around the data gathering. The worksheet itself is straightforward arithmetic. The hard part is making sure the numbers you plug in are right. If your situation involves significant capital losses exceeding your gains, or if you're dealing with partnerships, S-corps, or other pass-through entities that issue K-1s with capital gain distributions, the worksheet alone isn't enough. You should consult a tax professional who understands those structures. The worksheet was designed for individual investors with straightforward stock and bond transactions, not for complex pass-through situations where the gain allocation rules differ from what the form assumes.
Get the Full Details