Getting Through a Capital Gains Tax Worksheet Without Losing Your Mind
Most people think capital gains tax is just profit minus basis, then apply a rate. That's the headline version. The actual worksheet is where things get tedious because it forces you to sort holdings by holding period, account type, and gain category, then track losses that offset gains in specific orders. If you've ever tried to fill one out by hand for anything beyond a single stock sale, you know it eats up an evening and still leaves room for errors. Start by pulling your cost basis statements from every brokerage, retirement, and 529 account. Most platforms let you export CSV files that include purchase date, quantity, purchase price, fees, and adjustments. Don't rely on the summary pages—they often roll everything into one line and hide the difference between short-term and long-term lots. Once you have the data, organize it into two buckets: assets held one year or less, and assets held more than one year. Within each bucket, separate qualified dividends, collectible gains, unrecaptured Section 1250 gain, and regular capital gains. A single sale of rental property, for example, generates both a capital gain and unrecaptured Section 1250 gain because of depreciation. If you lump those together, your tax calculation will be wrong.
Here's where most people hit a wall. When you have both short-term and long-term losses, the worksheet requires you to net them against gains in a specific sequence before carrying any excess forward. Short-term losses offset short-term gains first, then long-term gains. Long-term losses do the reverse. Any remaining loss gets limited to $3,000 against ordinary income, and the rest carries forward. I learned this the hard way when I sold a partnership interest in 2019 and had to reconcile a $42,000 long-term loss against a mix of short-term and long-term gains from a totally different portfolio. I initially netted everything together and underreported my income by about $8,000. The fix was to rebuild the worksheet from scratch, separating the partnership gain/loss from the brokerage activity, then applying the netting order explicitly on paper before entering anything into tax software. After you've categorized everything, run the netting process. If your net long-term gain exceeds your net short-term gain, you apply the preferential rates. For 2025, that's 0 percent if your taxable income falls below $95,750 for single filers or $191,500 for married filing jointly, 15 percent between those thresholds and $501,600 single or $533,600 joint, and 20 percent above that. You also need to check whether the 3.8 percent net investment income tax applies if your modified adjusted gross income exceeds $200,000 single or $250,000 joint. The worksheet isn't just a calculator. It's also a record of your lot selection method. If you used specific identification instead of FIFO, the IRS expects you to have documented which shares you sold and at what cost. Average cost is fine for mutual funds in IRA accounts but doesn't carry over the same way for taxable accounts. I've seen people use average cost on a taxable stock position and then wonder why their basis looked inflated on the 1099-B compared to what they thought they paid.
One thing the worksheet won't do for you is handle wash sales across accounts. If you sold Stock A at a loss in your brokerage account and bought the same stock back in your IRA within 30 days, that wash sale disallows the loss. The worksheet has no built-in mechanism to catch this. You have to flag it manually. I keep a separate spreadsheet tracking all my positions with purchase dates and sale dates so I can cross-reference against repurchases within the 61-day window. It takes about ten minutes each quarter and has saved me from multiple amended returns. Another edge case that trips people up involves worthless securities. If a stock goes to zero, you treat it as sold on the last day of the year. The worksheet needs the fair market value recorded as zero and the basis written off completely. If you wait until the next year and then receive a corrected 1099-B, your worksheet will already be wrong. I had a client who held shares of a biotech company that quietly dissolved in November but didn't get the formal write-down notice until March. He assumed the gain would resolve itself. It didn't. We had to amend his return to reflect the worthlessness and rework the worksheet with the correct holding period ending December 31st. The worksheet also doesn't automatically account for state-level differences. Some states conform to federal capital gains treatment. Others tax capital gains as ordinary income, and a few don't tax them at all. California, for instance, treats capital gains as ordinary income for state purposes, which means the preferential rates disappear at the state level even if they apply federally. You'll need a second worksheet for state purposes if you're in one of those states.
Get the Full Details
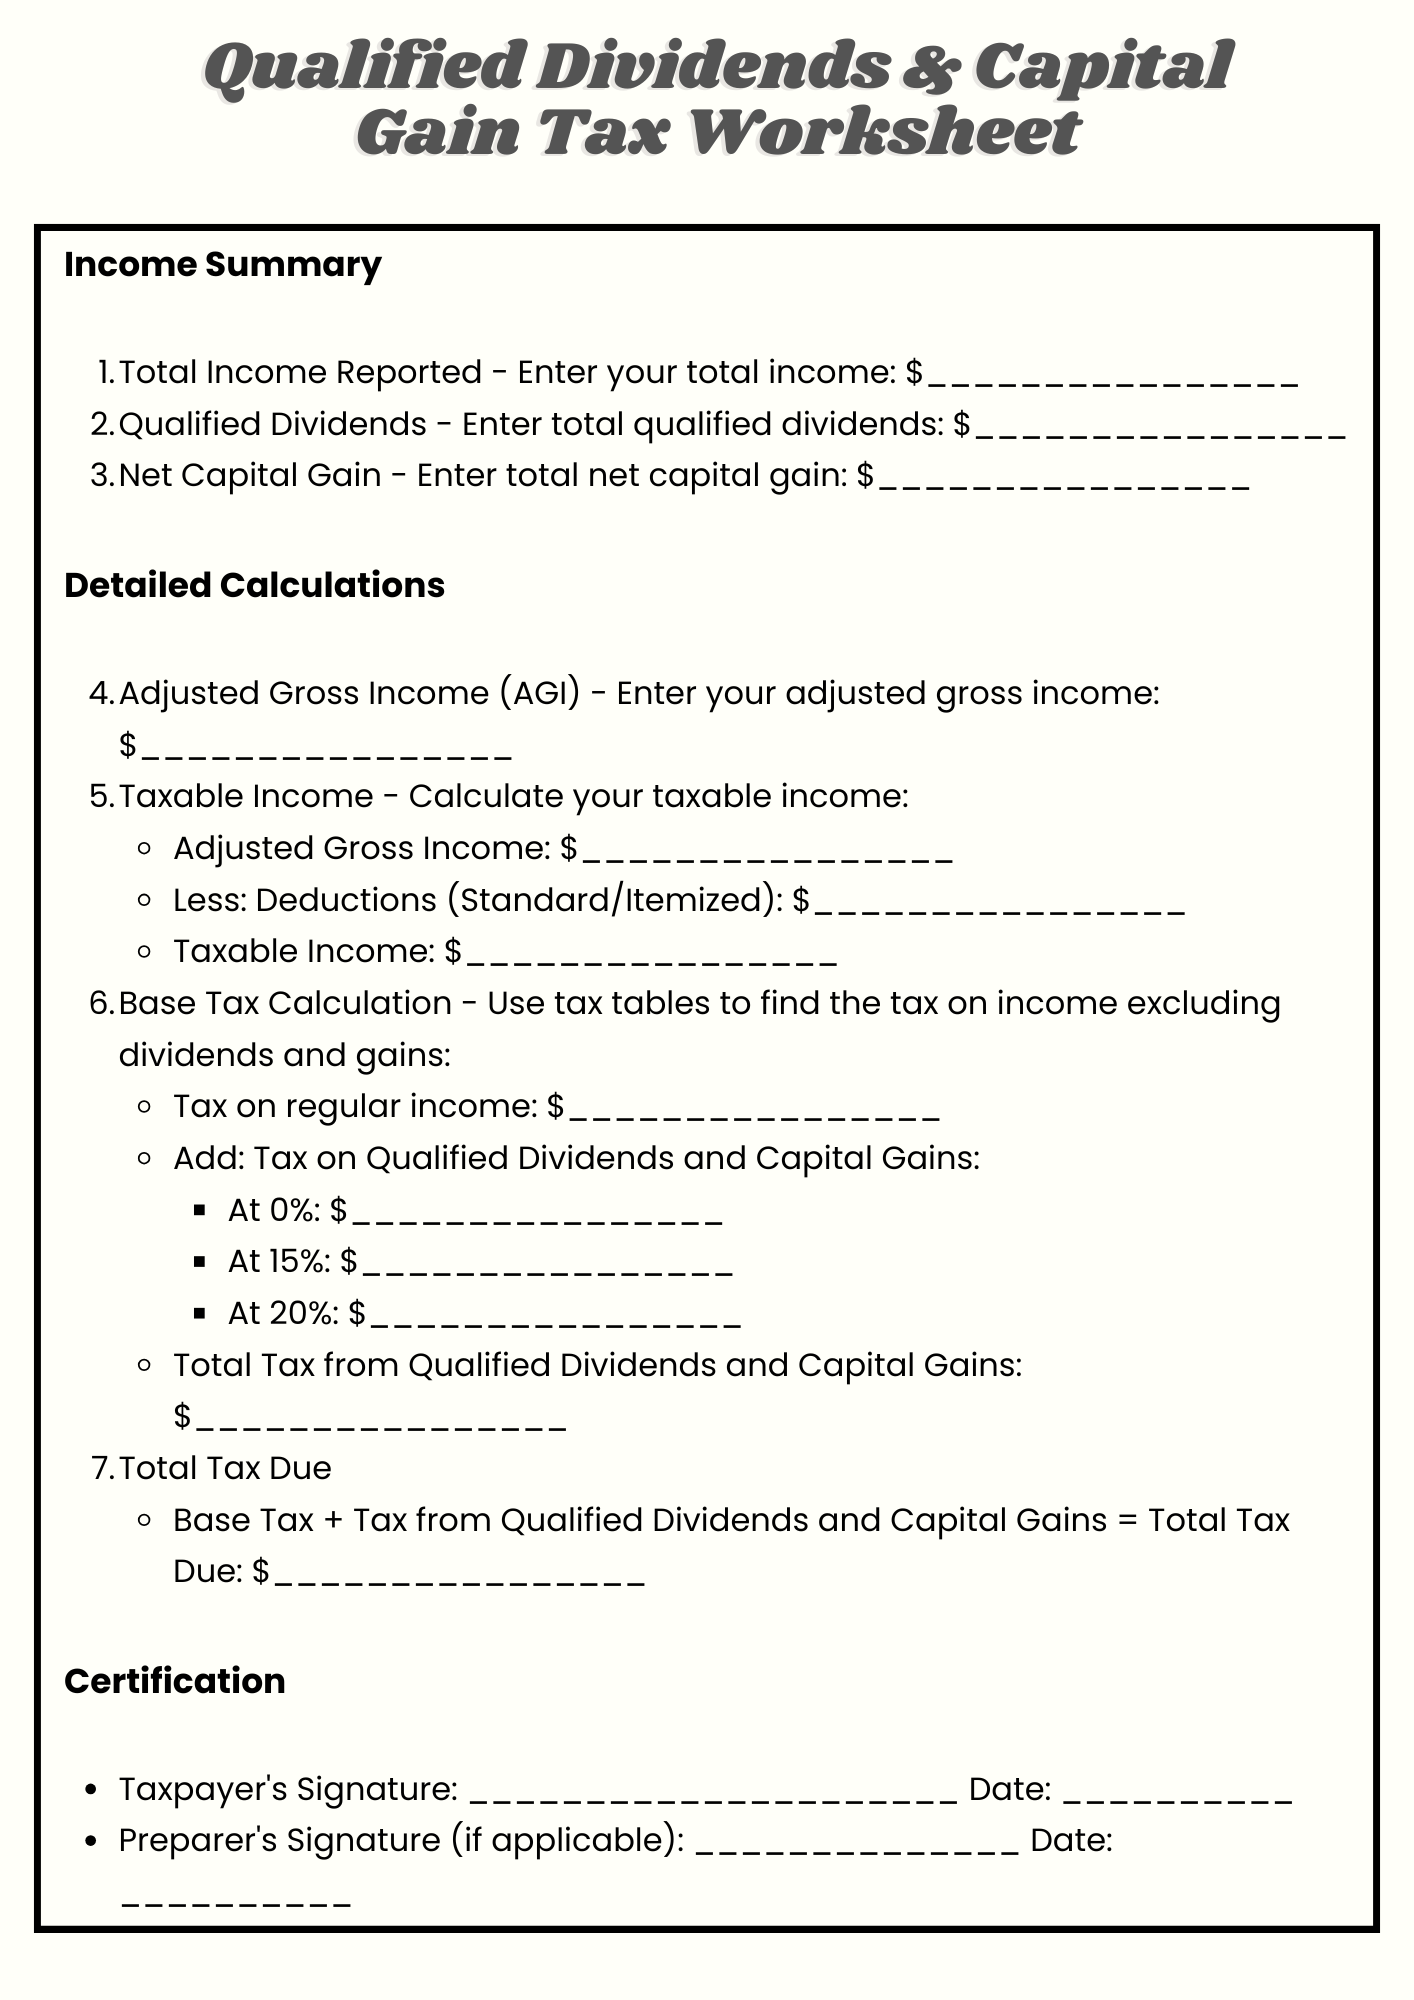
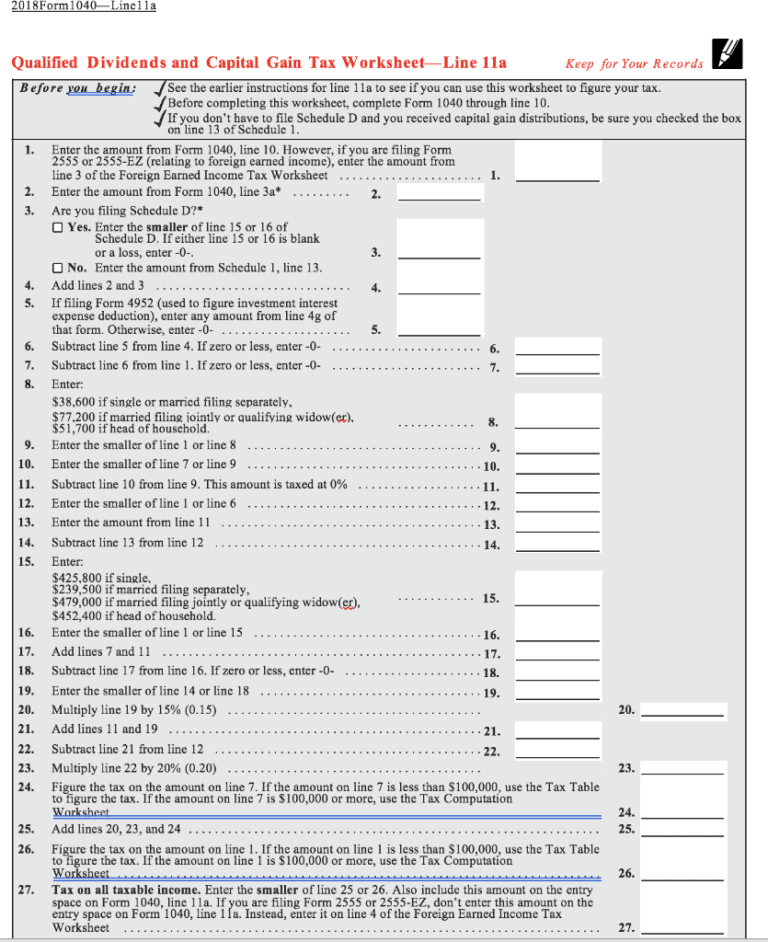
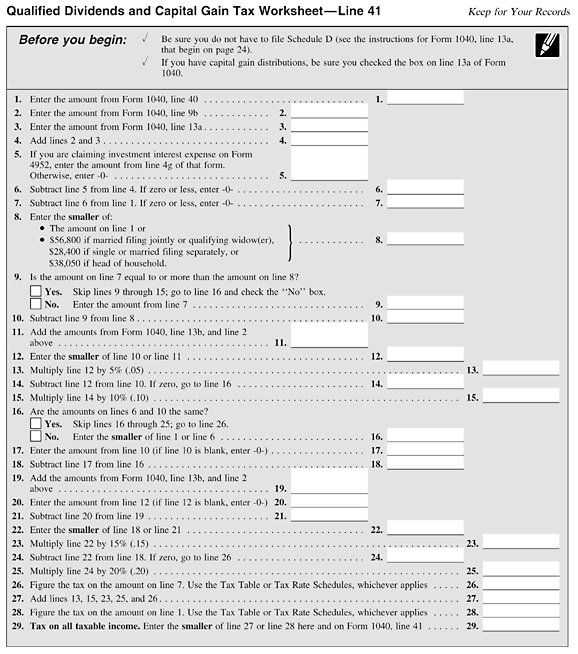
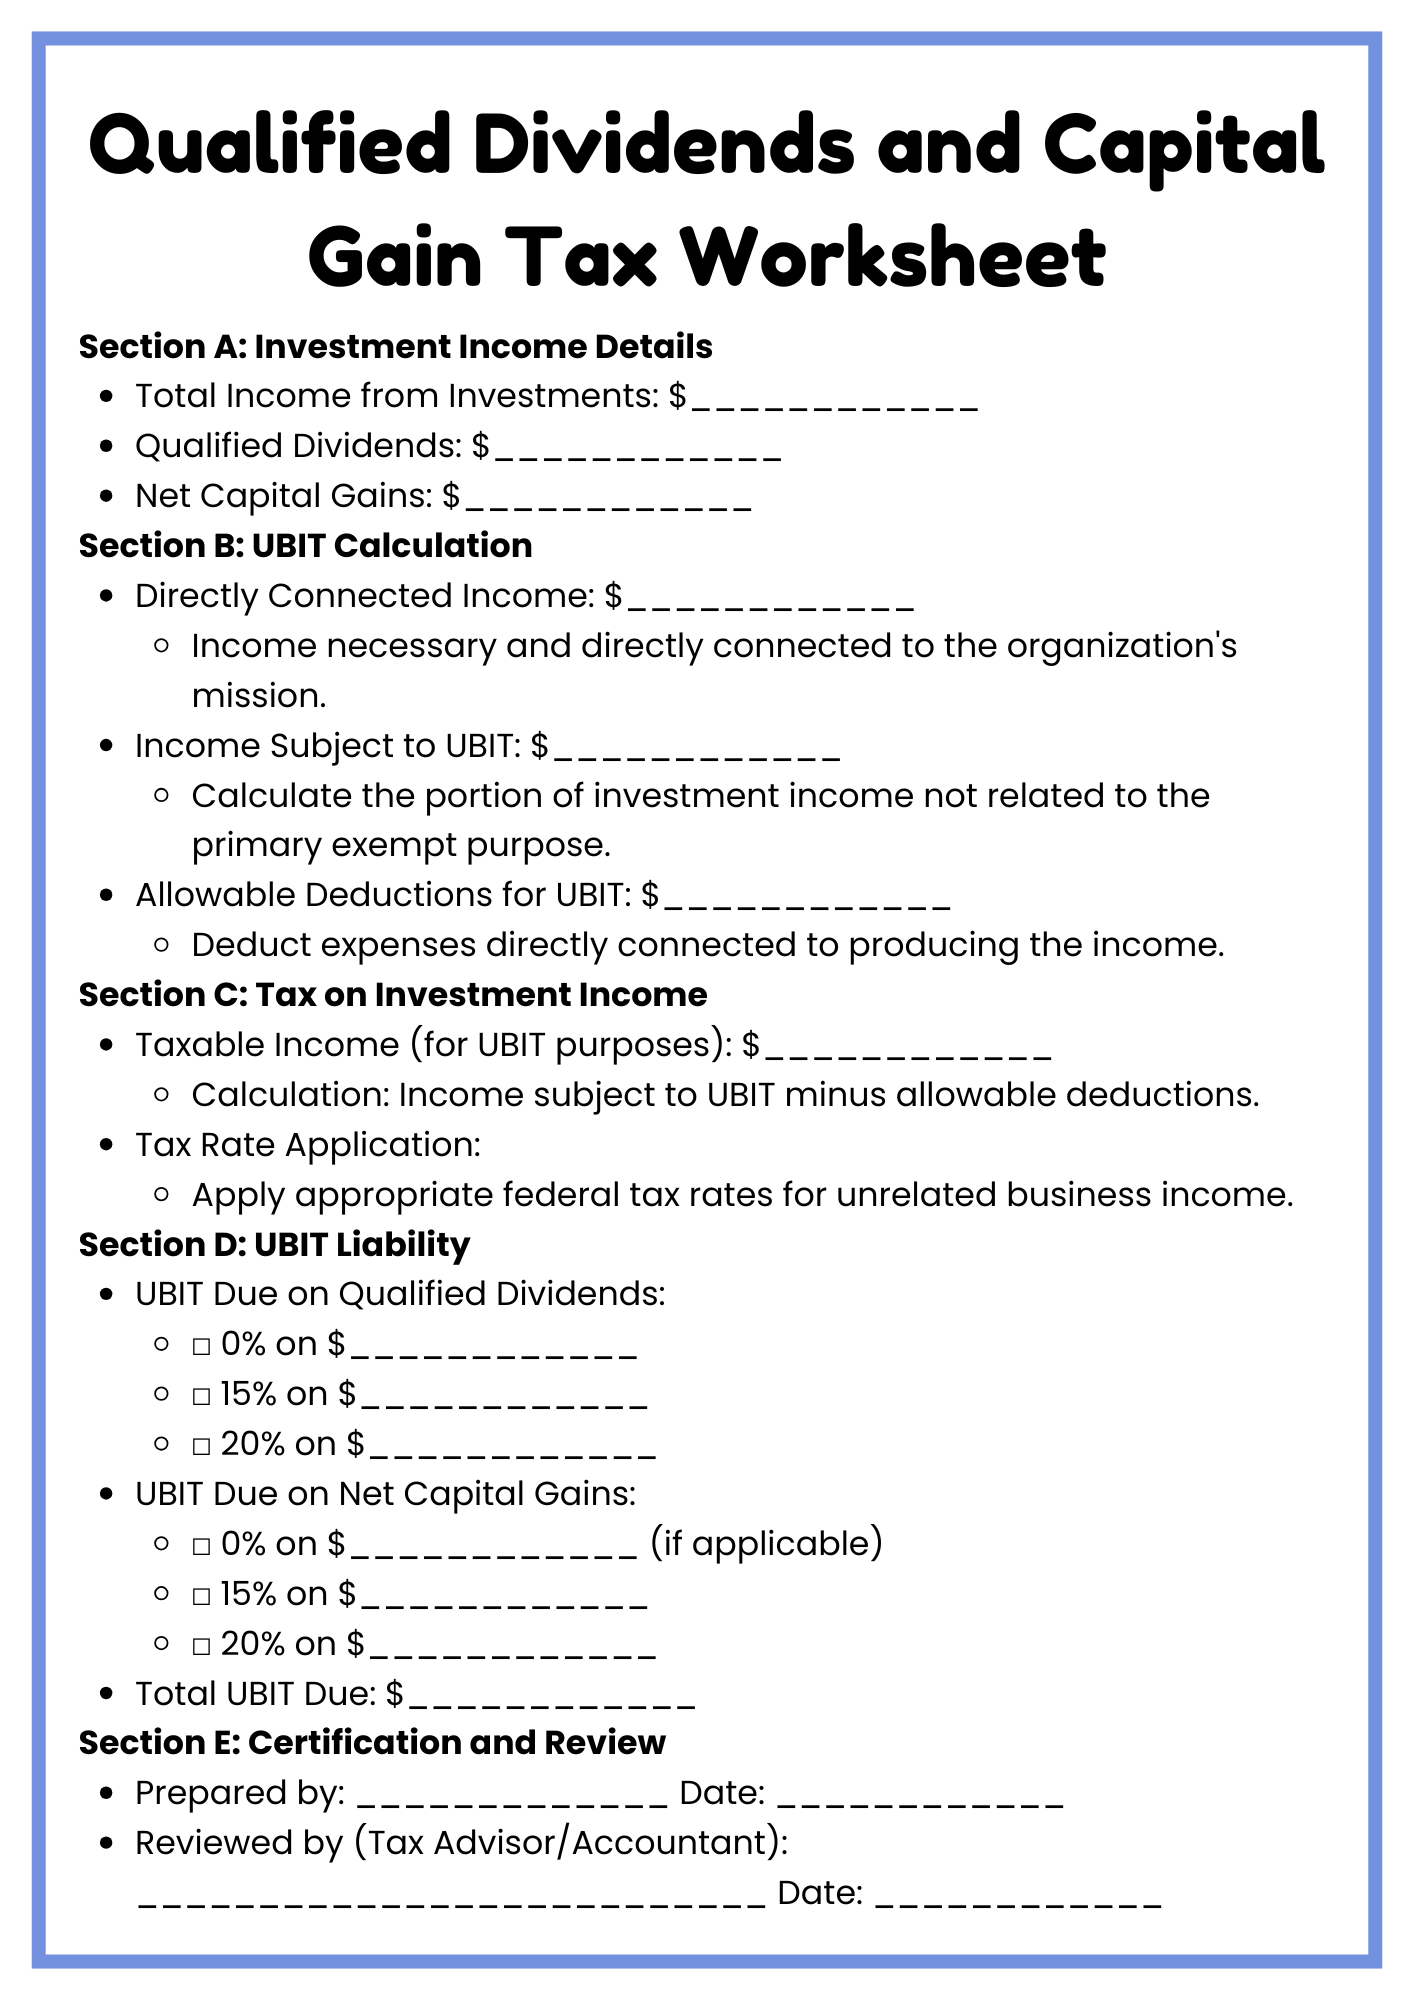
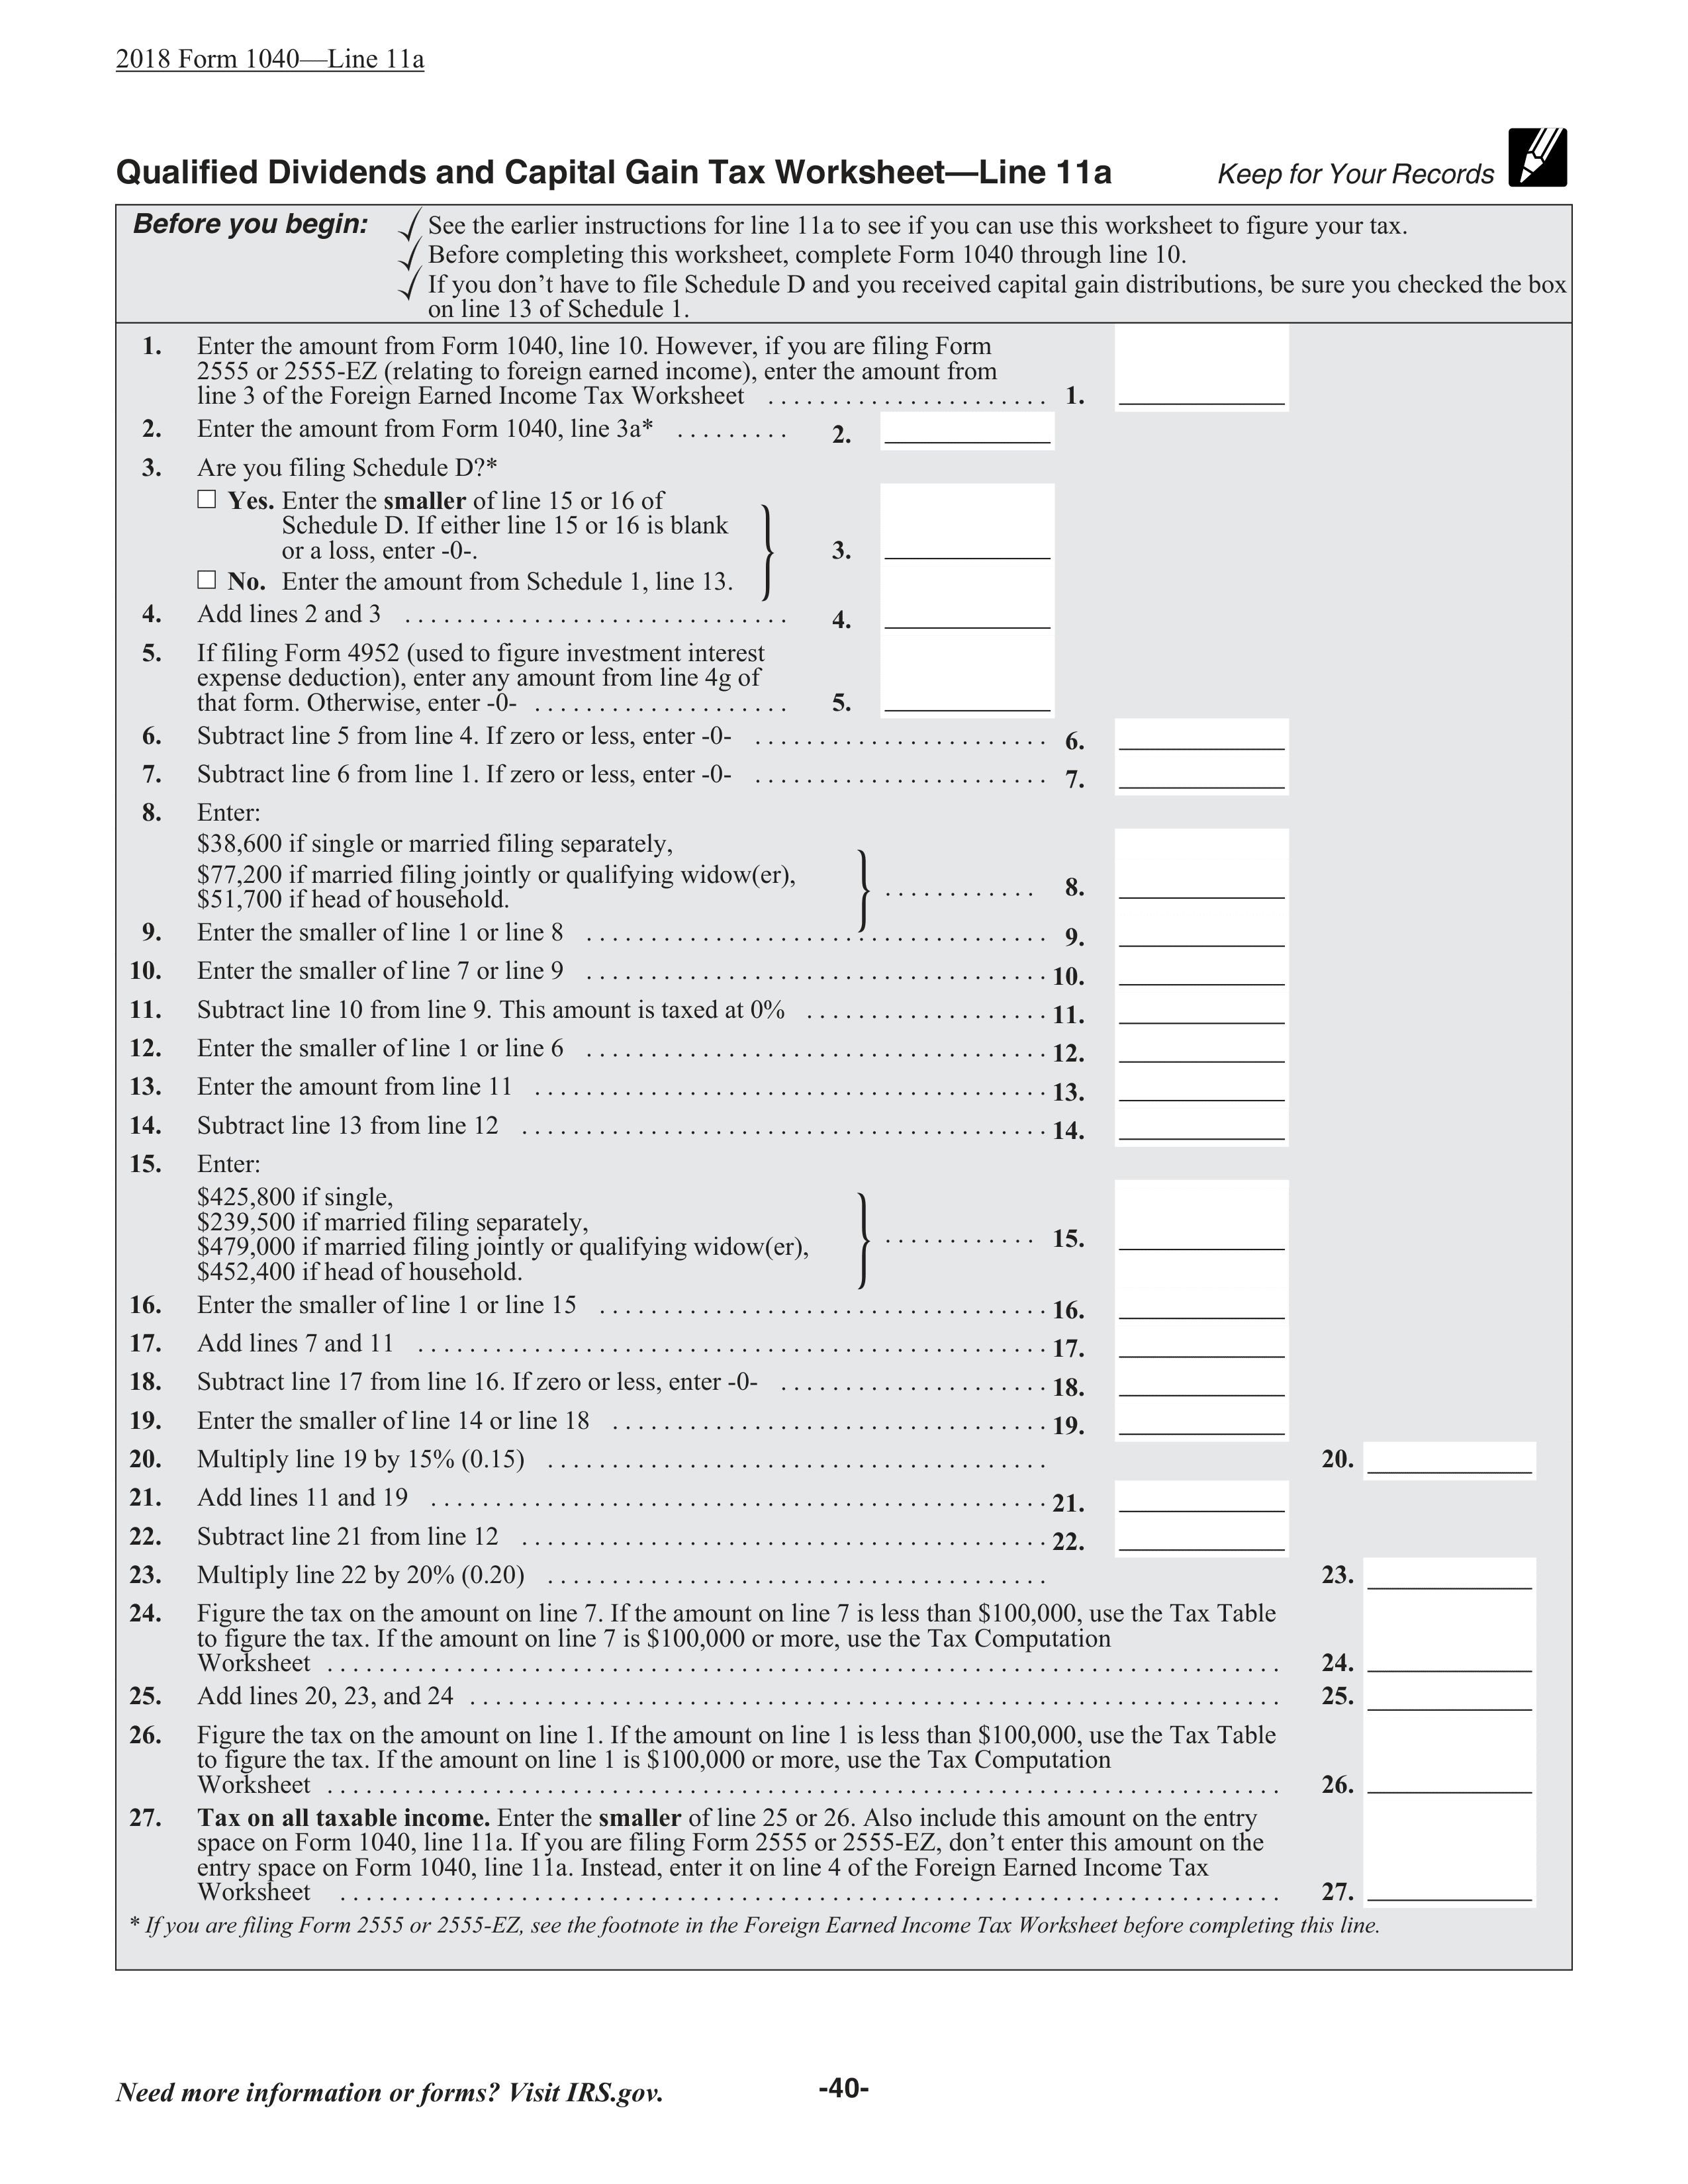
If you're dealing with inheritance property, the step-up in basis changes the calculation entirely. The worksheet assumes you have a cost basis you entered yourself. Inherited assets get a basis equal to the fair market value at the date of death or the alternate valuation date. Make sure your cost basis statement reflects the stepped-up amount, not what the deceased originally paid. I've seen this mistake cost people thousands because they used the decedent's historical basis instead of the date-of-death value, which inflated their gain and pushed them into a higher bracket. There's no free downloadable Capital Gains Tax Worksheet that the government publishes as a standalone form for individual investors. Form 8949 and Schedule D serve the same function and are available directly from IRS.gov. If you're looking for a printable worksheet, those two forms are your starting point. Many third-party sites offer templates, but they often pre-fill sections incorrectly or use outdated rate brackets. Stick to the IRS versions and fill them in from your own data. That usually takes me about twenty minutes once the lot tracking is set up properly. The real bottleneck isn't the math. It's the data collection. If you have holdings across three or more platforms, the export format will vary, and some brokers still send PDFs instead of CSVs. PDF extraction adds time and introduces transcription errors. I recommend using a tool like TurboTax or H&R Block if your situation is straightforward, but for anything involving multiple account types, pass-through entities, or complex lot tracking, a spreadsheet with explicit columns for asset, symbol, shares, cost, date acquired, date sold, proceeds, and gain category will catch issues before they reach the worksheet stage.
A final practical note: keep your worksheet and supporting documentation for at least three years from the filing date, or two years from the date you paid the tax, whichever is later. The IRS can challenge your basis allocation, especially if you used specific identification without clear records. A messy worksheet from four years ago is not something you want to reconstruct on demand.