How the Capital Loss Carryover Worksheet Actually Works
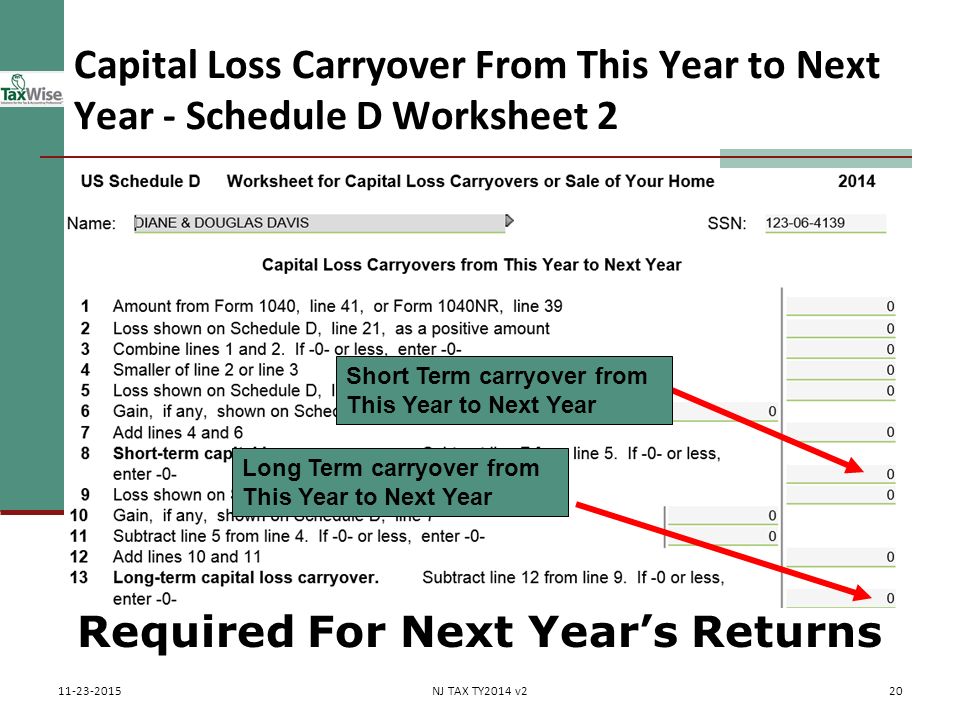
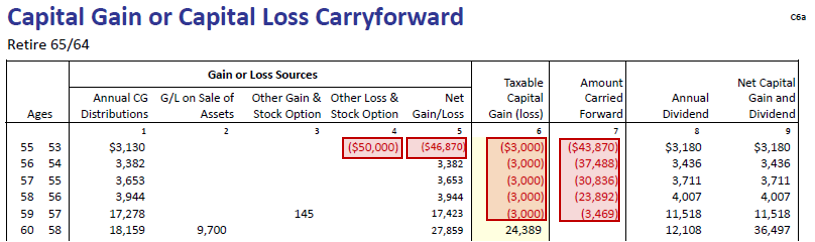
The capital loss carryover worksheet isn't some mystical IRS document. It's Schedule D, lines 8 through 11, and it shows up on your tax return when you've sold assets for more losses than you can fully offset against gains and the $3,000 ordinary income allowance. Most people don't realize it until they're staring at a 1099-B from three different brokerages and the numbers don't line up. I set up a sample to make this concrete. Let's say you have $12,000 in short-term capital losses from selling tech stocks, $4,500 in long-term losses from an investment property, and $6,000 in short-term gains from selling a rental vehicle. You combine the short-term net positions first: $6,000 gain minus $12,000 loss gives you a $6,000 net short-term loss. Then you layer on the long-term loss: $6,000 plus $4,500 equals $10,500 total net capital loss for the year. Here's where it gets mechanically interesting. The IRS lets you deduct up to $3,000 of that total net capital loss against your ordinary income -- wages, interest, whatever. That leaves $7,500 to carry forward to next year. This is the core mechanic. Everything else is just bookkeeping to make sure you track the character of the loss, because short-term losses stay short-term and long-term losses stay long-term in the carryover bucket.
Capital Loss Carryover Worksheet Example
Working through the actual line items on the worksheet: Line 8 is where you report the total net capital loss from Schedule D, line 10. That's your $10,500. Line 9 is the $3,000 limitation (or $1,500 if you're married filing separately). Line 10 is simply line 8 minus line 9, which gives you the carryover amount -- $7,500 in this case. Line 11 tells you how to report it on next year's return: $6,000 as short-term and $4,500 as long-term. You can pull up the official worksheet on IRS.gov as part of the Schedule D instructions for the current tax year, or use any major tax preparation software which generates it automatically behind the scenes. I stopped filling it by hand years ago. FreeTaxUSA or TurboTax both produce it without requiring you to do the arithmetic manually.
I hit a specific edge case last year that wasn't obvious from the instructions. I had washed-sale violations mixed with a net operating loss situation because I'd sold crypto at a loss, bought back into the same token within the wash-sale window, and then the disallowed loss pushed my total deductions in a way that interacted strangely with the $3,000 cap. The work-around was to separate the wash-sale disallowed losses out on a sub-schedule before putting anything onto the main worksheet, because those losses don't disappear -- they just get tacked onto the cost basis of the replacement shares and deferred until that replacement position is eventually sold. If you don't track that adjustment separately, you'll undercount your carryover by exactly the wash-sale amount and the IRS will flag it during review. One thing nobody tells you about carryovers: they retain their original character indefinitely. Short-term stays short-term. Long-term stays long-term. That matters because if next year you have a large short-term gain but only long-term carryover losses sitting there, you can't use the short-term gains to absorb the long-term losses first. The ordering rules on Schedule D force you to net like with like before you ever touch the $3,000 ordinary income deduction. This trips up a lot of people who assume the carryover is just a generic pool of loss dollars. Another nuance: if you have both short-term and long-term carryovers and next year produces gains in both categories, you apply the carryover losses in a specific order. Short-term losses offset short-term gains first. Long-term losses offset long-term gains first. Only after those nets are calculated do you combine them and apply the $3,000 rule against ordinary income. Get the ordering wrong and your taxable gain will be higher than it should be, sometimes by enough to push you into a different bracket.
Get the Full Details
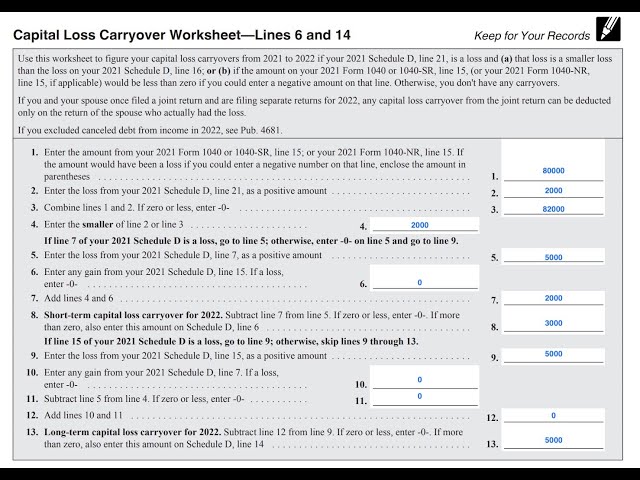
The honest limitations: the carryover system only helps if you actually have future gains or future ordinary income to absorb it. If you're in a years-long stretch of no investment activity -- say you retired and aren't selling anything -- those carryover losses just sit there. They don't expire, which sounds generous, but they also don't earn interest or generate any benefit while idle. You could end up with thousands in loss carryovers that never get used if your portfolio goes dormant. There's no statute of limitations on losing them, but there is also no mechanism to monetize them separately. Also, the worksheet itself doesn't account for state-level quirks. Some states don't conform to the federal capital loss rules and have their own caps or carryforward periods. If you live in a state like California with different provisions, your state return calculation will diverge from the federal worksheet. You'll need a separate state schedule and the federal carryover will feed into it, but not always in a straightforward way. If you're dealing with a straightforward case -- a few 1099-Bs, a Property sale, maybe some crypto -- the software path is fine and takes about five minutes. The manual path is about twenty minutes if you're comfortable with Schedule D. Beyond that, or if you have wash sales, depreciation recapture, or state complications, a tax professional who actually knows capital loss rules rather than just running numbers will save you from having to refile an amended return. I've seen enough clients get burned by that.