Why This Template Is Actually Useful
Most capital assessment tools you find online are either oversimplified spreadsheets or overengineered financial models that take two weeks to build. A proper Capital Needs Assessment Template sits somewhere in between. It forces you to separate working capital from long-term capital expenditures, which is the single most common mistake I see. People treat all capital needs as one bucket and then wonder why they run short three months into the fiscal year. I built my current template after going through a rough period where we underestimated our working capital gap by nearly forty percent. The root cause was that inventory builds for seasonal demand required funding six weeks before revenue came back in, and nobody had planned for that bridge. The template now captures that timing difference explicitly.
What the Capital Needs Assessment Template Actually Does
At its core, the template calculates the gap between when you need money and when you expect to have it. It is not a forecasting tool for revenue. It is a gap analysis tool. You input your known obligations, your expected funding sources, and the timeline for both. The output is a cash shortfall figure with a date attached to it. The structure I use has four sections. The first covers current liabilities due within the next twelve months. This includes payroll, rent, loan payments, supplier invoices, and tax obligations. The second section is capital expenditures scheduled over a three to five year horizon. The third section lists expected funding sources like retained earnings, lines of credit, and investor capital. The fourth section calculates the gap and flags months where the gap exceeds your threshold. I keep the template in a simple Google Sheets file because it needs to be editable without special software. The formulas are basic. Subtract expected funding from obligations by month and highlight any negative result in red. That is the entire logic. The value is in forcing the categorization, not in sophisticated calculations.
One thing that caught me off guard when I first used this properly was that working capital needs often grow faster than revenue in expanding companies. When you sign larger contracts, you need more inventory and you extend more credit to customers, but your payables do not automatically adjust to match. I learned this the hard way when a new client pushed our accounts receivable from thirty days to sixty days without renegotiating our supplier terms. The gap appeared in month two and we had no buffer. Another counterintuitive point that people miss is that the discount rate you use for evaluating whether to fund the gap with debt versus equity should not be your cost of debt alone. If you are considering equity financing, you need to factor in what that equity could earn elsewhere. A rule I follow is using a blended hurdle rate of around twelve to fifteen percent when comparing funding options, regardless of what the bank is offering. Debt looks cheaper on paper but equity has a real cost that gets ignored. Here is the honest downside of this approach. The template does not account for volatility in revenue or unexpected expenses very well. It works best for stable businesses with predictable cash flows. If your revenue swings twenty percent quarter to quarter, you need to run the assessment under at least three scenarios. I usually add a worst-case column that assumes revenue drops fifteen percent and costs stay flat. The gap in that scenario tells you what your real minimum capital position needs to be.
Get the Full Details
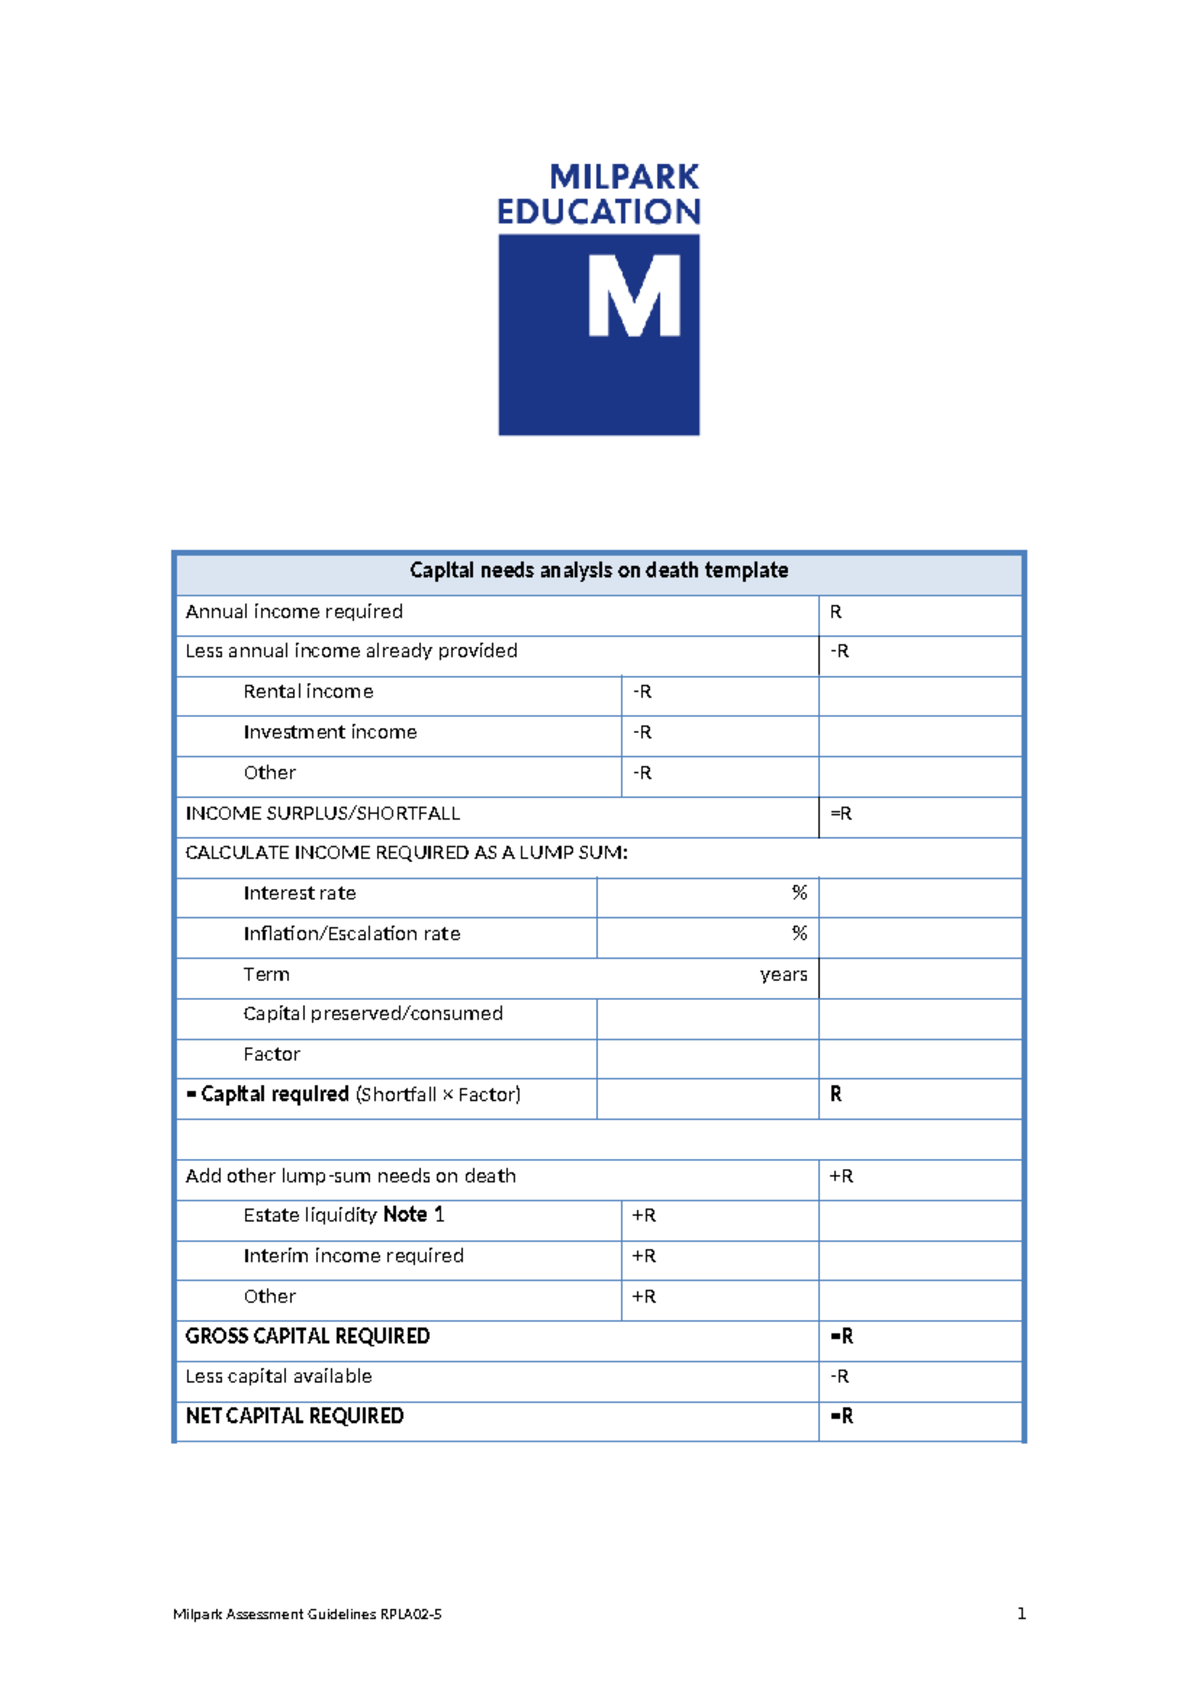
I also found that contingency buffers of ten percent are almost never enough. I bumped mine to twenty percent after a major supplier went under during a project and we had to pay upfront to a replacement vendor, which blew past our initial estimate by eighteen percent. That one incident changed how I build every assessment going forward. One practical tip that saves time is to link your existing accounting software to pull the liability data automatically. Most small business accounting tools can export a trial balance or accounts payable aging report in CSV format. Importing that into the template cuts the setup time from about two hours to roughly twenty minutes. The manual entry part is usually just the three to five year capital expenditure schedule, and that does not change frequently enough to warrant automation.
Where to Find a Working Version
I do not maintain a public download link for the template itself since it is customized to my industry assumptions. However, you can build one quickly using the structure described above. Start with a blank spreadsheet. Create month-by-month columns for the next eighteen months. Set up four tabs: Current Obligations, Long-term Capital, Expected Funding, and Gap Analysis. Pull your data from your accounting system into the first tab and work through the rest from there. It takes longer to explain than it does to build.