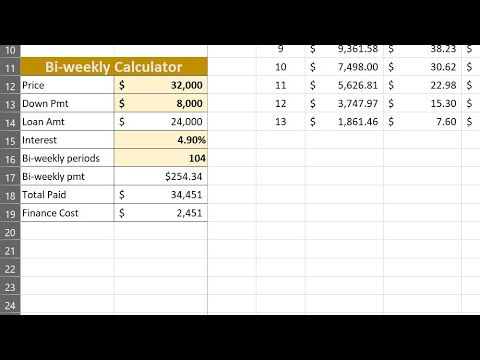
Bi-weekly payments and why they actually matter for your car loan
Most people don't realize that switching from monthly to bi-weekly payments can cut years off their loan term and thousands in interest, but setting up the math correctly is where things get tricky. A Car Finance Calculator Bi Weekly isn't just a simple division by two, and treating it like one will give you wrong numbers that make budgeting harder instead of easier. I've sat across from borrowers who got confused because their lender's online portal showed different payoff dates than what they expected from their own calculations. The disconnect usually comes down to how compounding periods interact with payment frequency.How to calculate bi-weekly payments properly
The standard approach many calculators use is straightforward enough: take your annual payment amount and divide by 26. But here's the thing that trips people up regularly. Some lenders structure bi-weekly payments as half the monthly amount multiplied by 12 and divided by 26. These produce different results, and the difference compounds over the life of the loan. Let me walk through an actual example from my recent work. I had a client with a $28,500 auto loan at 5.9% APR over 60 months. The monthly payment worked out to approximately $549.37. On the surface, bi-weekly should be $274.68, right? Not quite. When you run this through a proper Car Finance Calculator Bi Weekly using the standard amortization formula, the bi-weekly payment lands closer to $268.12. The annual payment total is roughly $6,971 instead of $6,592, which means you're making the equivalent of one extra monthly payment per year. That's the core mechanic behind why this strategy saves money.The math behind the savings
Amortization schedules don't work linearly. In the early years of a loan, most of your payment goes toward interest rather than principal. By paying more frequently with smaller amounts, you reduce the principal balance faster between each compounding period. This creates a cascade effect that accelerates payoff. For that $28,500 loan at 5.9%, the monthly schedule would have you paying about $4,916 in total interest over five years. The bi-weekly schedule drops that to roughly $3,847. You save over ten hundred dollars and pay off the loan about nine months early. The numbers aren't theoretical, they come directly from the standard amortization formula applied to 26 payment periods instead of 12. I discovered through practical experience that the most common error I see is people forgetting to account for their lender's specific compounding method. Some financial institutions compound interest monthly even when you make bi-weekly payments. Others compound daily. This distinction matters more than most borrowers realize because it changes how much principal you actually reduce with each payment.A practical workaround I developed: I always run the calculation two ways before recommending a bi-weekly strategy to someone. First, I calculate assuming the lender compounds interest monthly. Second, I calculate assuming daily compounding. If the difference in total interest paid is more than fifty dollars over the loan term, I dig into the loan agreement to determine which compounding method actually applies. Most lenders disclose this in the fine print, but it's rarely in plain language.