Why people still do this math by hand
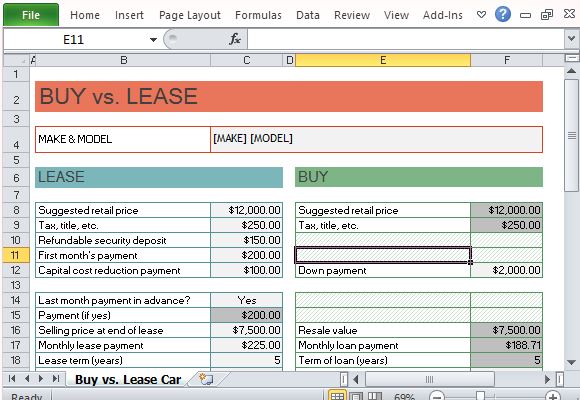
I've watched dozens of customers sit across from me at a dealership office, laptop open, trying to build a custom spreadsheet to figure out whether they should lease or buy a vehicle. They'll spend forty-five minutes wrestling with residual values, money factors, and tax implications before giving up and asking me to just tell them what to do. There's no shame in that. The problem is most people don't actually need a spreadsheet. What they need is the right calculator, fed with the right numbers, and someone who knows which inputs actually move the needle. A Car Lease Versus Purchase Calculator is exactly what it sounds like — a tool that takes the key financial variables of a lease deal and a comparable purchase deal and spits out a side-by-side comparison. But here's the thing most online calculators won't tell you: the output is only as good as the numbers you put into it, and most of the fields on a typical calculator page are misleading if you don't know how they map to real dealer quotes. I spent six years working in automotive finance, and the number one mistake I see is people plugging in the MSRP instead of the actual negotiated price. That single error can swing the comparison by three or four thousand dollars depending on the deal structure.
How to set up a Car Lease Versus Purchase Calculator correctly
Let me walk through the process the way I'd actually use it, not the way a marketing page would describe it. First, get your numbers in writing. I don't care if you got a verbal quote over the phone. Get an out-the-door breakdown from the dealer for both the lease and the purchase scenario. You need the capitalized cost, the money factor, the residual value percentage, the lease term in months, any disposition fee, the purchase price, the loan rate, the loan term, and your local sales tax rate. Write them all down before you touch a calculator. I've lost count of the times someone comes back two days later having forgotten whether the money factor was 0.00125 or 0.0025, which changes the lease cost by nearly a hundred dollars a month. Once you have those numbers, input them. Here's where I want to flag something most people miss. The standard approach most calculators use is to compute the total cost of each option over its respective term and then compare them directly. That feels intuitive but it's technically wrong if the lease and purchase terms differ. A thirty-six-month lease versus a sixty-month loan aren't comparable on a simple total-cost basis because you're holding the purchased car for twice as long and you haven't accounted for the residual value at the end of the lease. The proper comparison is the net cost of each option, which means subtracting the expected resale value from the total amount paid. For the lease, that resale value is the residual value built into the contract. For the purchase, it's whatever you think you can sell or trade the car for at the end of your ownership period. I had a customer last year who was comparing a lease on a BMW 3 Series against buying the same car. Her lease had a money factor of 0.00085, which converts to roughly a 2.04 percent interest rate if you multiply by 2,400. The dealer quoted a capitalized cost reduction of zero, meaning she was financing the full amount. She ran her numbers through a generic online calculator and it told her the lease was cheaper by about two hundred dollars a month. She was ready to sign. I looked at the residual value the dealer was using — 58 percent of MSRP at thirty-six months — and asked her to pull the actual Black Book retail value for that same year and mileage. It was 52 percent. The dealer was inflating the residual by six percentage points, which is the single biggest way leases get structured to look better than they actually are. When we corrected for that, the purchase came out cheaper by about eight hundred dollars over three years, even after accounting for the fact that she'd own the car at the end.
That's the kind of adjustment a basic calculator won't make for you. A good Car Lease Versus Purchase Calculator will let you override the residual or let you enter your own estimated resale value, but most of the free ones online don't. You'll need to either find one that does or build a simple comparison yourself using the formula I described.
Get the Full Details
The inputs that matter and the ones that don't
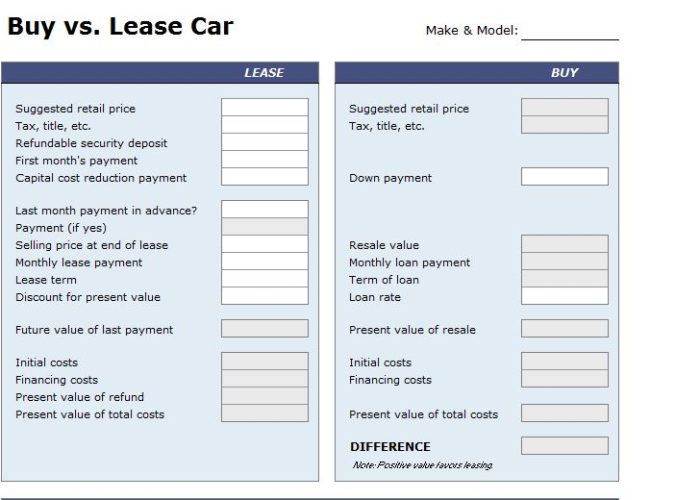
Here's a practical breakdown of what each field actually does and where the traps are. The capitalized cost is your starting point. This is the negotiated price of the vehicle, not the MSRP, not the invoice price, and definitely not the sticker price you see on the window. It includes any add-ons the dealer rolls in, so check carefully. If the dealer adds a $1,200 fabric protection package to your cap cost, you're effectively paying finance charges on that $1,200 for the entire lease term, which for a three-year lease at a 2 percent effective rate works out to roughly twenty-five dollars in wasted money. The money factor is the lease equivalent of an interest rate, but it's expressed in a way that makes it deliberately hard to compare. Multiply it by 2,400 to get an approximate annual percentage rate. A money factor of 0.0015 equals about 3.6 percent. Some leases advertise ridiculously low money factors like 0.00050, which translates to roughly 1.2 percent. Those are real when they're offered, usually as part of a corporate or loyalty program, but they come with strings attached — specific trim levels, limited availability, and often a requirement to lease multiple vehicles. The residual value is where the industry makes its margin. It's the percentage of the car's original value that the leasing company expects to recover when they sell it after the lease ends. Higher residual means lower monthly payments because you're only paying for the depreciation, not the full value. The problem is residuals are set by the leasing company, not by market reality, and they're notoriously optimistic on vehicles with poor long-term value retention. If a lease company thinks your car will hold 60 percent of its value after three years but the actual market value ends up being 50 percent, you've still paid for that gap through your monthly payments. The dealer doesn't care because the residual is baked into the lease from day one and it can't be changed.
Sales tax is another area where people consistently misjudge their costs. In some states you pay tax on the full lease payment every month. In others you only pay tax when you buy the car, which can create a massive apparent advantage for leasing that disappears once you do the math properly. I had a customer in New York who was thrilled that his lease payments were lower than his purchase payments until I pointed out he was paying monthly sales tax on every lease payment while his friend in California was paying sales tax only once on the purchase price. Over three years, the New York lessee ended up paying roughly $900 more in tax than the California buyer, completely erasing whatever advantage the lease structure provided.
When this calculator approach breaks down
Let me be honest about the limitations. A Car Lease Versus Purchase Calculator gives you a numerical answer, but that answer assumes you'll drive the exact mileage specified in the lease, keep the car in the condition the dealer expects, and hold onto the purchased car for the exact term you modeled. None of those assumptions are guaranteed. Excess mileage charges on leases are brutal — most leases allow between ten and fifteen thousand miles per year, and anything over that runs twenty to cents per mile. If you drive eighteen thousand miles a year and lease a car with a ten-thousand-mile limit, you're looking at an extra fourteen hundred dollars at lease end that no calculator will predict for you unless you're honest about your actual driving habits. Similarly, the calculator can't account for maintenance differences. Most leases require you to follow a strict maintenance schedule and use approved service centers, while a purchased car gives you flexibility. If your purchased car needs a major repair at year two that your warranty doesn't cover, that's an unpredictable cost. But if your lease requires you to replace tires twice because the excess wear guidelines are strict, that's also unpredictable. The calculator won't help you with either scenario. There's also the opportunity cost question that most calculators ignore entirely. If you lease, you're putting down less cash upfront and keeping that money available for something else — an investment, a home improvement, an emergency fund. If you buy, you might need a larger down payment or a higher monthly loan payment. A proper financial comparison should factor in what you could earn by investing that money instead of tying it up in a vehicle. At a conservative seven percent annual return, the difference between putting down five hundred dollars on a lease versus five thousand dollars on a purchase could be worth over a thousand dollars after three years. Again, no standard calculator builds this in.
What I actually recommend
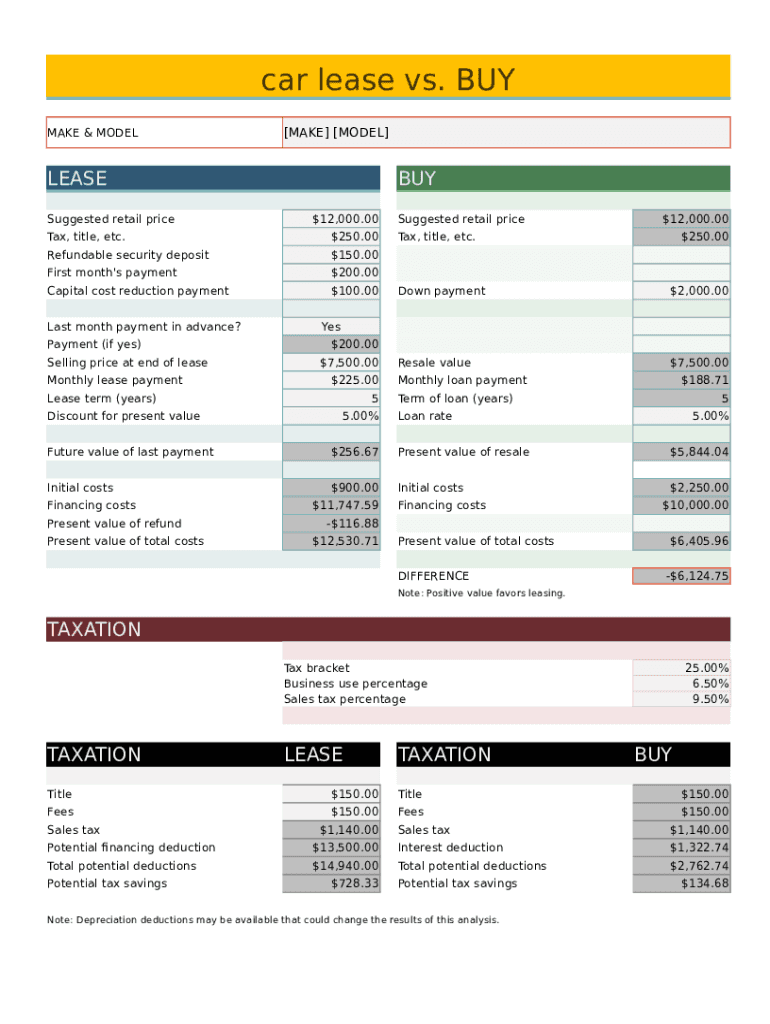
Find a calculator that lets you adjust the residual value and the resale value independently. Run the numbers with both the dealer's figures and your own adjusted figures. If the lease looks cheaper with the dealer's numbers but the purchase looks cheaper with your adjusted numbers, take that as a signal that the deal structure is favoring the lease through inflated residuals rather than genuine savings. In that case, either negotiate the residual down with the dealer or go with the purchase. It's almost always better to own the car than to lease it when the lease economics are built on optimistic depreciation assumptions. Also run a separate calculation for total cost of ownership including insurance, fuel, maintenance, and registration. These vary significantly between leased and owned vehicles but rarely get included in comparisons. A leased vehicle typically requires gap insurance and often higher collision deductibles, which adds fifty to eighty dollars a month. The purchase side might have lower insurance but higher maintenance costs as the car ages past warranty. Factor those in and you'll usually find the gap between the two options is much smaller than the monthly payment comparison suggests. The bottom line is that a Car Lease Versus Purchase Calculator is useful only if you understand what it's measuring and what it's leaving out. Get the real numbers from the dealer. Adjust the residuals to reflect actual market conditions. Account for taxes, mileage, and opportunity cost. Then decide based on the complete picture, not just the monthly payment difference. Most people who do that discover that the "better deal" they thought they found was an artifact of how the calculator was set up, not a real financial advantage.