What Actually Happens When You Refinance
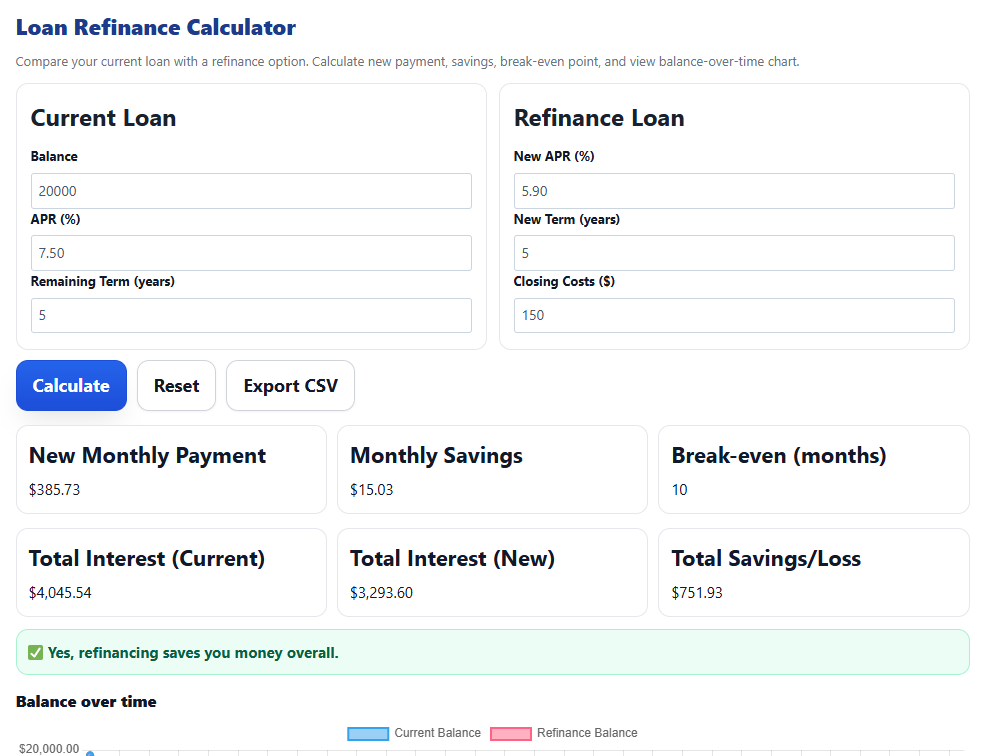
Most people use a Car Loan Refinance Calculator to figure out whether switching lenders will save them money. The reality is that these tools are decent starting points but they don't tell the full story. They take your current loan balance, remaining term, current rate, and the new rate you're being offered, then spits out a monthly payment estimate and total interest comparison. That's it. I spent three years working in auto lending and refinancing. One thing that comes up constantly: people run the numbers, see a lower monthly payment, and sign papers without checking what else changed. The calculator won't flag that for you. It just processes the inputs you give it.
How a Car Loan Refinance Calculator Actually Works
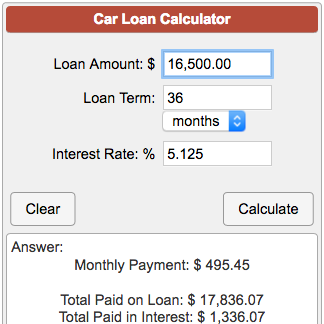
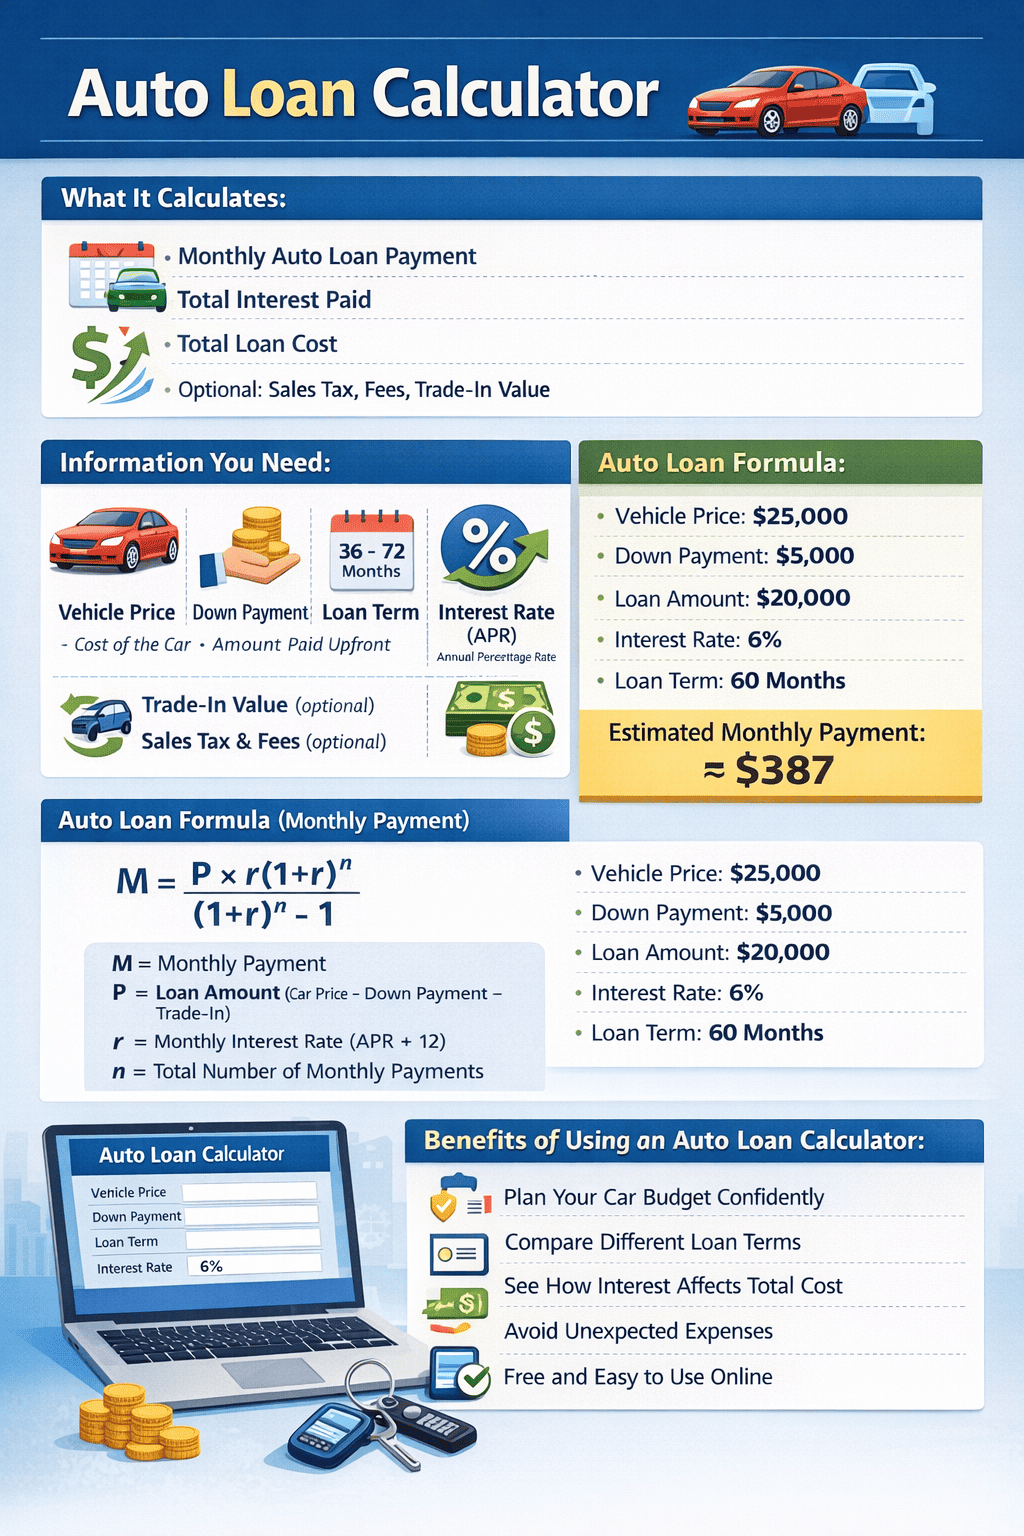
The basic formula behind every refinance calculator is the amortization formula. It takes the principal balance, divides by a factor that accounts for interest and the number of remaining payments, and gives you the monthly amount. Most online calculators use this same math, wrapped in a friendly interface. The key inputs are your current loan balance, your remaining number of months, your current interest rate, and the new rate you're being offered. Some calculators also factor in fees. Here's a practical example. I had a client once with $18,500 left on a loan at 7.2% with 42 months remaining. She was offered a refinance at 4.8%. The calculator showed her payment dropping from $448 to $434. A twelve dollar difference. Over four years that's roughly $576 in savings before any fees. She didn't refinance because the application fee alone was $295 and her credit had shifted slightly since she first got the loan. The margin was too thin. That's the thing calculators don't always make obvious. A seemingly significant rate drop can get eaten alive by origination fees, prepayment penalties, or a longer term that resets your amortization schedule. Your monthly payment might look better. You might pay more in total interest over the life of the loan.
The Problems With Standard Calculators
Most free calculators online assume a straightforward scenario. They don't handle things like negative equity, gap loans, or loans that were originally part of a package deal with extended warranties or service contracts rolled into the balance. I ran into this repeatedly. Someone would come to me with a loan that included a $2,400 tire and wheel protection plan that was part of the original finance amount. The calculator would treat the entire balance as pure loan principal and give misleading results. You have to manually strip out the non-loan components before plugging numbers in. Another issue is how different lenders calculate interest. Some use the daily balance method. Others use the standard amortization method. A calculator using one assumption and a lender using another will produce slightly different numbers. The discrepancy is usually small, maybe ten to twenty dollars over the life of a typical auto loan, but it adds up when you're comparing multiple offers. Prepayment penalties are the silent killer. Some contracts from the mid-2010s still have them. If your current loan charges a penalty for paying it off early, the calculator won't know about it unless you type it in manually. I've seen people lose hundreds of dollars because they assumed a simple refinance when their contract had a declining penalty schedule that still had several hundred dollars left on it.
Get the Full Details
What to Look for Beyond the Monthly Payment
Don't just look at the monthly payment. Look at the total cost. A longer term with a slightly lower rate can reduce your monthly obligation but cost you thousands more in interest. I once saw someone move from a 48-month loan to a 72-month loan. Monthly payment dropped by eighty dollars. Total interest paid went up by over two thousand dollars. The calculator showed both numbers clearly if you actually read past the first line of results. Credit score changes matter more than people expect. If your score has improved since you originally took out the loan, you may qualify for a significantly better rate. But if your score dropped, the opposite happens. Run the calculator with multiple rate scenarios based on different credit tiers. Most calculators let you adjust the rate manually, so do it. Try your current rate, the rate you were quoted, and a rate twenty basis points lower just to see the range. Fees add up fast. Application fees, title transfer fees, lien recording fees, and sometimes even document preparation fees. A legitimate refinance quote should itemize these. If a lender only gives you a rate and no fee breakdown, walk away. The real cost is hiding in those line items.
When Refinancing Makes Sense and When It Doesn't
Refinancing makes sense when your credit has improved significantly, when rates have dropped substantially since you originally financed, when you have a shorter term remaining and want to extend it to ease cash flow without paying more in total interest, or when you can combine multiple auto loans into one payment at a lower combined rate. It doesn't make sense when you're already near the end of your loan term and the fee structure eats any potential savings, when you have negative equity and would be borrowing more than the car is worth, when your contract carries a prepayment penalty that hasn't expired yet, or when you're extending a short remaining term into a much longer one and the total interest cost increases. There's also a timing consideration. If you've been making payments for less than six months on your current loan, many lenders won't even consider the refinance. They want to see a track record. Running a calculator at that stage is pointless. You'll waste your time and potentially harden your credit by submitting inquiries that go nowhere. The most practical approach is to gather your actual loan documents first. Pull your payoff amount from your current lender. Check your remaining term. Note any fees or penalties in the contract. Then plug the real numbers into a Car Loan Refinance Calculator. Don't estimate your balance. Don't guess your rate. Use the actual figures and compare at least three offers from different lenders before making a decision.