Building a Card Comparison Worksheet That Doesn't Waste Your Time
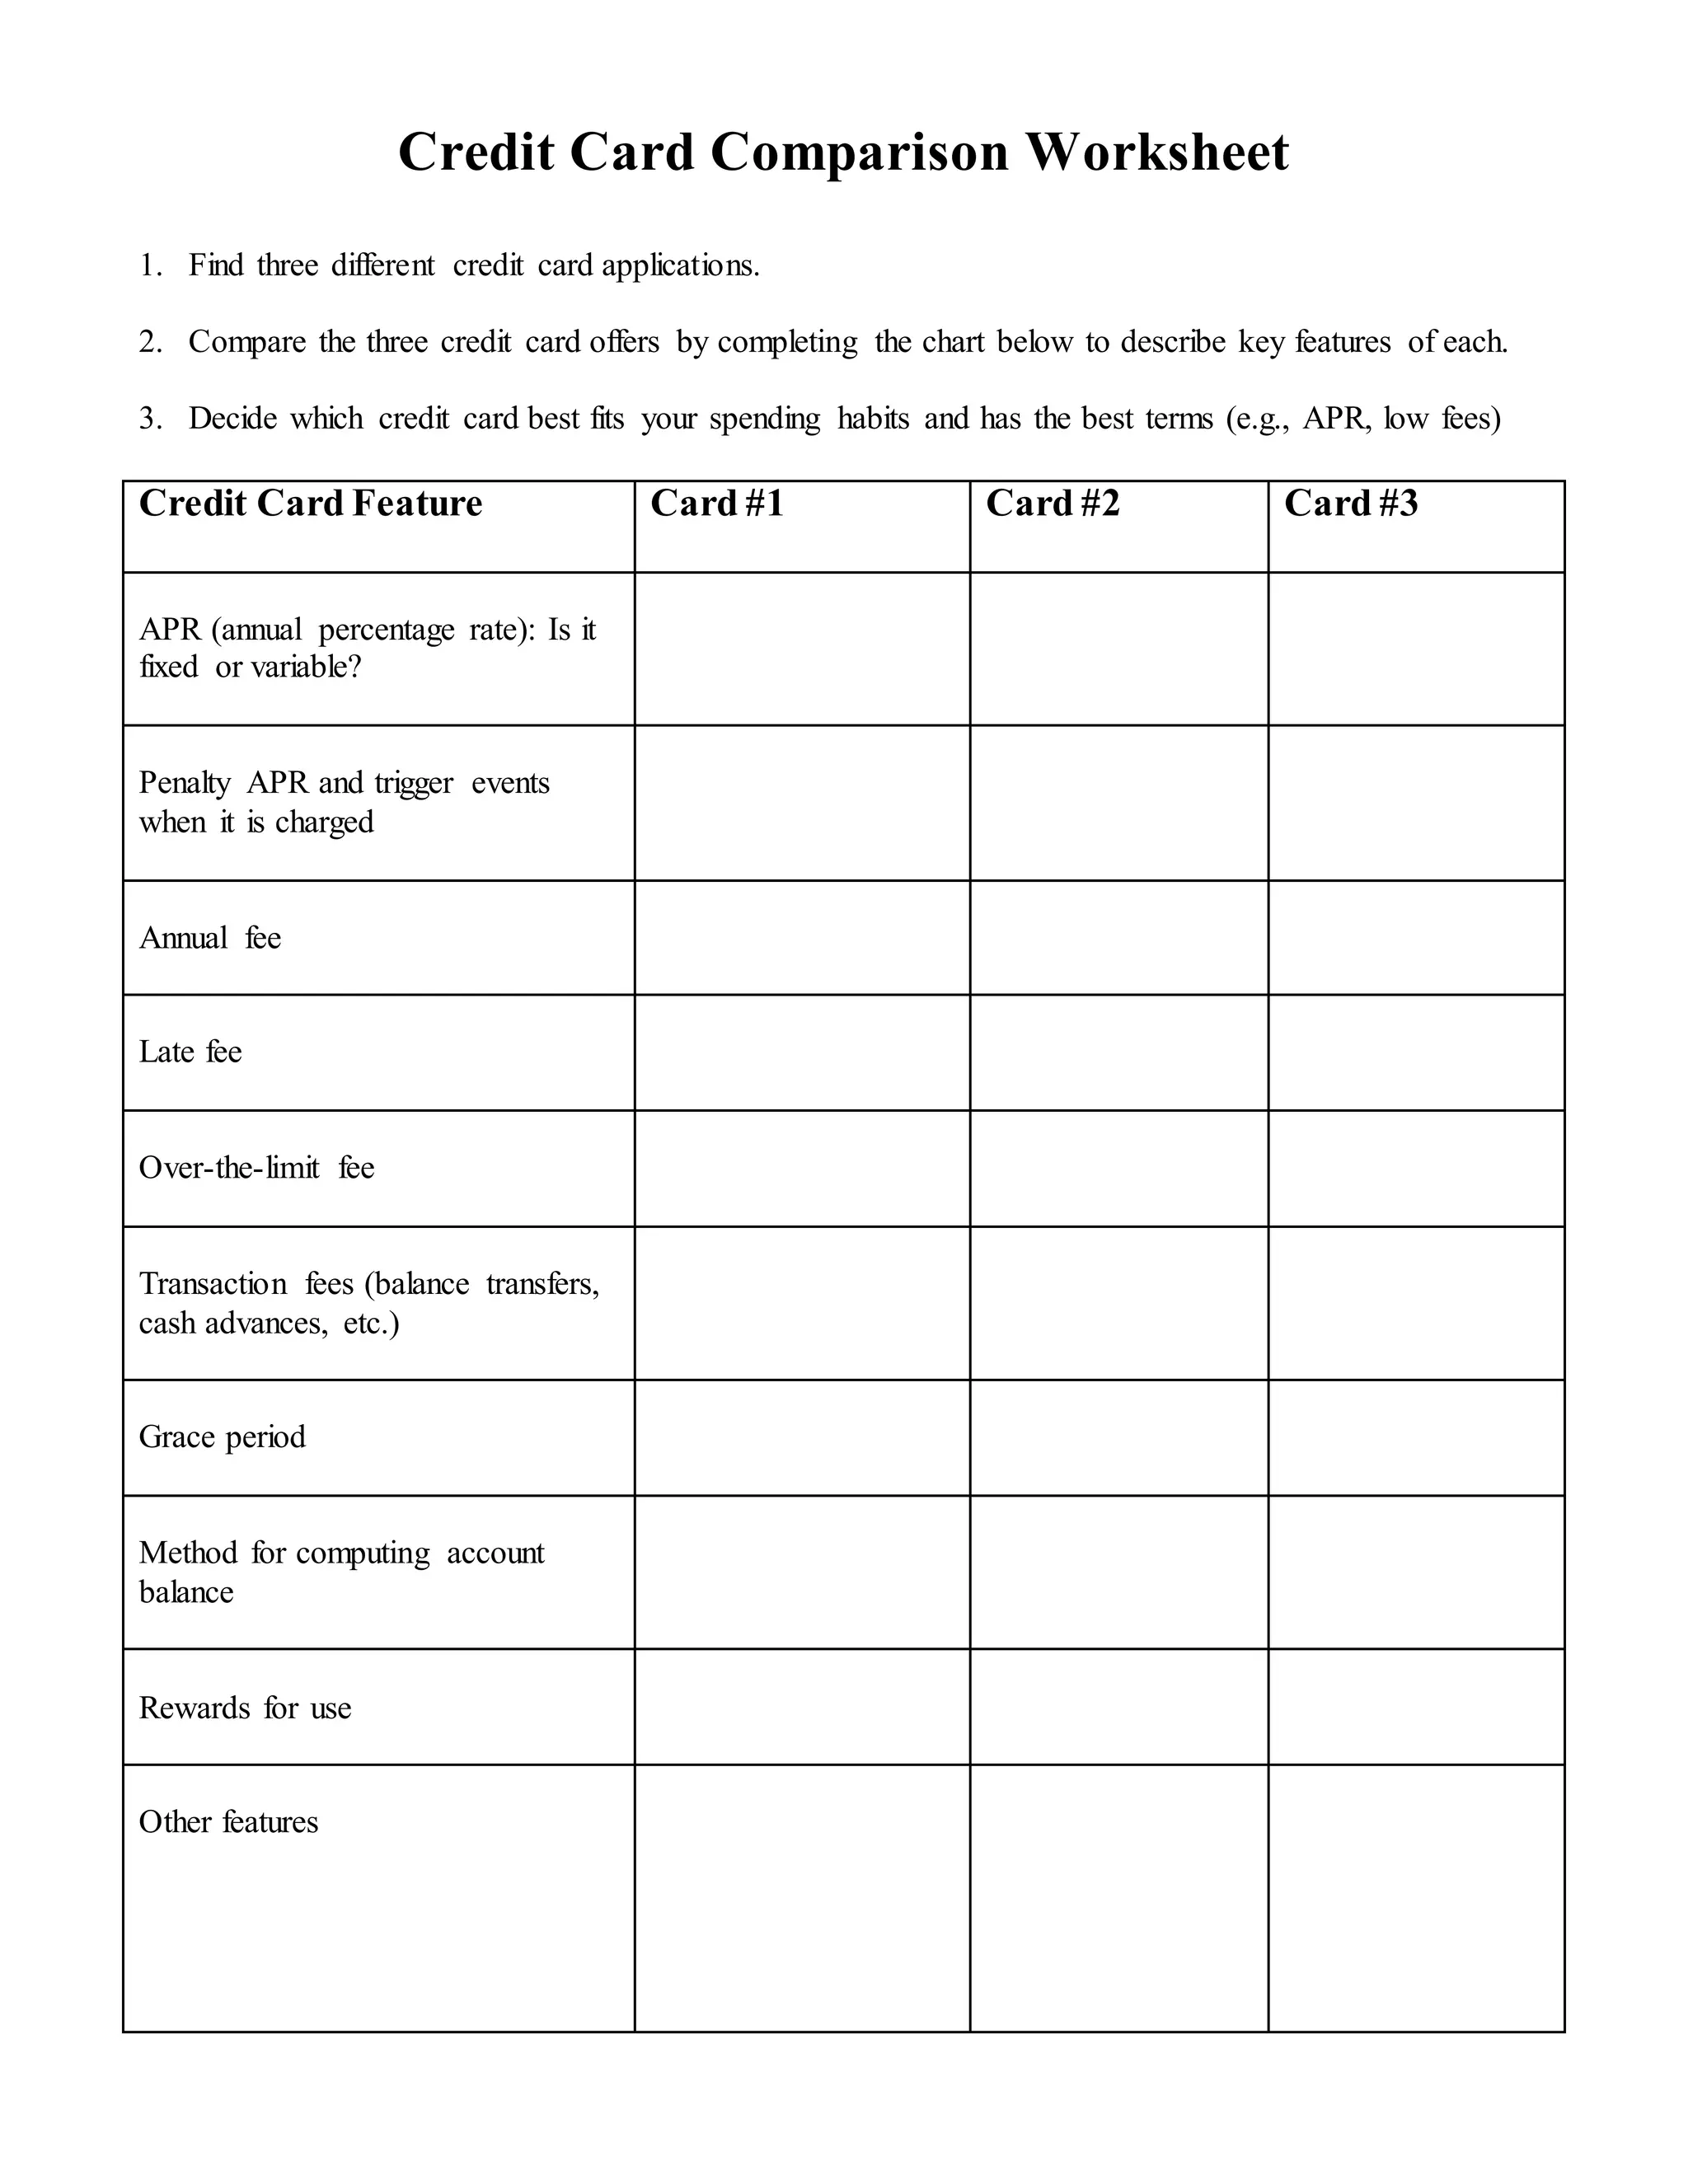
Most people try to compare credit cards using spreadsheets they pull together in about ten minutes. Those spreadsheets are almost always useless because they miss the fields that actually matter to your bottom line, and they make it impossible to factor in variables like spend velocity and redemption flexibility. I spent about three months fixing my own broken version after we almost signed our team up for a rewards card that looked great on paper but was terrible for how we actually spent money. The core of a functional Card Comparison Worksheet comes down to six sections, and you should build them in this order rather than the way most templates organize them. Start with the hard numbers first because those don't change based on opinion. List each card you're considering in its own row, then create columns for annual fee, introductory APR duration, regular APR range, balance transfer fee percentage, cashback rate on purchases, and any spending caps or category restrictions. That alone will eliminate about sixty percent of cards that look competitive at first glance but have structural flaws like zero intro periods or 3 percent annual fees. After the hard numbers, add a weighted scoring column. This is where most people mess up. You need to assign weightings based on your actual usage pattern, not generic advice you read online. If your business spends heavily on travel, give travel redemptions a weight of 0.4. If you mostly pay vendors in bulk and want simple statements, put the weight on statement credits and point flexibility. I had a client who was comparing fifteen cards and hadn't thought through whether her team would actually use lounge access or if she just liked the sound of it. We removed that category from her scoring and reassigned the weight to purchase protection benefits, which changed the winning card entirely.
The third section is where people usually stop, but it's not close to enough. Add a column for effective annual cost. This is calculated by taking the annual fee and subtracting any guaranteed first-year rewards based on your projected monthly spend. A card with a 95 dollar annual fee that gives you 500 dollars in statement credits during the first year has a negative effective annual cost of negative 405 dollars. That card is mathematically profitable to hold regardless of APR. A card with zero annual fee but zero rewards and a higher APR could end up costing you more over twelve months if you carry a balance. Run the effective annual cost for at least two years of ownership before you make any decisions.
The Fields Most People Forget
There are about eight fields that show up in every beginner comparison spreadsheet and then another dozen that don't, and the difference between those two groups determines whether you'll regret the decision six months later. Foreign transaction fees matter if anyone on your team travels internationally even once a quarter. Lost luggage reimbursement matters if you fly commercially more than four times a year. Purchase protection and extended warranty coverage matter if you buy equipment worth more than a few hundred dollars on any of these cards. Here's the thing nobody tells you about purchase protection and extended warranty benefits: the coverage limits are usually much lower than you expect, and the claim process can take ninety to one-hundred and twenty days. I had to file an extended warranty claim on a laptop purchased with a corporate card, and the entire process took four months. The card issuer required the original receipt, the manufacturer's warranty documentation, and a third party repair estimate. Having a Card Comparison Worksheet that tracks the exact claim requirements for each card upfront saved us from picking a card with generous stated benefits that had a notoriously slow claims department. The redemption method column is another field people skip at their own risk. Some cards auto-apply credits to your statement, which is simple and fast. Others require you to manually redeem points through a portal, and the portal value is typically twenty percent lower than the advertised point valuation. A card that advertises 50,000 points worth 1,000 dollars might actually be worth 800 dollars if you redeem through the travel portal versus the statement credit option. Always check the redemption floor before you trust the headline number.
Get the Full Details

A Real Problem I Ran Into
Last year I was comparing a batch of cards for a mid-size logistics company, and everything looked clean on the surface. Two of the five finalists had identical effective annual costs, similar APR ranges, and nearly the same rewards structure. The tiebreaker came from a field most people ignore entirely: the billing cycle cutoff date and grace period length. One card had a billing cycle that ended on the 28th of each month with a full forty-five day grace period from statement closing to payment due date. The other card had a billing cycle that ended on the 15th but only offered a twenty-one day grace period. For a company that runs payroll biweekly and processes vendor payments on fixed schedules, that twenty-one day window created a cash flow problem. They would have to pay the card balance before they received funds from their customers on certain cycles. Switching to the card with the longer grace period gave them approximately eleven extra days of operating float each cycle, which mattered more than the slightly higher rewards rate on the other card. The Card Comparison Worksheet caught this because I had added a cash flow alignment score that factored in the company's specific payment and receivable schedules.
Advanced Pitfalls That Beginners Miss
The first counter-intuitive insight is that a higher rewards rate is not always better if the redemption options are narrow. A card offering 2 percent unlimited cashback on everything is often superior to a card offering 5 percent on rotating categories and 3 percent on dining, because the 5 percent categories change quarterly and require active monitoring. Most people fail to track the category rotation schedule and end up earning the lower rate anyway. I've seen teams spend more time trying to optimize category spending than they would have saving by switching to a flat-rate card. The second common error involves underestimating the impact of credit limit changes. Card issuers frequently adjust limits after six to eighteen months, especially if you carry a balance or use a large percentage of your available credit. A card advertised with a fifteen thousand dollar limit might get reduced to eight thousand after your second statement if your utilization goes above thirty percent. This directly affects your ability to book travel or make large purchases without hitting your limit, and it can also trigger a hard inquiry or account review that temporarily impacts your credit score. Factor limit stability into your comparison by looking at issuer policies and customer complaints about sudden limit reductions.
Where This Approach Breaks Down
A Card Comparison Worksheet is not useful if you only have one or two cards to evaluate. The overhead of building the spreadsheet, researching redemption values, and calculating effective annual costs takes about forty-five minutes the first time you set it up properly. That time investment only pays off when you're comparing four or more cards simultaneously. If you're just choosing between a current card and one new alternative, a simple side-by-side list of the top five attributes will do the same job in five minutes. The worksheet also becomes unreliable when you cannot accurately project your annual spend by category. Every recommendation in the spreadsheet depends on your estimated spending numbers being realistic. If you estimate three thousand dollars in travel spending but actually spend nine hundred, your card ranking will be completely wrong. I've recommended cards that ranked first in the worksheet and ended up being the worst choice because the underlying spend assumptions were optimistic by a factor of three. Double-check your projections against your actual historical spending before you trust the output. Finally, these worksheets don't capture benefit changes that happen after you sign up. Issuers revise rewards rates, add category caps, retire lounge access, and change welcome offers frequently. The terms you see today when you fill out the worksheet may be different by the time you submit your application next month. Always verify the current terms on the issuer's website before making a final decision, and keep a dated copy of whatever terms you used in your comparison so you can track whether anything shifted during the evaluation period.

If you need a starting template, you can find a basic Card Comparison Worksheet structure that includes the effective annual cost formula and the weighted scoring system by searching for corporate card comparison spreadsheet templates from major financial advisory firms. Just don't use it without adding the cash flow alignment column and the redemption floor adjustment. Those two additions are what separate a spreadsheet that looks good from one that actually prevents you from making a costly mistake.


