Building a Cash Flow Analysis That Actually Works
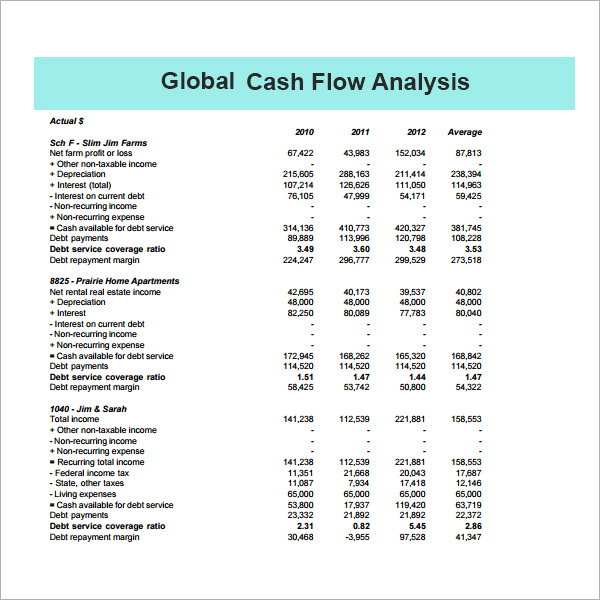
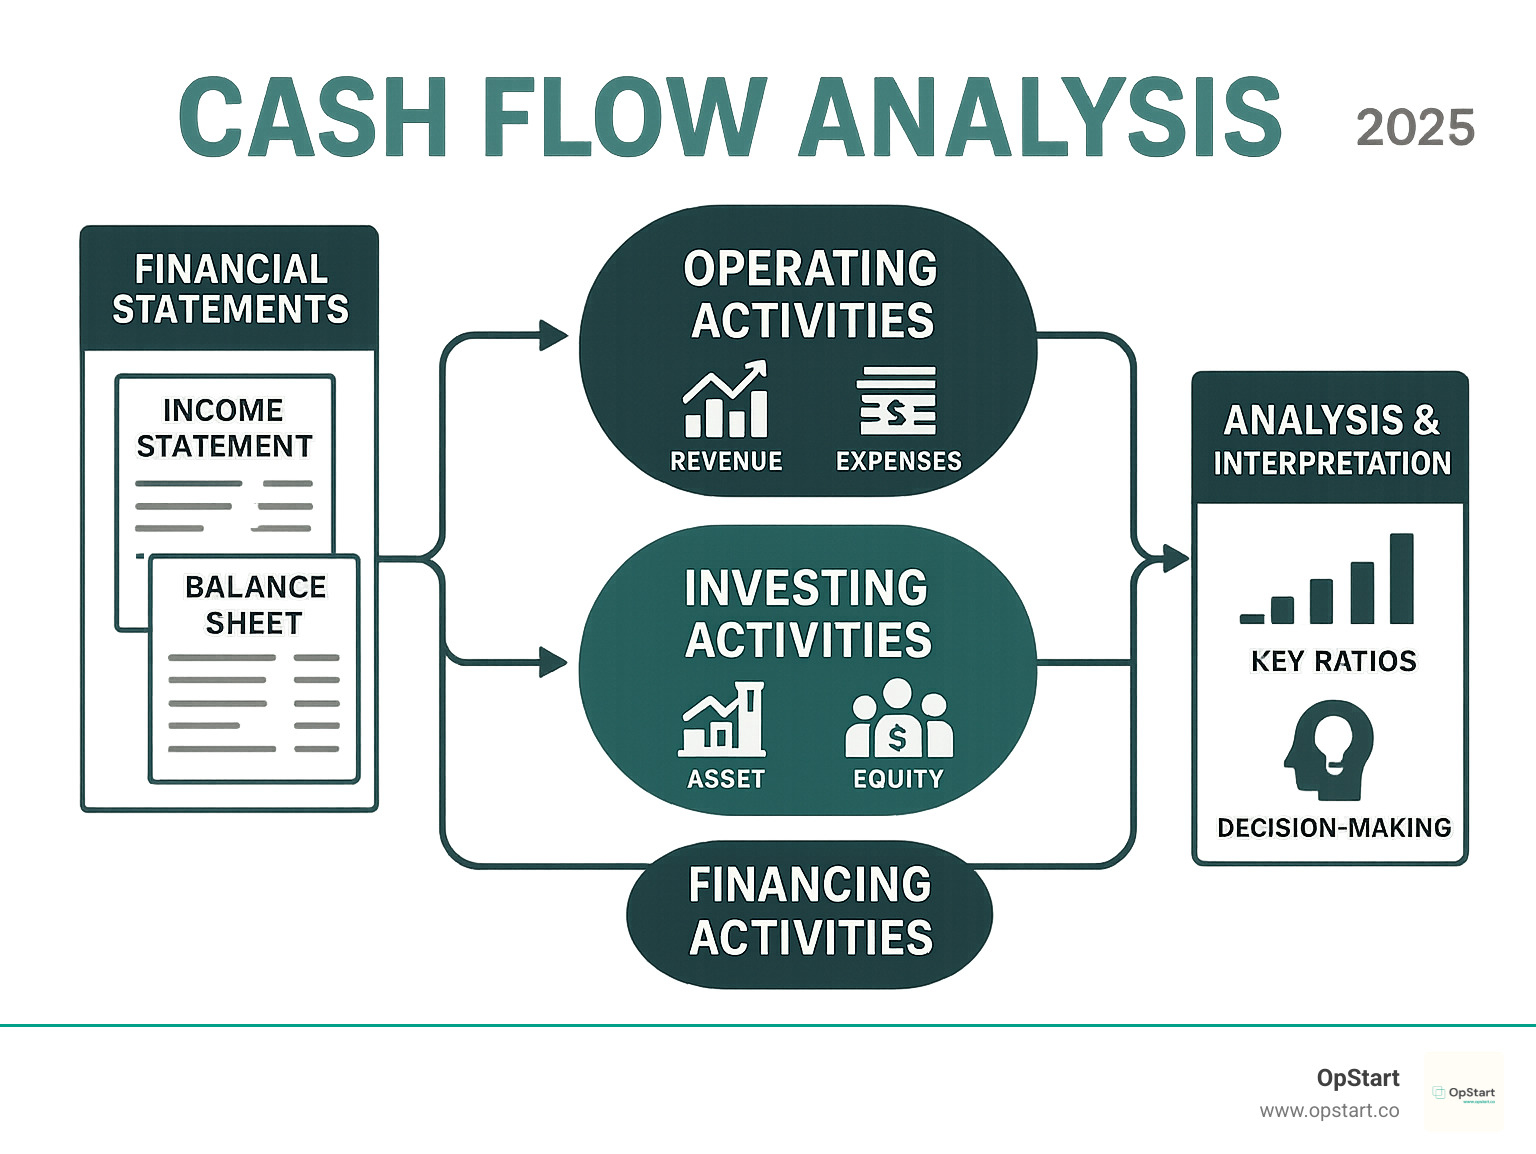
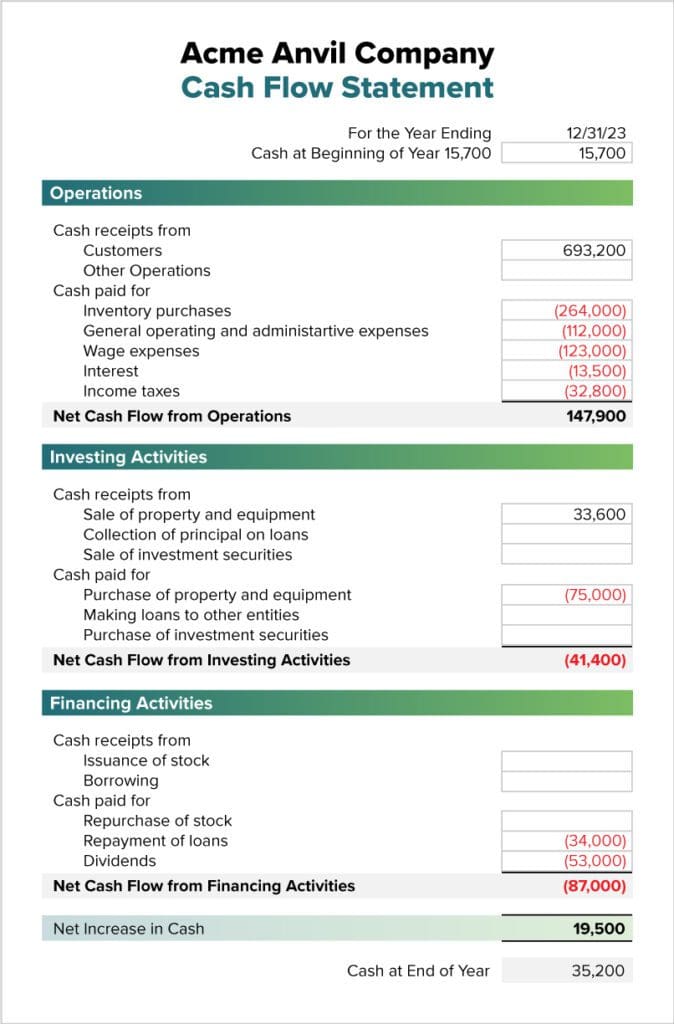
Cash Flow Analysis is usually taught in textbooks as a clean three-statement exercise: operating activities, investing activities, financing activities. Real life doesn't work that way. I spent about four years doing monthly close processes for a mid-market manufacturing company before I stopped trying to make spreadsheets match perfectly and started accepting that the real work is figuring out where the discrepancies live. The basic method is straightforward enough. You take your income statement and adjust for non-cash items like depreciation and amortization. Then you move through changes in working capital accounts — accounts receivable, inventory, accounts payable. That gives you operating cash flow. From there you look at capex, debt payments, equity transactions. The textbook gets you to the right place on paper.
Getting Your Cash Flow Analysis Right on the First Pass
Here's where most people mess up. They build the analysis from the bottom of the income statement and never verify it against the actual bank balance movements. I learned this the hard way. In 2019, I was reconciling a client's cash flow statement and the numbers looked fine on the surface. Operating cash flow was positive, investing was negative as expected from equipment purchases, financing showed debt paydown. Everything totaled correctly. Two weeks later, their bank called about an overdraft. The analysis was perfect and completely wrong because it missed a $47,000 intercompany transfer that had sat in a suspense account for six months. The cash was moving, but nobody was looking at the right place. The workaround was brutal but simple. I stopped building the analysis from the income statement entirely and started from the bank statement instead. Every line item on the bank feed, categorized and tagged, then aggregated back up to the cash flow categories. It took longer to set up initially — roughly three weeks of mapping transactions — but once the categorization rules were in place, the reconciliation time dropped from about two hours per month down to maybe twenty minutes. More importantly, nothing could hide anymore. There's a counter-intuitive thing about cash flow analysis that beginners rarely catch. A company can have strong operating cash flow and still be going under. I've seen this happen with vendors who front-load revenue recognition or offer aggressive early payment discounts that distort the picture. The cash comes in fast in one month, looks great on paper, and then disappears the next month when those same customers stop paying or the discounts become unsustainable. What actually matters is the consistency and predictability of the cash flow, not the peak number.
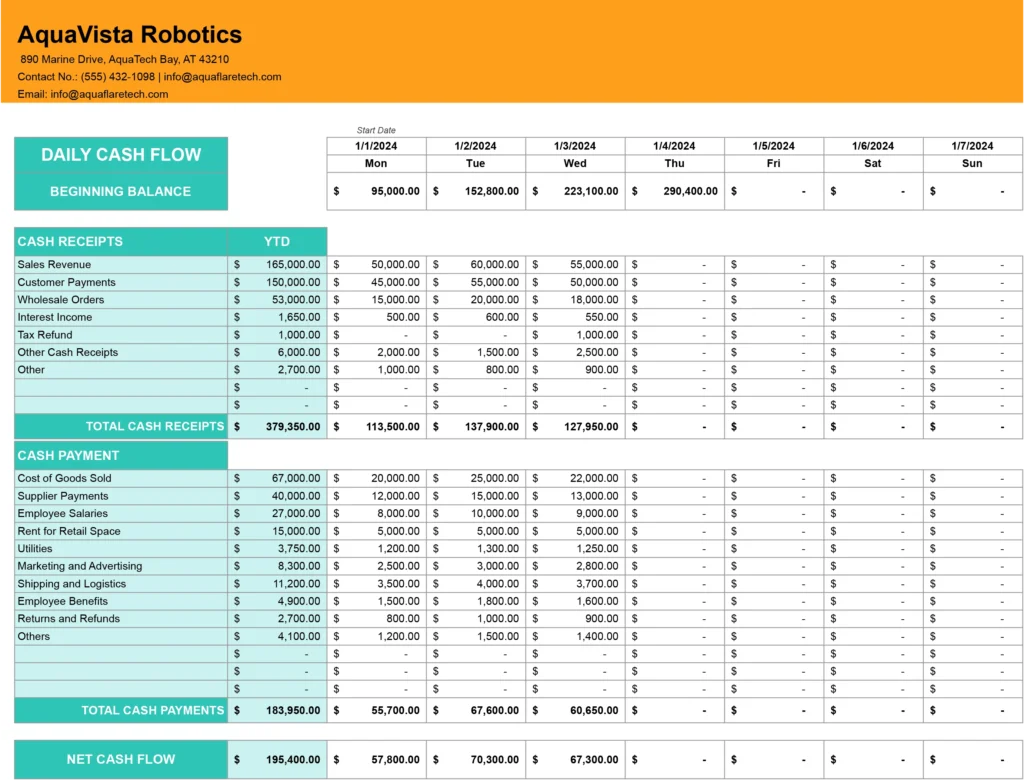
Another thing nobody warns you about is the treatment of restricted cash. If a company has cash locked in a margin account or a debt service reserve, standard cash flow analysis tools often ignore it or bury it in notes. That restricted cash might represent five to fifteen percent of total liquidity depending on the industry. For construction companies especially, this can be massive. I worked with a firm that had over a million dollars in restricted cash tied to performance bonds. Their reported cash position looked comfortable until someone actually needed to access those funds and couldn't. The standard tool for this work is a spreadsheet. Yes, that's what I just said. Excel or Google Sheets remains the most flexible option for most organizations. The problem is that spreadsheets accumulate errors over time. I've seen models with fifty-plus manual adjustments where nobody could trace a single number back to its source. The alternative is dedicated cash flow management software like Mosaic or Float, which connect directly to bank feeds and automate most of the categorization. These tools can cut your monthly analysis time from two hours to fifteen minutes if your chart of accounts is reasonably clean. If your chart of accounts is a mess, they'll just automate the mess faster. One limitation you need to accept upfront: cash flow analysis is backward-looking by nature. It tells you what happened, not what will happen. Forecasting is a separate exercise that requires additional assumptions about customer payment behavior, seasonal revenue patterns, and capital expenditure timing. Some companies try to combine both into a single report, but that tends to produce garbage results because the error margins compound. Keep them separate. Build your analysis on actuals, build your forecast on assumptions, and never confuse the two.
Get the Full Details
For small businesses running monthly analysis, the biggest practical issue is typically mismatched accounting periods. Revenue gets recorded when invoices are sent, but cash comes in thirty to sixty days later. If you're using accrual accounting and trying to do a cash flow analysis without proper timing adjustments, you'll see fluctuations that don't reflect reality. The fix is usually a simple aging schedule layered on top of your main analysis. Track when invoices were issued, when they're expected to pay, and when they actually paid. Three buckets: current, thirty days, sixty plus. That alone will eliminate most of the confusion. If you're starting from scratch and want something to work with, most template libraries have cash flow analysis templates, though I'd strongly recommend building your own rather than downloading a generic one. A downloaded template won't account for your specific revenue cycles, your industry's working capital norms, or your actual chart of accounts structure. Building it yourself takes about two weeks of evenings, but you'll actually understand every line item and know exactly where to look when something breaks. That second thing matters more than people realize. When the numbers look wrong and you're at 11 PM trying to figure out why, having built the model means you can trace the issue in ten minutes. Someone using a downloaded template will spend three hours Googling the same problem.